Retail Channel $ Update – August Monthly & September Advance
In September, YOY Commodities’ inflation rose to 4.6% from 4.0%, largely due to Gasoline. High cumulative inflation vs 21 can slow $ales growth and of course, current inflation changes can affect growth, but not always. We saw examples of all of these in September. Total Retail $ were +6.8% vs 25, 52% above the avg 92>25 lift. Relevant Retail’s inflation dropped from 1.8% to 1.7% and sales were +4.9%, 10% above their avg. The situation is definitely complex. We’ll continue to track the retail market with data from 2 reports provided by the Census Bureau and factor in targeted CPIs.
The Census Bureau reviewed & corrected the 18>26 data for the Monthly Retail Sales Reports. They still publish a Monthly and an Advance Report. Both are derived from sales data gathered from retailers across the U.S. and are published monthly at the same time. The Advance Report has a smaller sample size so it can be published quickly – 2 weeks after month end. The Monthly Report includes data from all respondents, so it takes longer to compile the data – about 6 weeks. Although the sample size for the Advance report is smaller, it has been proven to be statistically accurate with the Monthly reports. The biggest difference is that the full sample in the Monthly report allows us to “drill” a little deeper into the retail channels.
We will begin with the August Monthly Report and then go to the September Advance Report. Our focus is comparing to last year but also to 21 & 19. We’ll show both actual and the “real” change in sales as we factor inflation into the data.
Both reports include the following:
- Total Retail, Restaurants, Auto, Gas Stations and Relevant Retail (removing Restaurants, Auto and Gas Stations)
- Individual Channel Data – This is more detailed in the Monthly reports, and we’ll focus on Pet Relevant Channels.
The data will be presented in detailed charts to facilitate visual comparison between groups/channels. The charts will show 11 separate measurements. To save space they will be displayed in a stacked bar format for the channel charts.
- Current Month change – % & $ vs previous month
- Current Month change – % & $ vs same month last year and vs 2021.
- Current Month Real change vs last year and vs 2021 – % factoring in inflation
- Current Ytd change – % & $ for this year vs last year, 2021 & 2019.
- Current Ytd Real change % for this year vs last year and vs 2021 and 2019
- Monthly & Ytd $ & CPIs for this year vs last year and vs 2021 which are targeted by channel will also be shown. (CPI Details are at the end of the report)
First, the August Monthly. All but Relevant Retail were up from July and there were no actual sales drops. There were 4 “real” drops. Gas Stations are selling less product than in 2025 & 2019. However, Relevant Retail is all positive again. They’ve been all positive in 27 of the last 29 months. ($ are Not Seasonally Adjusted)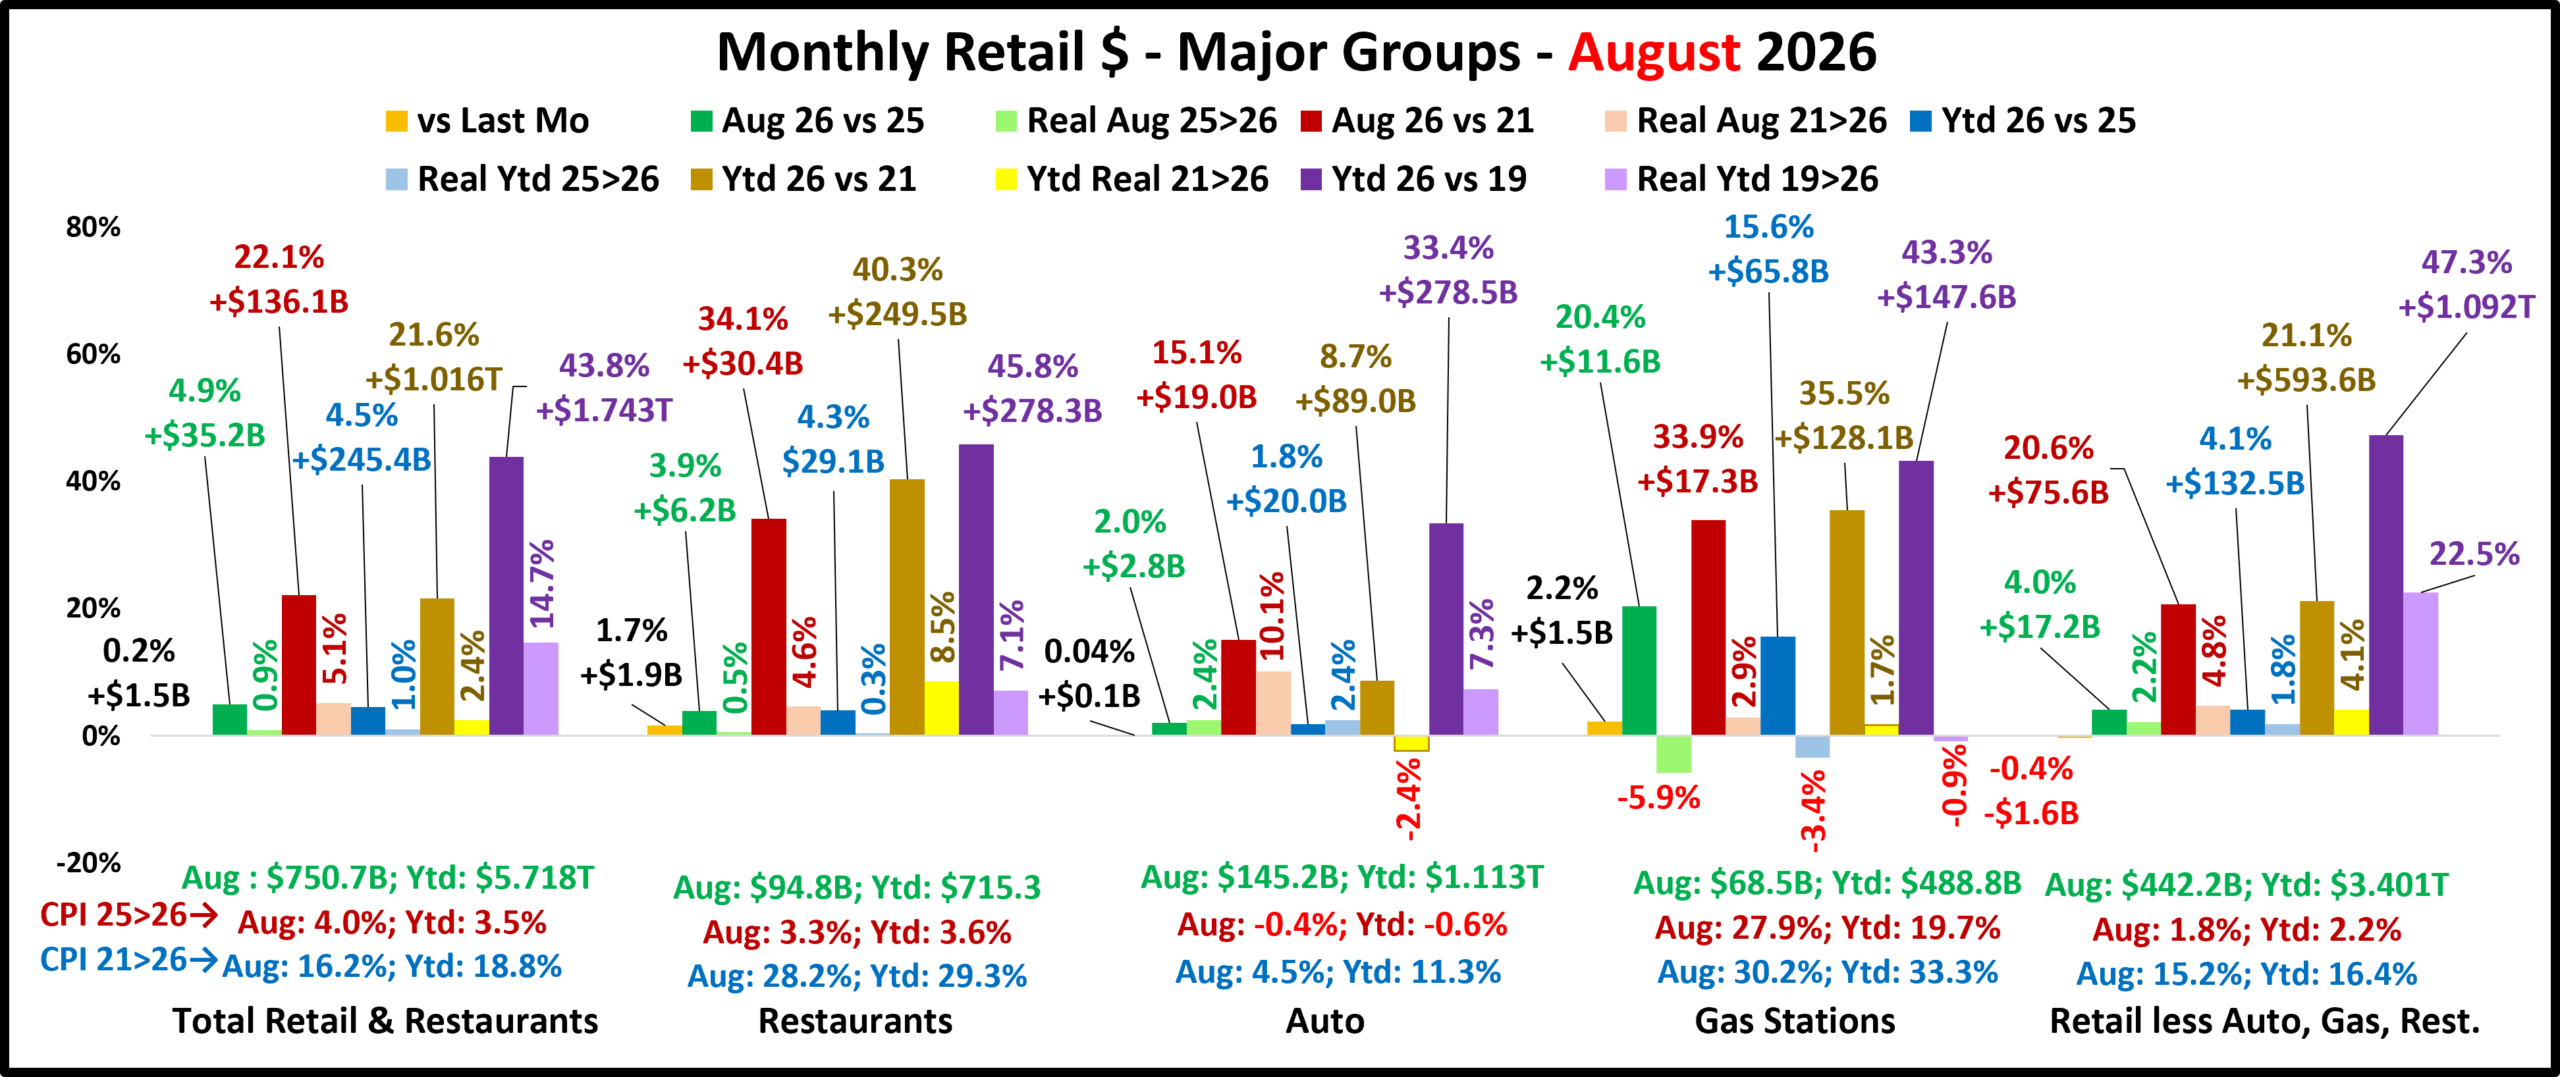
The Revised Aug Monthly is -$34.1B below the original Advance. Restaurants: -$13.8B; Auto: -$2.6B; Gas Stations: +$1.1B; Relevant Retail: -$18.8B. The lifts from July were not unexpected. A Jul>Aug increase in Total Retail has happened in 80% of the years since 1992. However, the 0.2% lift was -91% less than the 2.1% avg. There were no drops in actual sales, but there were 4 “real” drops (Auto & Gas) – 5 in Jun/Jul, 6 in May, 9 in Apr, 7 in Mar, but none in Dec>Feb. 3 groups were all positive – 4 in Jun/Jul, 3 in May, 1 in Apr, 2 in Mar and 4 in Feb. Restaurants have the biggest increase vs 21, but Relevant Retail is #1 vs 19 and in 19>26 “real” performance. However, only 47.6% of their growth is real.
Now, let’s see how some Key Pet Relevant channels did in August in the Stacked Bar Graph Format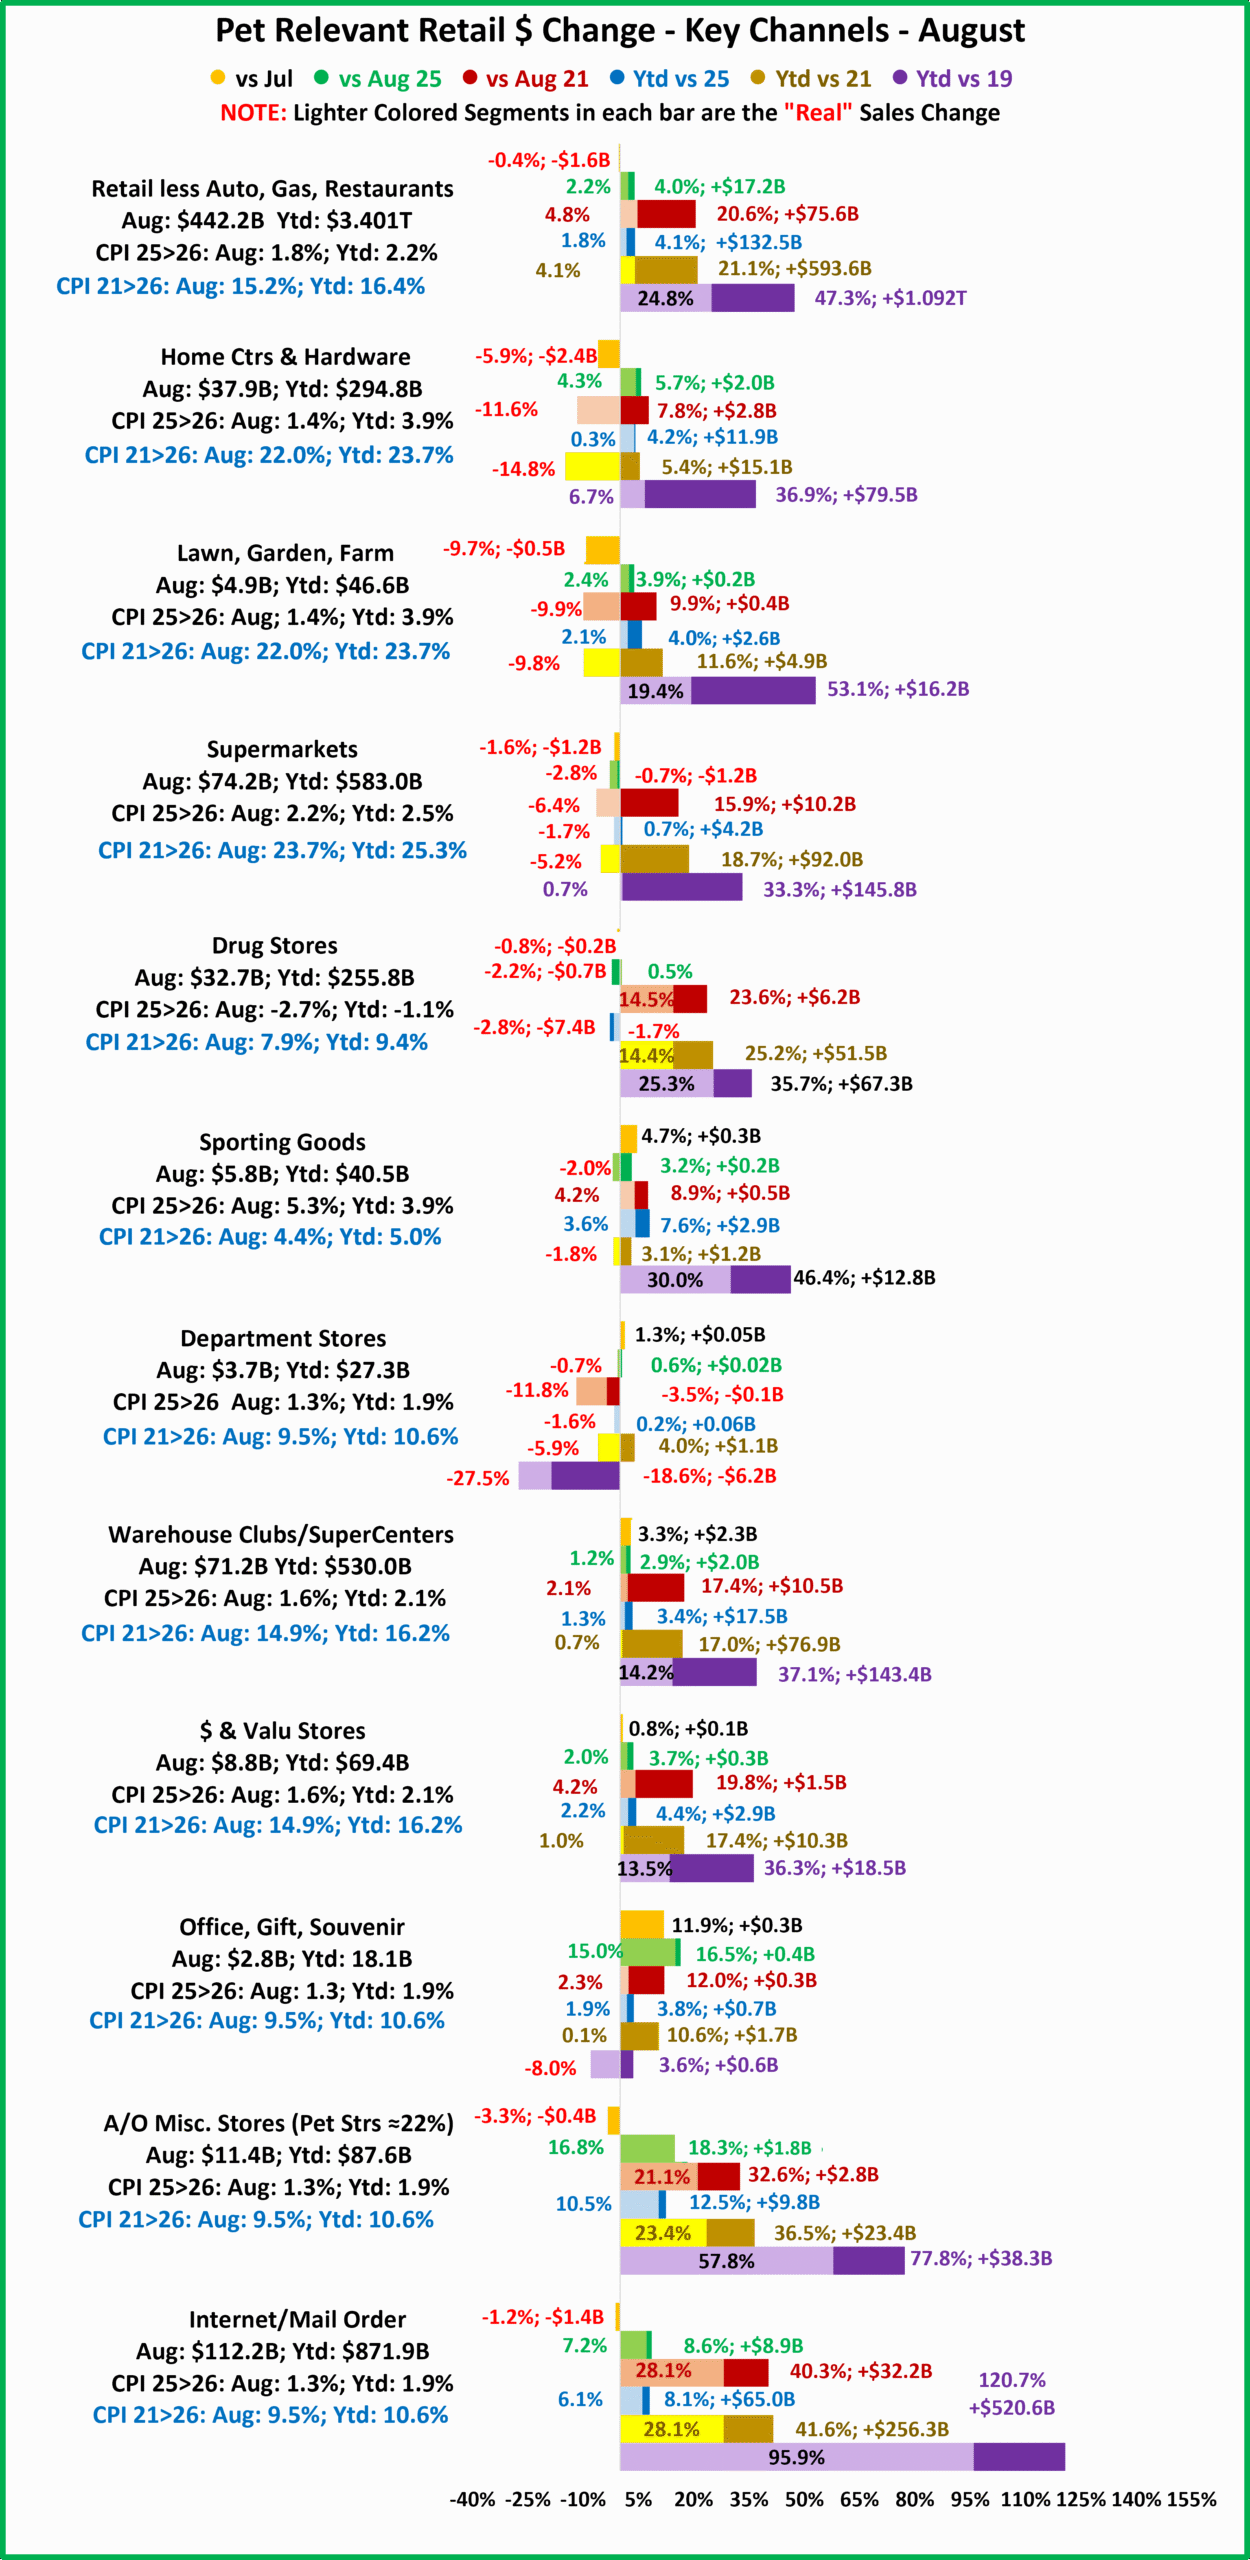
Overall– 5 of 11 were up from July. Vs Aug 25, 9 were actually and 8 “really” up. Vs Aug 21, 10 were up but only 7 were real lifts. Vs 2019, Only Dept Strs were actually & really down, but Off/Gift/Souv was really down.
- Building Material/Farm Stores – The pandemic focus on home has produced $ growth of 36.2% since 2019. Prices for the group are +22.0% from 21 and +28.3% from 2019, which is impactful. The Spring lift is over, HomeCtr/Hdwe Sales vs July were -5.9% and -9.7% for Farm. Vs other years, both are actually up for all and only really down vs 2021. Bldg Mat/Farm’s 19>26 real growth was 8.7% avg: 1.2%. HomeCtr/Hdwe: Ytd: 4.2%; Avg 19>26 Growth: 4.6%, Real: 0.9%; Farm: Ytd: +6.0%; Avg: 6.3%, Real: 2.6%
- Food & Drug – Both are essential. Except for the COVID food binge, they tend to have smaller changes in $. Vs July: Supermarkets: -1.6%; Drug: -0.8%. In terms of inflation, Groceries are 2.2%, while Drug/Med products are still deflating, -2.7%. Drug Stores are actually down vs 25 and really down Ytd. 70.9% of their 2019>26 growth is real. Supermarkets’ actual $ are up for all but vs Aug 25, but they are only “really” up vs 2019. Plus, only 0.02% of their 19>26 increase is real growth. Supermarkets: Ytd: +0.7%; Avg 19>26: +4.2%, Real: +0.1%; Drug Stores: Ytd: -2.8%; Avg: +4.5%, Real: +3.3%.
- Sporting Goods Stores – They also benefited from the pandemic in that consumers turned to self-entertainment, especially sports & outdoor activities. Sales are +4.7% vs July. They are only really negative ytd vs 21 and vs Aug 25. Prices stopped deflating. Deflation started in April 23 and was a big change from +1.1% in 22>23 & +7.9% in 21>22. This caused 64.7% of their 46.4% lift since 2019 to be real. Ytd: +7.6%; Avg 19>26: +5.6%; Real: +3.8%
- Gen Mdse – $ vs July: SupCtr/Club; +3.3%; $ Strs: +0.8%; Dept Strs: +1.3%. All comparisons were up for $ Strs & SupCtr/Club. Dept Stores are negative for all but actual vs Aug 25 & YTD vs 25 & 21. Their Actual sales are even -18.6% from 2019 (real:-27.5%). The other channels have an average of 37.0% in 19>26 growth. SupCtr/Club: Ytd: +3.4%; Avg 19>26: 4.6%, Real: 1.9%; $/Value Strs: Ytd: +4.4%; Avg: +4.5%, Real: +1.8%; Dept. Strs: Ytd: +0.2%; Avg: -2.9%, Real: -4.5%.
- Office, Gift & Souvenir Stores – Sales are +11.9% vs July. They are actually up for all and only really down Ytd vs 2019. Their recovery restarted Jun/Jul 25, but took off in Oct, slowed Nov, grew Dec, slowed Jan>Mar, grew in Apr, slowed in May, restarted in June, slowed a little in July, then grew in August. Ytd: +3.8%; Avg Growth Rate: 0.5%, Real: -1.2%
- Internet/Mail Order – Sales are -1.2% vs July but still set an August record. All YOY measurements are positive, but their YOY growth, +8.6%, is only 75.4% of their average since 2019. However, 79.5% of their 120.7% growth since 2019 is real. Ytd: +8.1%; Avg Growth: +12.0%, Real: +10.1%. As expected, they are by far the growth leader since 2019.
- A/O Miscellaneous – Pet Stores are 22>24% of total $. In May 2020 they began recovery which reached $100B for the 1st time in 22. In 23 their $ fell Jan>Feb, grew Mar>May, fell Jun>Aug, rose Sep>Nov, fell Dec>Jan 24, grew Feb>May, fell Jun>Sep, grew Oct, fell Nov, rose Dec, fell Jan>Feb 25, grew Mar>May, fell Jun>Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb/Mar, fell Apr, rose May/Jun, fell Jul/Aug. They’re all positive & are #2 in the increase vs 19 & vs 21. Also, 74.3% of their 77.8% growth since 2019 is real. Ytd: +12.5%; Avg 19>26: 8.6%, Real: +6.7%
August had a small lift vs July, -91% below avg. Relevant Retail was -0.4% (avg: +2.8%). Only 5 small channels were up. The YOY lift vs 25 was 8% above avg for Total, but -10% below avg for Relevant Retail. All 5 big groups & 9 of 11 smaller channels had lifts. Prices are only deflating in Auto & Drug, but cumulative inflation has an impact, as only 7 of 11 channels were really up vs Jul 21. Recovery is slow. In Sep, the commodities CPI rose from 4.0% to 4.6%. Let’s see if it impacts Retail.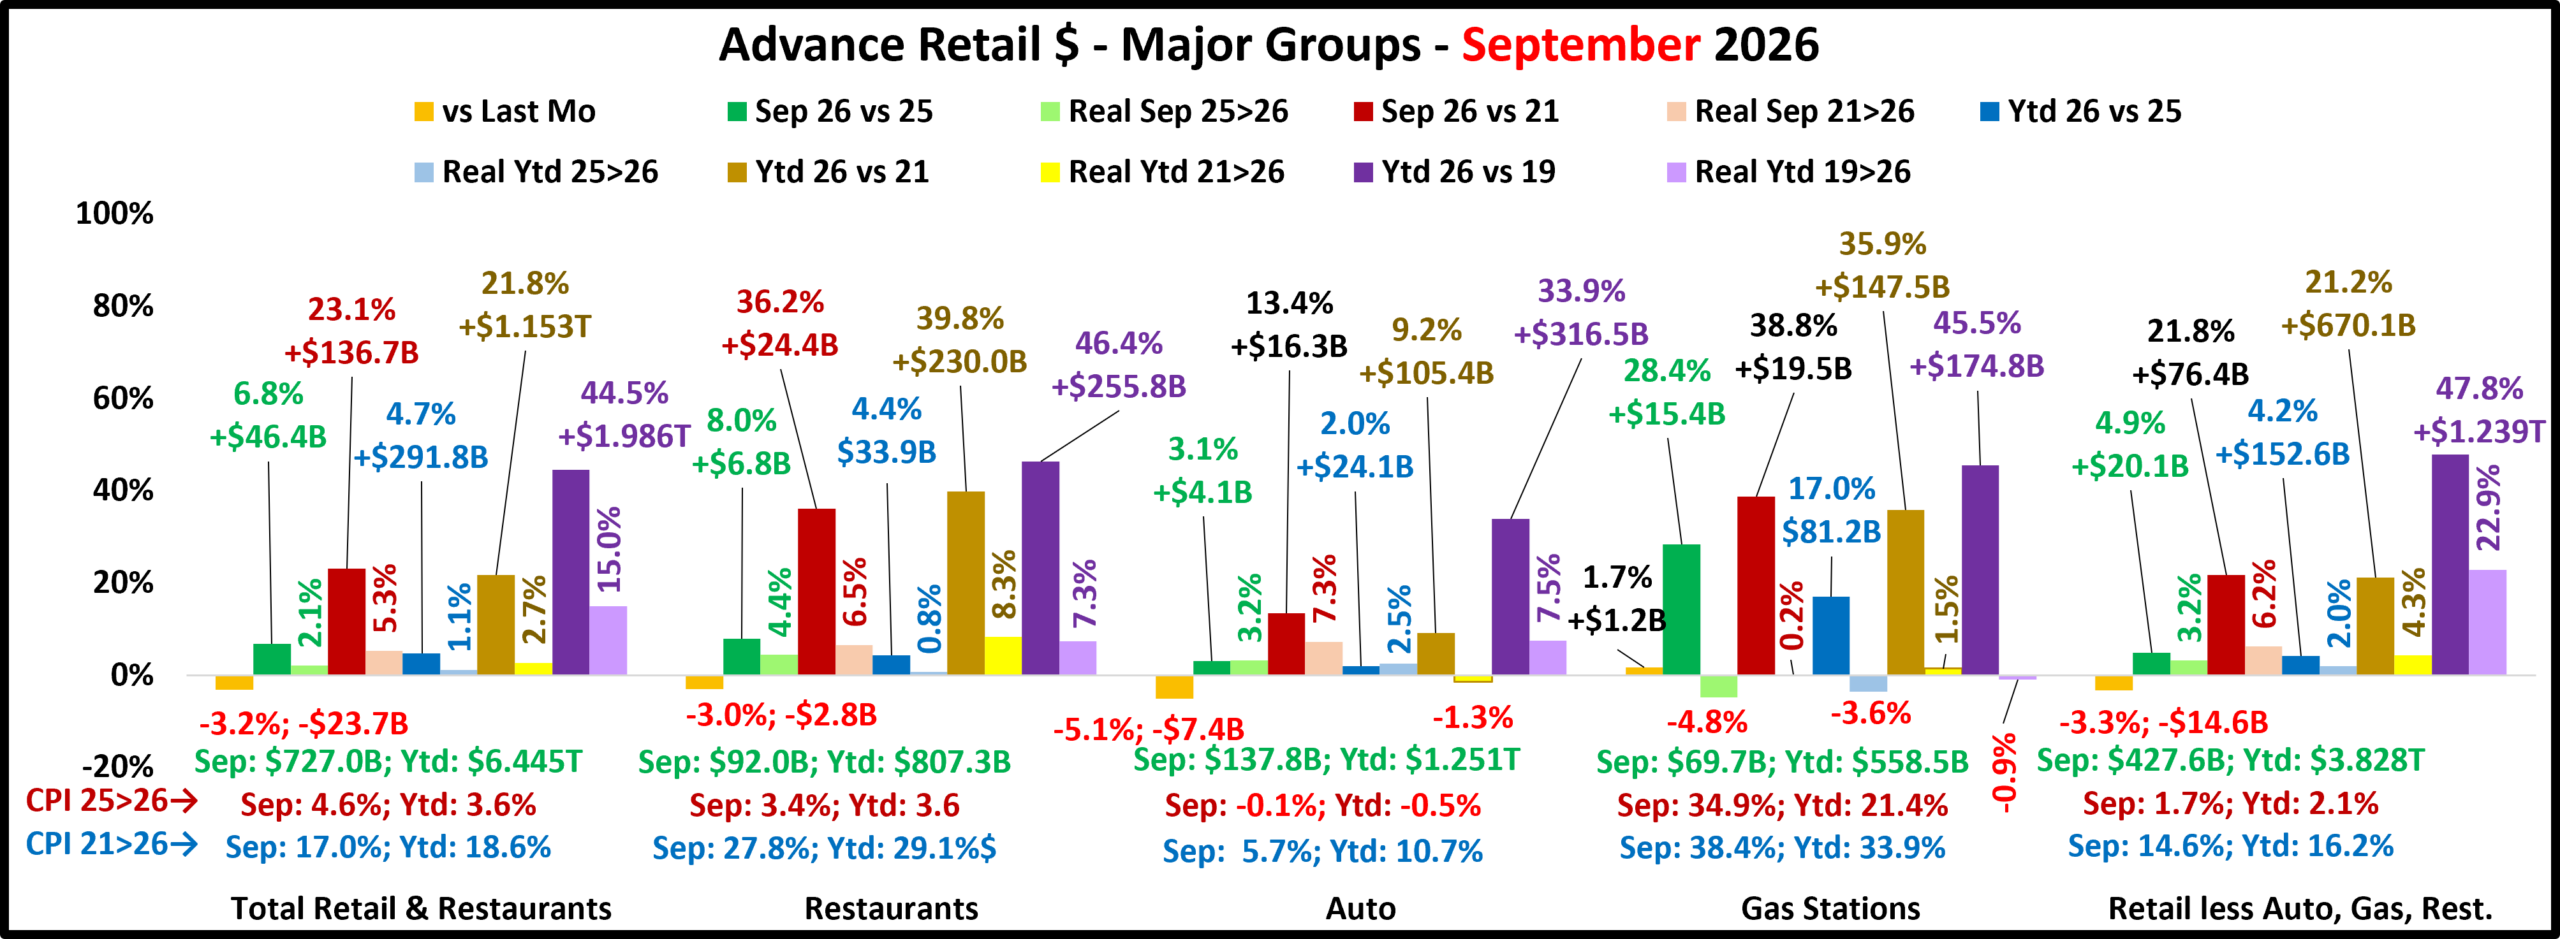
Only Gas Stations were up from Aug. Relevant Retail was -3.3%. An Aug>Sep Total Retail drop has happened in every year since 1992, but the -3.2% drop is 49% less than the -6.2% avg. There were no YOY $ drops, the same as May>Aug. All Big Groups were up vs 25 and the Total Retail lift of 6.8% vs Sep 25 was 52% above their +4.5% 92>25 avg. The Relevant Retail 4.9% increase vs Sep 25 was 10% above their +4.5% avg. The CPI for all commodities rose to 4.6% from 4.0% in Aug and it is still +17.0% vs 21. There is some “real” news. In Jan/Feb, no “real” measurement was down. In Mar there were 7, in Apr 9, in May 6, in Jun/Jul 5, in Aug/Sep 4. Gas Stations are still selling less Gas in 26 than in all yrs but 21. Like August, 3 Groups are all positive – 4 in Jun/Jul, 3 in May, 2 in Apr & 1 in Mar. Note: Relevant Retail has been all positive in 28 of the last 30 months.
Overall Inflation Reality– The Total Retail CPI rose to 4.6%, but the $ lift vs 25 was 52% above avg. The Restaurant CPI rose to +3.4% but their $ lift was 54% above avg. The Gas CPI rose from 27.9% to 34.9%. They are in turmoil, but the YOY lift is far above avg. Auto inflation is -0.1% vs 25 and only 5.7% vs 21. Sales were +3.1% vs 25. Their avg change is +4.1%. Inflation slowed to 1.7% from 1.8% for Relevant Retail and their lift was 10% above avg. They are again all positive. Progress is complex in 26.
Total Retail – Since Jun 20, every month but Apr 23, Jun 24 & Feb 25 has set a monthly $ record. In 23>26, Sales got on a roller coaster. Down Jan 24, up Feb>Mar, down Apr, up May, down Jun, up Jul>Aug, down Sep, up Oct>Dec, down Jan/Feb 25, up Mar, down Apr, up May, down Jun, up Jul/Aug, down Sep, up Oct, down Nov, up Dec, down Jan/Feb, up Mar, down Apr, up May, down Jun, up Jul/Aug, down Sep. Prices are +4.6% and YOY $ are +6.8%, 52% above avg. 34% of 19>26 growth is real. The inflation lift didn’t impact YOY $. Growth: 25>26: 4.7%; Avg 19>26: +5.4%, Real: 2.0%
Restaurants – They were hit hard by the pandemic and didn’t begin recovery until Mar 21. However, they have had strong growth since then, exceeding $1T for the 1st time in 25. September $ are +8.0% vs 25 and they have the biggest lift vs 21. (#2 vs 19). Inflation rose to 3.4% from 3.3% vs last year, but it is +27.8% vs 21 and +36.4% vs 19. Their 8.0% YOY lift is 53.8% above their +5.2% 92>25 avg. They are again all positive, but just 15.7% of their 46.4% growth since 2019 is real. They are last in Big Group performance. Recovery started late but inflation started early. Growth: 4.4%; Avg 19>26: +5.6%, Real: +1.0%. They just account for 12.5% of Total Retail $, but their strong growth has helped Total Retail.
Auto (Motor Vehicle/Parts Dealers) – They overcame the stay-at-home attitude with deals & advertising. They finished 2020 only down 1% vs 2019. They hit a record $1.51T in 2021 but much was due to high prices. In 22, sales got on a rollercoaster. Inflation started to drop mid-year and $ set a record, $1.58T. However, their YE real 22 sales were not good, -6.6% vs 21. In 23 the sales rollercoaster continued but set a record, $1.609T. $ fell Jan 24, grew Feb/Mar, fell Apr, grew May, fell June, grew Jul/Aug, fell Sep, grew Oct, fell Nov, grew Dec, fell Jan/Feb 25, grew Mar, fell Apr>Jun, rose Jul/Aug, fell Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb, fell Mar/Apr, rose May, fell Jun, rose Jul/Aug, fell Sep. September was +3.1% vs 25. Avg: 4.1%. Only 22.1% of 19>26 growth is real. Growth: 2.0%; Avg 19>26: +4.3%, Real: +1.0%
Gas Stations – They were hit hard by “stay at home”. They started recovery in Mar 21, and inflation began. Sales got on a rollercoaster in 22 but set an all-time record, $722B. Inflation started to slow in Aug 22, and prices slightly deflated in Dec & Feb 23, then strongly fell in Mar>Jul to -20.2%. In Sep they were +2.7% but began deflating to -4.2% in Feb 24. In Mar>May $ grew, fell Jun, rose July, fell Aug/Sep, rose Oct, fell Nov>Feb 25, rose Mar>May, fell Jun, rose Jul, fell Aug>Oct, up Nov, fell Dec/Jan 26, skyrocketed Feb>May, fell Jun, rose Jul>Sep. Sep $ vs 25: +28.4% (4.4% avg). No $ drops, but only real $ vs 21 are up. Growth: +17.0%; Avg 19>26: +5.5%, Real: -0.1%. Strong inflation can be “really” negative.
Relevant Retail – Less Auto, Gas and Restaurants – They account for ≈60% of Total Retail $ in a variety of channels. Their only down month until Feb 25 was Apr 20, and they led the way in Retail’s recovery. Sales got on a roller coaster in 22, but all months set new records with Dec reaching a new all-time high, $460B, and an annual record of $4.677T. In 23, the roller coaster continued. A Dec lift set a monthly record of $466.4B & an annual record of $4.761T. The roller coaster restarted in 24. $ rose Oct>Jan 25, fell Feb, rose Mar>May, fell Jun, rose Jul, fell Aug/Sep, rose Oct>Dec, fell Jan>Feb 26, rose Mar, fell Apr, rose May, fell Jun, rose Jul, fell Aug/Sep. The Sep 4.9% YOY lift is 10% above their 4.5% avg. They are all positive again & 48% of their 19>26 growth is real, #1 in Big Group performance. Growth: 4.2%; Avg 19>26: +5.7%, Real: +3.0%. In 24 their inflation rate fell from 3.2% to 0.1%. It rose in 25 to 1.8% in Sep, slowed to 1.5% Oct, rose to 2.0% Dec>Jan 26, Mar: 2.3%, Apr: 2.7%, May fell to 2.5%, Jun: 2.1%, Jul: 2.0%, Aug: 1.8%, Sep: 1.7%. Low inflation hasn’t spurred growth.
September Retail $ fell vs Aug. Total Retail was -3.2% (avg: -6.2%); Relevant Retail was -3.3%. (avg: -5.4%). Like May>Aug, no actual comparison was negative. Mar had 1. Dec>Feb & Apr, 2. There were 4 real drops in Aug/Sep, Jun/Jul 5. May 6, Apr 9; Mar 7; Dec>Feb None. In Dec, all were up vs 24 but only Relevant. Retail’s lift was above avg. In Jan, 3 lifts, all below avg. Feb, 4 lifts, all below avg. Mar/Apr, 4 lifts, 2 above avg. May 5 lifts, 2 above avg. Jun/Jul 5 lifts, 4 above avg. In Aug/Sep 5 lifts, 4 above avg. In Dec>Feb, 4 were all positive. Mar, 2. Apr, 1. May, 3, Jun/Jul 4, Aug/Sep 3. Relevant Retail has been all positive in 28 of 30 months. YOY inflation is relatively low for all but Gasoline. However, cumulative inflation can also slow sales.
Here’s a more detailed look at September by Key Channels in the Stacked Bar Graph Format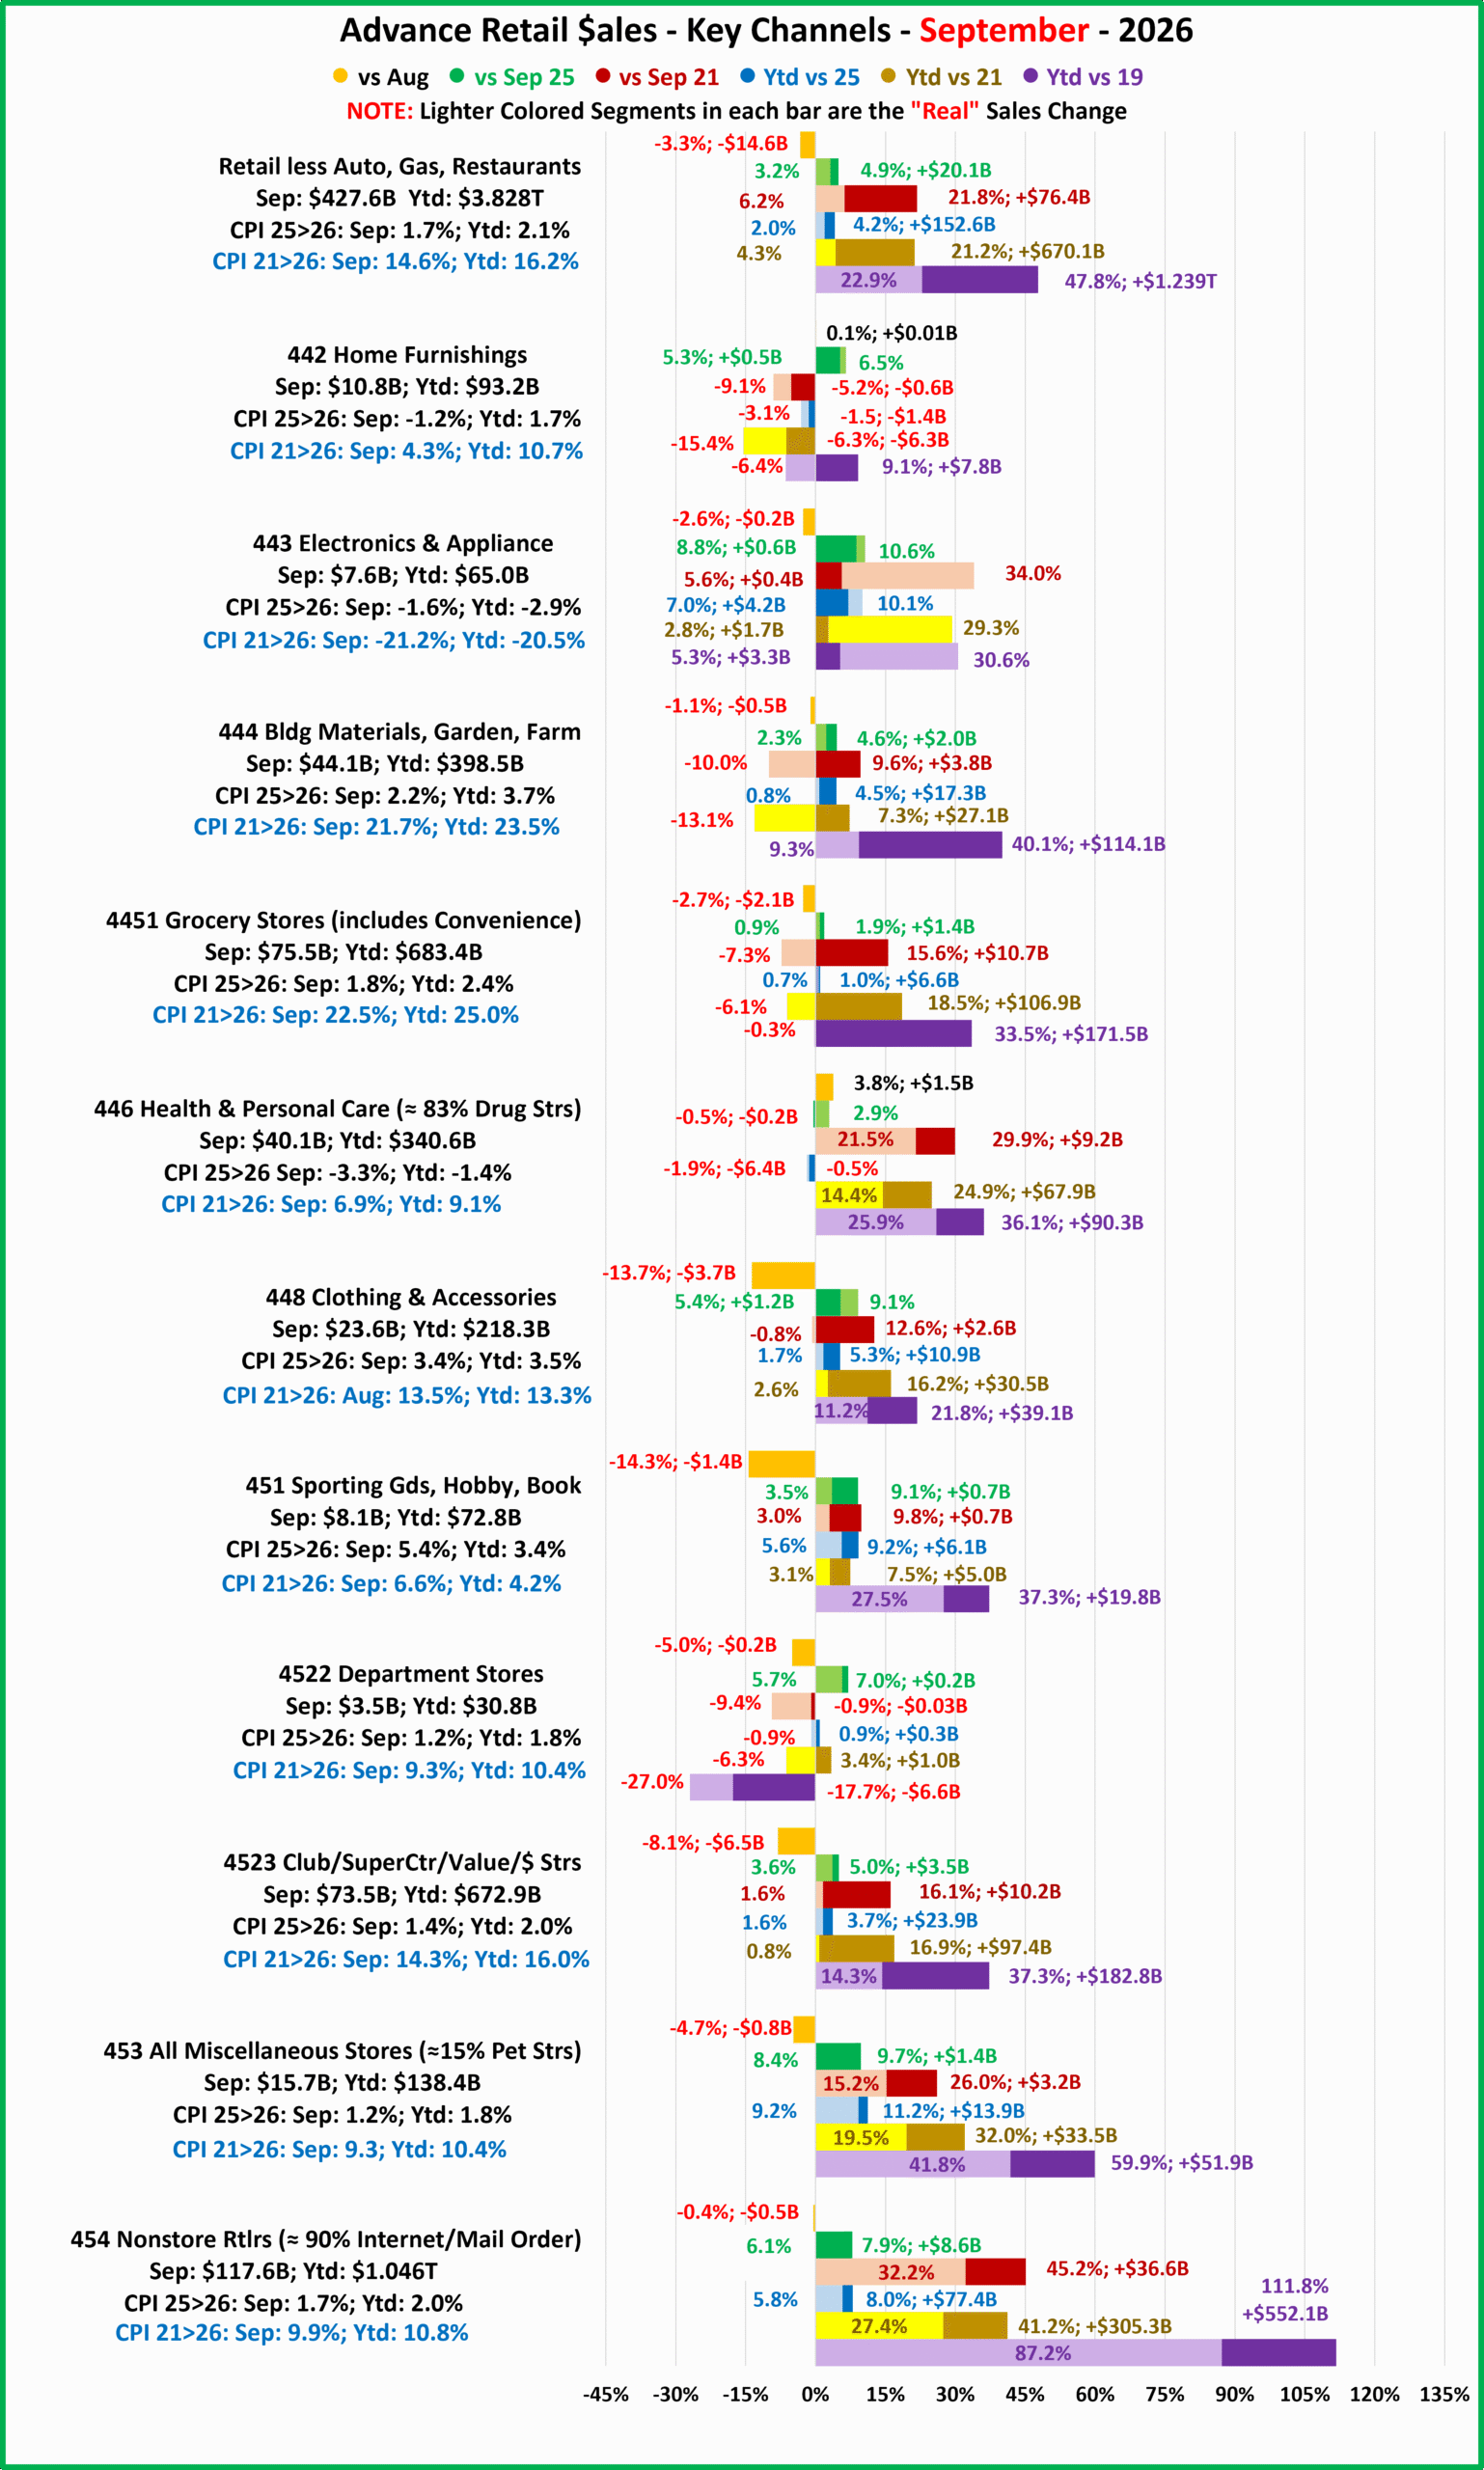
- Relevant Retail: Ytd Growth: +4.2%; Avg 19>26: +5.7%; Real: 3.0%. % Real Growth: 47.9% Only 2 of 11 were up from August. Vs Sep 25: 10 were up, 11 Real. Vs Sep 21: 9 were up; 6 Real. Vs 19: Department Stores were down & real Furniture & Grocery
- All Department Stores – This group was struggling before the pandemic hit them hard. They began recovery in March 21. Sales are -5.0% from August and all YOY comparisons but vs Sep 25 & YTD actual vs 25, 21 are negative. Their 7.0% September YOY lift is much better than their -4.2% avg. Ytd Growth: +0.9%; Avg 19>26: -2.8%; Real: -4.4%. % Real growth: None
- Club/SuprCtr/$- They fueled a big part of the recovery because they focus on value which has broad consumer appeal. $ales are -8.1% from August, but they are up in all comparisons. Their 5.0% YOY September lift is -38.1% below their 92>25 avg of +8.1%. Ytd Growth: 3.7%; Avg 19>26: +4.6%; Real: 1.9%. % Real Growth: 38.3%
- Grocery- They depend on frequent purchases, so their changes are usually less radical. $ales are -2.7% from August. They are actually up for all but really down vs 21 & 19. Cumulative inflation has hit them hard. Their 1.9% YOY September lift is -40.3% below their +3.1% avg. Ytd Growth: 1.0%; Avg 19>26: +4.2%; Real: -0.04%. % Real Growth: None
- Health/Drug Stores – Many stores are essential, but consumers visit less often than Grocery stores. $ are +3.8% from August and positive in all YOY comparisons but vs 25. Inflation has been relatively low, so it is surprising that their -0.5% YOY drop vs Sep 25 is far below avg, (5.5%). Ytd Growth: -1.9%; Avg 19>26: +4.5%; Real: 3.4%. % Real Growth: 71.7%
- Clothing and Accessories – Clothes mattered less if you stayed home. That changed in March 2021 with strong growth through 2022. Sales are -13.7% from August, but positive in all YOY measurements. $ales are +5.4% vs Sep 25, double their 2.7% avg. Ytd Growth: 5.3%; Avg 19>26: +2.9%; Real: 1.5%. % Real Growth: 51.4%.
- Home Furnishings – In mid-2020, consumers’ focus turned to their homes and furniture became a priority. Prices are deflating again. $ are +0.1% from August, but they are only actually up vs Sep 25 and vs 2019. YOY vs Sep 25, they are +5.3%, +90.6% above their 2.8% avg lift. Ytd Growth: -1.5%; Avg 19>26: +1.3%; Real: -0.9%. % Real Growth: None
- Electronic/Appliances – They have had many issues. $ fell in Apr>May of 2020 and didn’t reach 2019 levels until March 21. $ are -2.6% from August, but up in all comparisons. Strong deflation made real sales very high. Sales are +8.8% vs Sep 25, 4 times the 2.2% avg. Ytd Growth: 7.0%; Avg 19>26: 0.7%; Real: 4.6%. % Real Growth: 100+%
- Bldg Matl, Farm, Garden, Hdwe – They benefited from the consumers’ focus on home. In 22 the lift slowed as inflation grew to 10+%. Prices rose again in Apr>Sep 25, dropped Oct/Nov, rose Dec/Jan to 5.6%, fell Feb to 4.8%, rose Mar to 6.0%, fell Apr>Aug to 1.4%, rose Sep to 2.2%. $ are -1.1% from August. They are really down vs 2021. All others are up. $ vs Sep 25 were +4.6%, 13% above their 4.1% Avg. Ytd Growth: 4.5%; Avg 19>26: 4.9%; Real: 1.3%. % Real Growth: 23.2%
- Sporting Goods, Hobby and Book Stores – Consumers turned their attention to recreation and Sporting Goods stores sales took off. Book & Hobby Stores recovered more slowly. This group has been on a sales roller coaster since June 24 and $ are -14.3% from August, but all YOY comparisons are again positive. YOY Sales vs Sep 25 are +9.1%, 3.6 times their 2.5% avg. Ytd Growth: +9.2%; Avg 19>26: +4.6%; Real: 3.5 %. % Real Growth: 73.7%.
- All Miscellaneous Stores – Pet Stores have been a key part of the strong and growing recovery of this group. They finished 2020 at -2.3% but sales took off in March 21 and have continued to grow. Sales are -4.7% vs August, but positive in all comparisons. They are 2nd in the % increase vs 19 & vs 21. Plus, their 9.7% YOY Sep lift is 2.3 times their 92>25 avg of +4.2%. Ytd Growth: +11.2%; Avg 19>26: 6.9%; Real: 5.1%. % Real Growth: 69.8%.
- NonStore Retailers – 90% of their $ comes from Internet/Mail Order/TV. The pandemic accelerated online spending. They ended 2020 +29.2% and monthly $ exceeded $100B for the 1st time. The growth continued in 2021 as sales broke the $1 Trillion barrier. $ are -0.4% from August and their YOY lift vs Sep 25 of 7.9% is -17.2% below the 9.2% avg. However, they are positive in all comparisons. Ytd Growth: 8.0%; Avg 19>26: +11.3%; Real: 9.4%. % Real Growth: 78.0%.
Recap – Driven by Relevant Retail, the Pandemic recovery was widespread by Y/E 21. In 22 we were hit with the strongest inflation in 40 years. Inflation has slowed considerably from its Jun 22 peak, but only 3 smaller channels are now deflating. Deflation helps, but cumulative inflation can still have a negative impact – slowed YOY growth and even sales drops. As expected, $ rose from August for only 2 of 11 small channels. Both of the lifts were above average. The biggest concern is still YOY drops and smaller lifts. Relevant Retail’s +4.9% lift vs Sep 25 was 10% above avg. 10 channels had a YOY lift vs 25, the same as Jul/Aug. 7 of the lifts were above average, equal to August. There are many factors affecting growth, but the major one is retail pricing. February is usually the worst retail month. September is the 3rd worst & the Aug>Sep drop is the 2nd largest of 5. Both Total & Relevant Retail had record monthly sales for Dec>Sep 26. The September Relevant Retail YOY lift was above average and the biggest since 2022. 7 channels had an above average lift, tied with June & August for the most in 26. Sales dropped less than expected and YOY performance was stable and relatively good in September. We’ll see what happens in October.
Here are the Aug/Sep inflation rates for the CPIs used to calculate the impact of inflation on retail groups and channels. This includes special aggregate CPIs created with the instruction and guidance of the US BLS. I also researched data from the last Economic Census to review the share of sales by product category for the various channels to help in selecting what expenditures to include in specific aggregates. Of course, none of these specially created aggregates are 100% accurate but they are much closer than the overall CPI or available aggregates. The data includes the CPI changes vs 21 to show cumulative inflation.
Monthly YOY CPI changes of 0.2% or more are highlighted. (Green = lower; Pink = higher)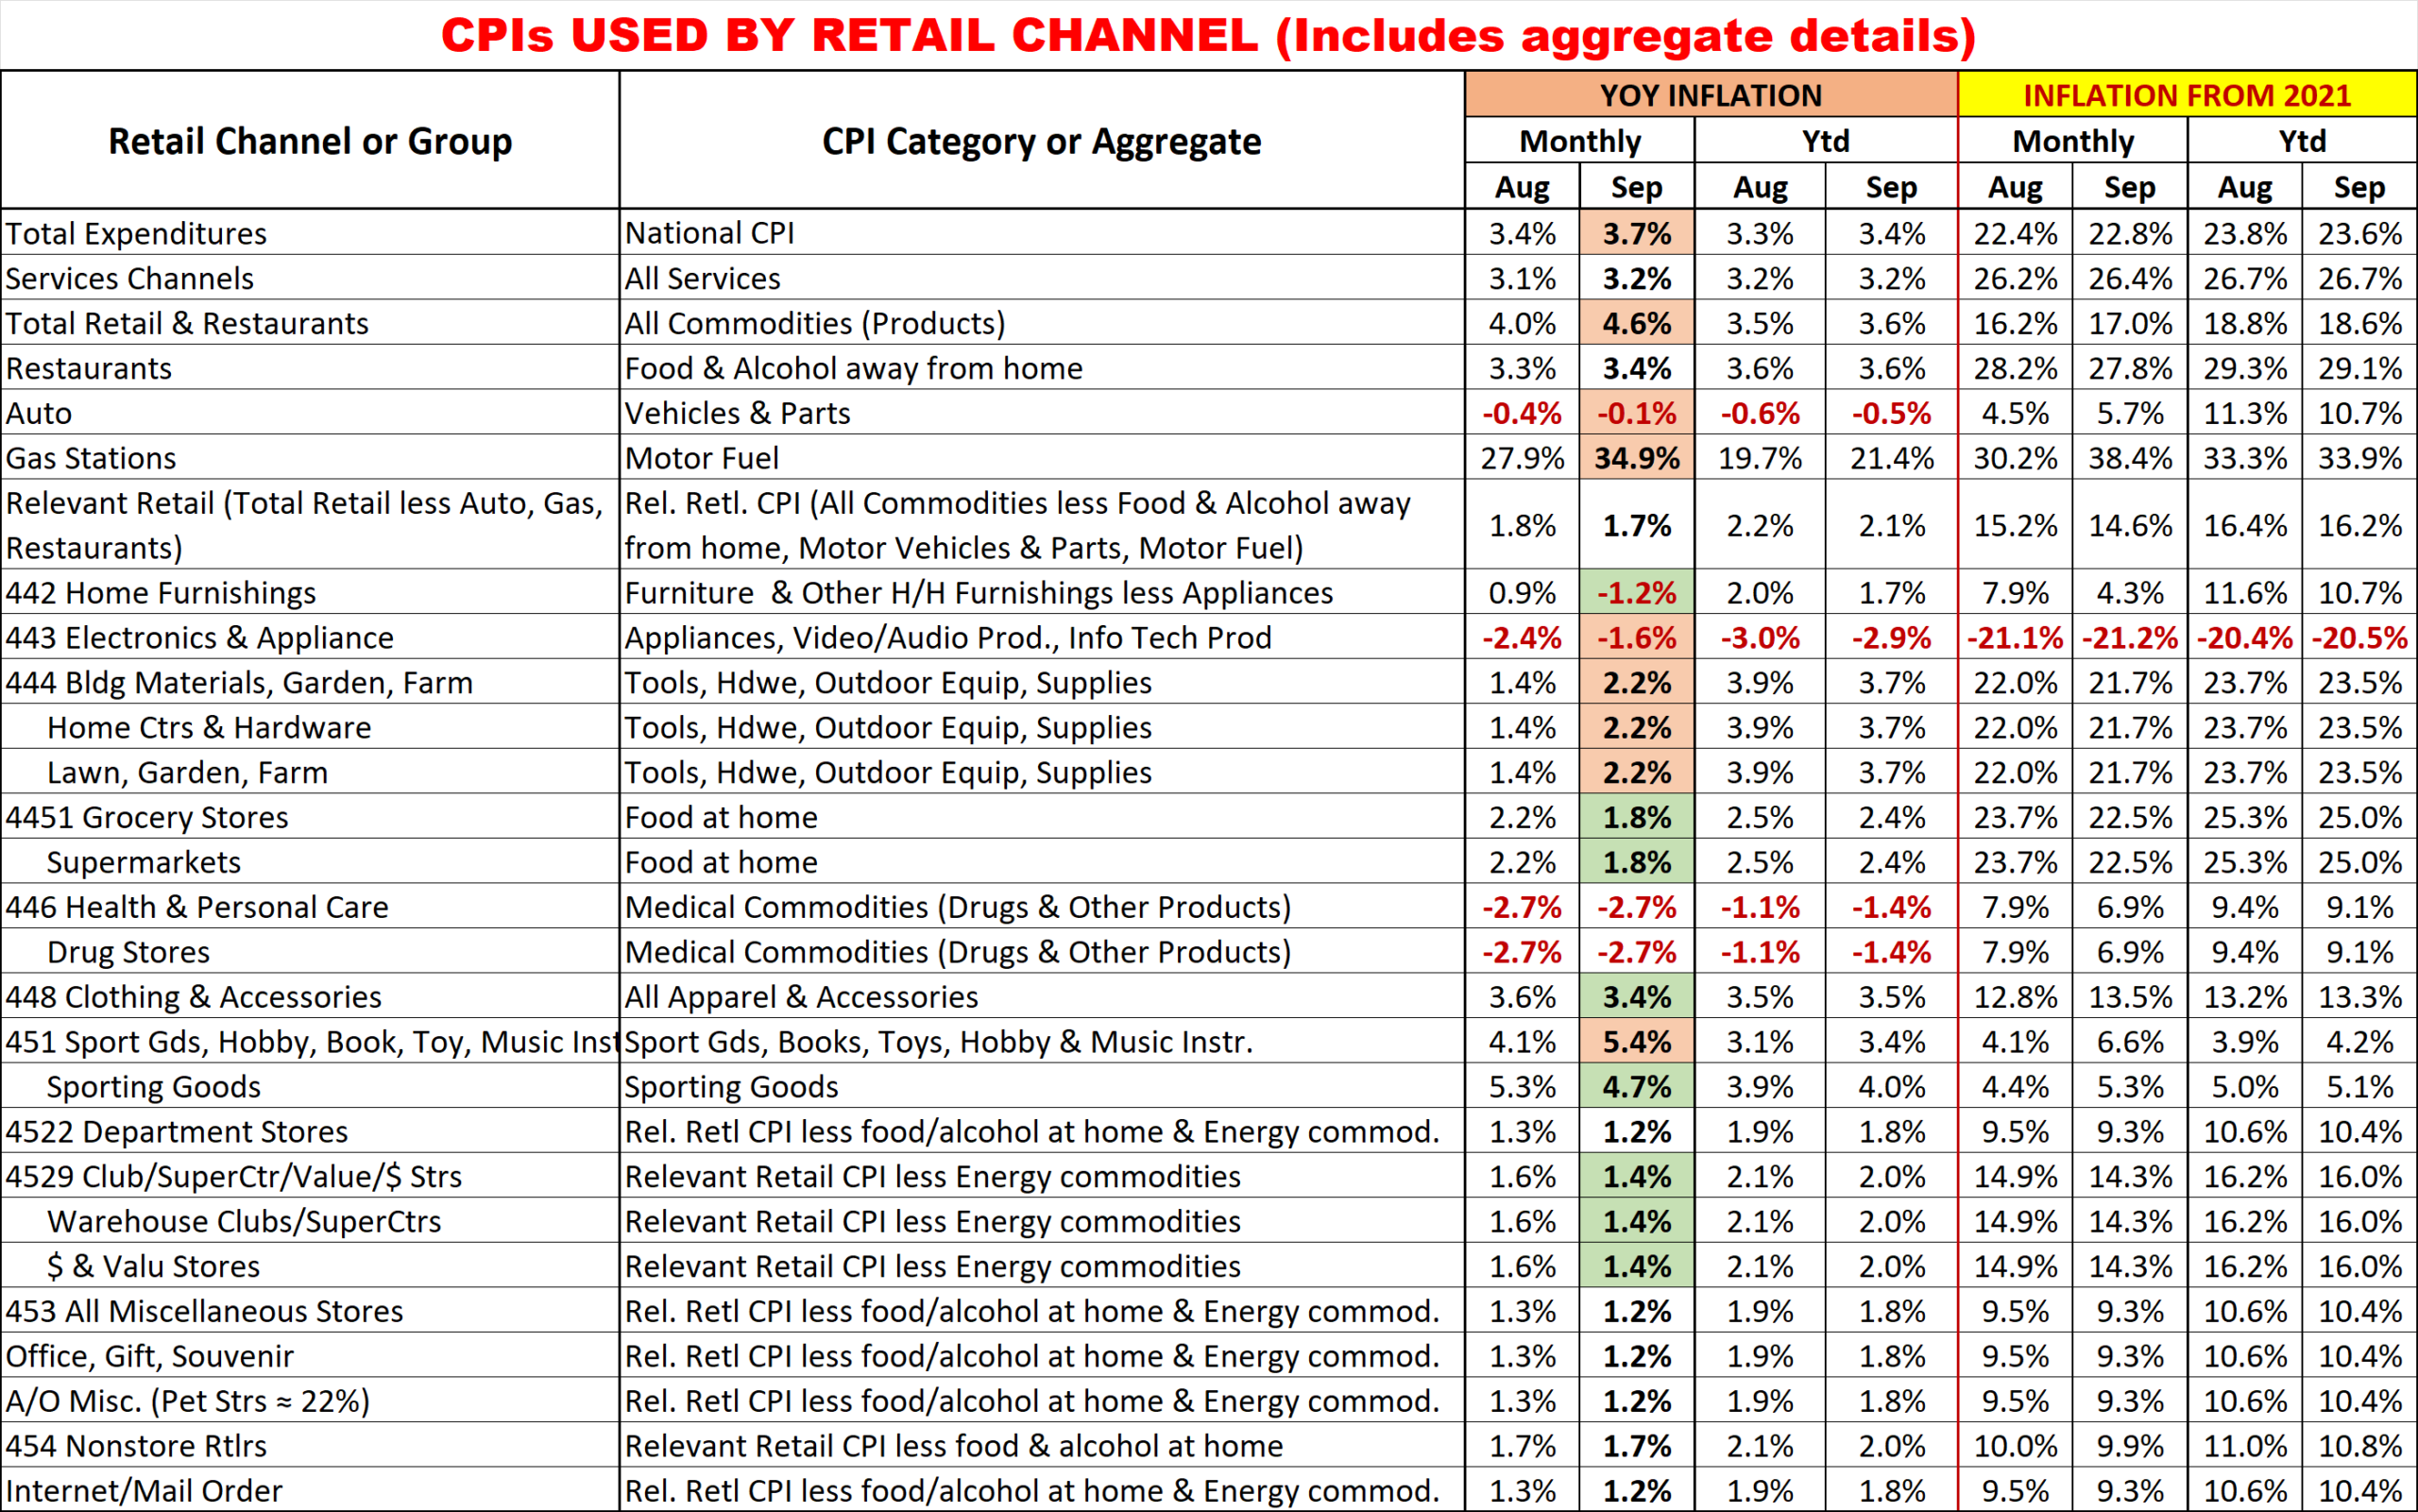 Here are some answers to some obvious questions. Note: Inflation again slowed slightly for most outlets.
- Why is the group for Nonstore different from the Internet?
- Non-store is not all internet. It also includes Fuel Oil Dealers, the non-motor fuel Energy Commodity.
- Why is there no Food at home included in Nonstore or Internet/Online
- Grocery purchasing is becoming popular, but almost all is from companies whose major business is brick ‘n mortar. These online sales are recorded under their primary channel
- 5 Channels have the same CPI aggregate but represent a variety of business types.
- They also have a wide range of product types. Rather than try to build aggregates of a multitude of small expenditure categories, it seemed better to eliminate the biggest, influential groups that they don’t sell. This method is not perfect, but it is certainly closer than any existing aggregate.
- Why are Grocery and Supermarkets only tied to the Grocery CPI?
- According to the Economic Census, 76% of their sales comes from Grocery products. Grocery Products are the driver. The balance of their sales comes from a collection of a multitude of categories
- What about Drug/Health Stores only being tied to Medical Commodities.
- An answer similar to the one for Grocery/Supermarkets. However, in this case Medical Commodities account for over 80% of these stores’ total sales.
- Why do SuperCtrs/Clubs and $ Stores have the same CPI?
- While the Big Stores sell much more fresh groceries, Groceries account for ¼ of $ Store sales. Both Channels generally offer most of the same product categories, but the actual product mix is different.