Petflation 2026; September Update – A Big YOY Drop: 3.2% to 2.2%

It’s time to continue with 2026 Inflation. The Consumer Price Index peaked back in June 2022 at 9.1% then began to slow until it turned up in Jul/Aug 2023. Prices fell Oct>Dec 23, then turned up Jan>Oct 24 but fell in Nov. However, they rose 10 straight months to a record high in Sep 25, fell Oct>Dec, rose Jan>May (Record), fell Jun/Jul, rose Aug/Sep (record). In September, the CPI vs last year rose to 3.7% from 3.4%. Grocery prices were up 0.1% from Aug, but their YOY inflation fell to 1.8% from 2.2%. BTW, Gas prices are up 45.5% from Feb. Even minor price changes can affect consumer pet spending, especially in the discretionary pet segments, so we will continue with monthly reports to track petflation as it evolves.

Petflation was +4.1% in Dec 21 while the overall CPI was +7.0%. The gap narrowed as Petflation accelerated. It was 96.7% of the national rate in June 22. National inflation has slowed considerably, but Petflation generally increased until June 23. It passed the CPI in July 22, fell below Apr>Jul 24. It passed the CPI in Aug, fell below Sep>Oct, rose above in Nov, fell below Dec>Aug 25, passed it Sep>Oct & Dec>Mar 26, equal in Apr, fell below in May>Sep. All reports include:

  • A rolling 24-month tracking of the CPI for all pet segments and the national CPI. The base number will be pre-pandemic December 2019 in this and future reports, which will facilitate comparisons.
  • Monthly comparisons of 26 vs 25 which will include Pet Segments and relevant Human spending categories. Plus
    1. CPI change from the previous month.
    2. Inflation changes for recent years (25>26, 24>25, 23>24, 22>23, 21>22, 20>21, 19>20, 18>19)
    3. Total Inflation for the current month in 2026 vs 2019 and vs 2021 to see the full inflation surge.
    4. Average annual Year Over Year inflation rate from 2019 to 2026
  • YTD comparisons
    1. YTD numbers for the monthly comparisons #2>4 above

In our first graph we will track the monthly change in prices for the 24 months from Sep 24 to Sep 26. We will use December 2019 as a base number so we can track the progress from pre-pandemic times through an eventual recovery. This chart is designed to give you a visual image of the flow of pricing. You can see the similarities and differences in segment patterns and compare them to the overall U.S. CPI. The year-end numbers & those from 12 and 24 months earlier are included. We also included and highlighted (pink) the cumulative price peak for each segment. In Sep, Pet prices were -0.4% from Aug. Food: -0.02%, Supplies: -0.8%, Services: -1.2%, Vet: +0.3%. Again, only Vet Prices were up.

In Sep 24, the CPI was +22.7% and Pet was +24.2%. The Services segments inflated after mid-20, while Product inflation stayed low until late 21. In 22, Food prices grew but others had mixed patterns until July 22, when all rose. In Aug>Oct Petflation took off. In Nov>Dec, Services & Food inflated while Vet & Supplies prices stabilized. In Jan>Apr 23, prices grew every month for all except for 1 Supplies dip. In May Products prices grew while Services slowed. In Jun/Jul this reversed. In Aug all but Services fell. In Sep/Oct this flipped. In Nov, all but Food & Vet fell. In Dec, Supp. & Vet drove a lift. In Jan>Mar 24 Pet prices grew. In April, prices in all but Vet fell. In May, all but Food grew. In June, Products drove a lift. In July, all but Services fell. In Aug, Food drove a drop. In Sep, Products fueled a drop. In Nov all were up. Prices dropped in Mar & Oct>Nov 25, rose Dec>Mar 26, fell Apr/May, rose Jun>Aug. All but Vet & the CPI fell in Sep. All segments were at/near a record Mar>Sep 26.

  • U.S. CPI – Inflation was below 2% through 2020. It turned up in January 21 and grew until flattening in Jul>Dec 22. Prices rose Jan>Sep 23, fell Oct>Dec, rose Jan>Oct 24, fell Nov, rose Dec>Sep 25, fell Nov>Dec, set records Jan>May 26, slowed Jun/Jul, rose Aug/Sep. 21.9% of the lift since 2019 happened Jan>Jun 22, 7.4% of the time.
  • Pet Food Prices were at the Dec 19 level Apr 20>Sep 21. They grew & peaked in May 23, then got on a roller coaster Jun/Jul 25↑, Aug↓, Sep↔, Oct/Nov↓, Dec>Mar 26↑, Apr/May↓, Jun/Jul↑, Aug/Sep↓. 87% of the lift was in 22/23.
  • Pet Supplies – Supplies prices were high in Dec 19 due to tariffs. They had a deflated roller coaster ride until mid-21 when they returned to Dec 19 prices & stayed there until 22. They turned up in Jan 22 (record), plateaued Feb>May, grew June, flattened July, then turned up in Aug>Oct (record). Prices stabilized Nov>Dec, grew Jan>Feb 23. fell in Mar, but the roller coaster hasn’t stopped. Jan>Feb 25↓, Mar>May↑, Jun↓, Jul↑, Aug↓, Sep↑, Oct>Nov↓, Dec↑, Jan 26↓, Feb>Mar↑(record), Apr>Jun↓, Jul↑, Aug/Sep↓. Prices are now 2.1% below the March record.
  • Pet Services– Inflation is usually 2+%. Due to closures, prices increased at a lower rate in 2020. In 2021 consumer demand increased but with fewer outlets. Inflation grew in 21 with the biggest lift in Jan>Apr. Inflation was strong in 22, but prices got on a roller coaster. They rose Jul>Apr 23, fell May. Jun>Aug↑, Sep>Dec↓, Jan>Mar 24↑, Apr↓, May↑, Jun↓, Jul>Nov↑, Dec>Mar 25↓, Apr>Aug↑, Sep↓, Oct>Jun 26↑(record), Jul>Sep↓.
  • Veterinary – Inflation has been consistent. Prices turned up in Mar 20 & grew through 21. They surged in Dec 21 putting them above the CPI. In May/Jun 22 prices fell below the CPI, but they rose again & have been above the CPI since July 22. In 23>26 prices grew Jan>May, leveled Jun/Jul, fell Aug, grew Sep>Dec, fell Jan 24, grew Feb>May, fell Jun/Jul, grew Aug 24>Sep 25, fell Oct/Nov, grew Dec>Apr 26, fell May, grew Jun, fell Jul, rose Aug/Sep.
  • Total Pet – Petflation is a sum of the segments. In Dec 21 the price surge began. In Mar>Jun 22 the segments had ups & downs. Petflation grew Jul>Nov, slowed Dec, grew Jan>May 23, fell Jun>Aug, grew Sep/Oct, fell Nov, then grew Dec>Mar 24 to a record. Prices fell in April, rose May>Jun, fell Jul>Sep, rose Oct>Nov, fell Dec, rose Jan>Feb 25, fell Mar, grew Apr>Jul, fell Aug, rose Sep, fell Oct>Nov, rose Dec>Mar 26, fell Apr>May, rose Jun>Aug (Record), fell Sep.

Next, we’ll focus on the YOY inflation rate change for September and compare it to last month, last year and to previous years. We will also show total inflation from 21>26 & 19>26. Petflation rose from 2.5% to 3.5% in Sep 25, fell to 2.6% in Nov, rose to 3.5% in Dec & 4.3% in Mar 26. In Apr it fell to 3.8%, 3.2% in May/Jun & 3.0% in Jul. It rose to 3.2% in Aug, then fell to 2.2% in Sep. The chart lets you compare the inflation of 25>26 to 24>25 & other years and see how much of the inflation since 2019 came from the recent surge. We’ve added some human categories to put the Pet data into perspective.

Overall, prices were +0.6% from Aug and rose to +3.7% from +3.4% vs Sep 25. Grocery prices rose 0.1% but YOY inflation slowed from 2.2% to 1.8%. There were 4 price drops from last month, all Pet. There were 4 in Aug, 3 in Jul, but none in Feb. In Dec & Jan there was 1. In Nov there were 6 drops. The national YOY monthly CPI rate of 3.7% is up 23% from 24>25 but it’s 55% less than 21>22. The 25>26 rate is only above 24>25 for Pet Food & the National CPI. In our 2021>2026 measurement you also can see that over 73% of the cumulative inflation since 2019 has occurred in all but 3 segments – Haircuts, Medical Services & Groceries. Service Segments have generally had higher inflation rates so there was a smaller pricing lift in the recent increase. Groceries had a limited surge. Pet Products have a very different pattern. The 21>26 inflation surge provided 93.5% of their overall inflation since 2019. This happened because Pet Products prices in 2021 were still recovering from a deflationary period. Services expenditures account for 63.5% of the National CPI, so they are very influential. Their current CPI is 3.2%, up from 3.1%. The CPI for Commodities rose from 4.0% to 4.6%. Commodities are the current inflation driver. The situation in Pet is reversed. Petflation: 2.2%, down from 3.2%. The CPI for the Service Segments is 3.1%, down from 4.8%. The Pet Products CPI is 1.3%, down from 1.9%. Services is the driver, but both contributed.

  • U.S. CPI– Prices are +0.6% from Aug. The YOY rate is 3.7%, up from 3.4%. It peaked at +9.1% back in June 2022. The targeted inflation rate is <2% so we are still 85+% higher than the target. The lift follows Aug stability, a Jun/Jul drop, Mar>May lifts, Feb stability, a Jan lift, Dec stability and drops in Oct & Nov. The current rate is 23% above 24>25 and the 21>26 rate is +22.8%, 73% of the inflation since 2019. The Inflation surge was growing in Aug 21, 5.4%
  • Pet Food– Prices are -0.02% vs Aug, but +1.5% vs Sep 25, down from 1.6%. They are still 17% below the Food at Home inflation rate of +1.8%. Remember that the YOY Pet Food CPI has deflated in 17 of the last 31 months. The 2021>2026 inflation surge has generated 96.4% of the 24.9% inflation since 2019. Inflation began for Pet Food in June 2021, +0.9%, after 12 straight deflationary months. Pet Food prices reached a new record high in July 26, then fell.
  • Food at Home – Prices are +0.1% from Aug, but the YOY CPI fell from 2.2% to 1.8%. This is radically lower than Jul>Sep 2022 when it exceeded 13%. The 33.2% Inflation for this category since 2019 is 6.4% more than the national CPI but is only in 4th place behind 3 Services expenditures. 67.8% of the inflation since 2019 occurred from 2021>26. This is 5.3% less than the 73.3% by the CPI, but we should note that Grocery prices began inflating in 2020>21 then the rate accelerated. It appears that the pandemic supply chain issues in Food which contributed to higher prices started early and foreshadowed problems in other categories and the overall CPI tsunami.
  • Pets & Supplies– Prices were -0.8% from Aug and YOY inflation fell to 1.5% from 1.9%. They still have the lowest rate vs 2019. Prices deflated for much of 20>21. As a result, the 2021>26 surge accounted for 89.5% of the total inflation since 2019. Prices set a record in Oct 22 then deflated. 3 lifts pushed them to a record high in Feb 23. Prices fell in Mar & the roller coaster continued into 25. They fell Jan/Feb 25, rose Mar>May, fell Jun, rose Jul, fell Aug, rose Sep, fell Oct>Nov, rose Dec (record), fell in Jan, rose Feb>Mar – a new record, fell Apr>Jun, rose Jul, then fell Aug/Sep.
  • Veterinary Services– Prices are +0.3% from Aug and +4.6% from 2025, down from 5.7%. They are now #1 in 25>26 inflation, passing Pet Services. They’re still #1 in inflation since 2019, +55.0% and 21, +44.5%. For Veterinary, high annual inflation is the norm. However, the rate has increased during the current surge, especially since 23. They have the highest September avg rate in 26 (+6.5%) and 80.9% of the cumulative inflation since 2019 occurred from 2021>26.
  • Medical Services – Prices turned sharply up at the start of the pandemic but then inflation slowed and fell to a low rate in 20>21. Prices rose 0.3% from Aug, but inflation vs last year was stable at +2.5%. Medical Services are not a big part of the current surge as only 68.4% of the 21.2%, 2019>26 increase happened from 21>26.
  • Pet Services – Inflation slowed in 20 but grew in 21. In 24 prices surged in Jul>Nov, then fell to 3.9% in Dec>Mar 25. Apr grew, May fell, June rose, Jul rose to 6.3%, Aug fell to 5.8% & Nov to 4.2%. In Dec>Mar 26 it rose: 7.8%, Apr fell: 6.6%, May: 7.0%, Jun>Sep fell: 6.3% to 3.6%. They are #2 vs 25, 21 & 19. 75.6% of their inflation is from 21>26.
  • Haircuts/Other Personal Services – Prices are +0.4% from Aug and YOY fell to +3.7% from +4.2%. 23 of the last 33 months have been 4.0+%. Inflation has been pretty consistent. Just 66.1 % of the 19>26 inflation happened 21>26.
  • Total Pet– Petflation fell to 2.2% from 3.2%. No segment had a rate increase. Total Petflation is 37% below the 24>25 rate and 40.5% below the U.S. CPI. Plus, it is now below the 3.1% avg Sep rate since 1997. Sep prices fell -0.4% from Aug. Only Veterinary had an increase. The Aug>Sep -0.4% decrease was very different from the 0.1% 97>25 avg change. A key factor in the current YOY CPI drop was that prices rose 0.7% in 25. Aug Pet prices hit a record high. Sep prices are only 0.4% less than in Aug. Inflation is complex and recovery is slow. Now, we’ll look at YTD data.

The 25>26 rate is higher than 24>25 for all, but Vet & Med Serv. The 22>23 inflation rate was the highest for Total Pet, Pet Food, Veterinary & Pet Services. 21>22 has the highest rate for Groceries, Pet Supplies & the Natl CPI; 20>21: Haircuts; 19>20: Medical Services. The average national inflation rate in the 7 years since 2019 is 3.8%. Only 3 of the categories are below that rate – Medical Services (2.9%), Pet Supplies (1.8%) and Pet Food (3.3%). It is no surprise that Veterinary Services has the highest average rate (6.5%), but all 4 other categories are +4.1% or higher.

  • U.S. CPI – The 25>26 rate is 3.4%, up 26% from 24>25 and 13.3% from 23>24. However, it is 59% less than 21>22 and 10.5% below the average increase from 2019>2026, but still 48% more than the average increase from 2018>21. 78% of the 30.2% inflation since 2019 occurred from 2021>26. Inflation is a problem that started recently.
  • Pet Food – Ytd prices are still inflating, 1.7%, the same as Jun>Aug, but down from 1.8% in May. That’s a big increase from -0.2% in 24>25. It is above 0.7% in 23>24 and the 1.1% 18>21 average. Pet Food has the highest 22>23 rate but is only #6 in the 21>26 rates and #7 in 19>26. Deflation in the 1st half of 2021 kept YTD prices low then they surged in 22 and especially in 23. 96% of the inflation since 2019 occurred from 2021>26.
  • Food at Home – The 25>26 inflation rate is 4.3% above 24>25, but it is down 61% from 22>23 and 79% from 21>22. It’s even 8% lower than 20>21, but 12% above the average rate from 2018>20. It is only in 5th place for the highest inflation since 2019 but still beat the U.S. CPI by 8.0%. You can see the impact of supply chain issues on the Grocery category as 77% of the inflation since 2019 occurred from 2021>26.
  • Pets & Pet Supplies – A roller coaster, prices rose Jan>Feb 24, fell Mar>Apr, rose May>Jun, fell July, rose Aug, fell Sep>Oct, rose Nov>Dec, fell Jan>Feb 25, rose Mar>May, deflated vs 24 in June, rose July: +0.7%, fell to 0.0% in Aug, rose Sep>Dec, fell Jan 26, rose Feb>Mar, fell Apr>Jun, rose Jul, fell Aug/Sep. Supplies have the lowest inflation since 2019. Their biggest YOY lifts since 2019 were in 22 & 23. The 2021 deflation created an unusual situation. Prices are up 13.4% from 2019 but 106 % of this lift happened from 21>25. Prices are up 14.2% from their 2021 “bottom”.
  • Veterinary Services – Inflation was high in 2019 and steadily grew until it took off in late 2022. The rate may have peaked in 2023, but it is still going strong in 2026, +5.4%, the 2nd  highest on the chart. However, they are still #1 in inflation since 2019 and since 2021. At +6.5%, they have the highest average inflation rate since 2019. It is 71% higher than the National Average but 2.2 times higher than the Inflation average for Medical Services. Strong Inflation is the norm in Veterinary Services.
  • Medical Services – Prices went up significantly at the beginning of the pandemic, but inflation slowed in 2021. In September 2026 it is 3.2%, 10% above the 2.9% 2019>26 average rate. We should also note that 3.2% is radically higher than the -0.1% low point in 22>23.
  • Pet Services – After falling in late 2023, prices surged in 2024, then fell in 2025 until an Apr>Aug lift followed by a Sep>Nov dip, a Dec>Jun 26 lift & a Jul>Sep drop. The 25>26 6.0% CPI is #1 on the chart, passing Veterinary. It is 13% above their 19>26 avg and 2.3 times their 2018>20 avg. Pet Services is also 2nd in both 19>26 and 21>26 inflation.
  • Haircuts & Personal Services – The services segments, essential & non-essential, were hit hardest by the pandemic. The industry responded by raising prices. 2026 inflation is 4.2%, 20.8% below its 20/21 peak, but 23.5% above the 18>20 average. Consumers are paying over 35% more than in 2019, which usually reduces the purchase frequency.
  • Total Pet – Petflation is 3.3%, up 43.5% from 24>25, but 64% less than their 22>23 peak. However, It’s also 43.5% more than their 18>21 avg, but 3.0% below the US CPI. Pet prices are only -0.4% below their record high. Except for Mar/Aug/Oct/Nov, Pet prices rose in 25. This continued in Jan>Mar 26, paused in Apr>May, rose in Jun>Aug, fell Sep. The recent drop is primarily being driven by slowed inflation in both Pet Products and Pet Services.

The Petflation recovery paused in Aug 24, came back Sep>Oct, paused in Nov, resumed in Dec>Jan 25, paused in Feb, restarted in Mar and paused Apr>Sep. It improved Oct/Nov, paused in Dec>Mar, improved Apr/May, paused Jun>Aug, restarted in Sep. We tend to focus on the monthly YOY inflation in the current year and ignore the fact that inflation is cumulative. Pet prices are 26.7% above 2021 and 31.9% higher than 2019. Those are big lifts. In fact, Mar prices for the National CPI, Total Pet and all pet segments reached new record highs. By Sep, all but Supplies had set a new record. Only Supplies prices (+12.4%) are less than 24.9% higher than 2019. Since price/value is the biggest driver in consumer spending, inflation will affect the Pet Industry. Services will be the least impacted as it is the most driven by high income CUs. Veterinary will continue to see a reduction in visit frequency. Pet Parents will just pay more. The product segments will see a more complex reaction. Supplies are more discretionary so we will likely see a reduction in purchase frequency. In Pet Food, the most needed segment, some Pet Parents may choose to downgrade their Pet Food. However, the biggest impact in both product segments will be a strong movement to online purchasing and private label. We saw proof of this at both GPE 25/26 & SZ 25/26 as a huge # of exhibitors offered OEM services. Strong, cumulative inflation has a widespread impact. We’ll continue to monitor the situation.
Retail Channel $ Update – July Monthly & August Advance

In August, YOY Commodities’ inflation rose to 4.0% from 3.9%, largely due to Gasoline. High cumulative inflation vs 21 can slow $ales growth and of course, current inflation changes can affect growth, but not always. We saw examples of all of these in August. Total Retail $ were +5.3% vs 25, 13.9% above the avg 92>25 lift. Relevant Retail’s inflation dropped from 2.0% to 1.8% and sales were +4.9%, 5.9% above their avg. The situation is definitely complex. We’ll continue to track the retail market with data from 2 reports provided by the Census Bureau and factor in targeted CPIs.

The Census Bureau Reports are the Monthly and the Advance Retail Sales Reports. Both are derived from sales data gathered from retailers across the U.S. and are published monthly at the same time. The Advance Report has a smaller sample size so it can be published quickly – normally, 2 weeks after month end. The Monthly Report includes data from all respondents, so it takes longer to compile the data – about 6 weeks. Although the sample size for the Advance report is smaller, the results over the years have proven it to be statistically accurate with the Monthly reports. The biggest difference is that the full sample in the Monthly report allows us to “drill” a little deeper into the retail channels.

We will begin with the July Monthly Report and then go to the August Advance Report. Our focus is comparing to last year but also 21 & 19. We’ll show both actual and the “real” change in sales as we factor inflation into the data.

Both reports include the following:

  • Total Retail, Restaurants, Auto, Gas Stations and Relevant Retail (removing Restaurants, Auto and Gas)
  • Individual Channel Data – This is more detailed in the Monthly reports, and we’ll focus on Pet Relevant Channels.

The data will be presented in detailed charts to facilitate visual comparison between groups/channels. The charts will show 11 separate measurements. To save space they will be displayed in a stacked bar format for the channel charts.

  • Current Month change – % & $ vs previous month
  • Current Month change – % & $ vs same month last year and vs 2021.
    • Current Month Real change vs last year and vs 2021 – % factoring in inflation
  • Current Ytd change – % & $ for this year vs last year, 2021 & 2019.
    • Current Ytd Real change % for this year vs last year and vs 2021 and 2019
  • Monthly & Ytd $ & CPIs for this year vs last year and vs 2021 which are targeted by channel will also be shown. (CPI Details are at the end of the report)

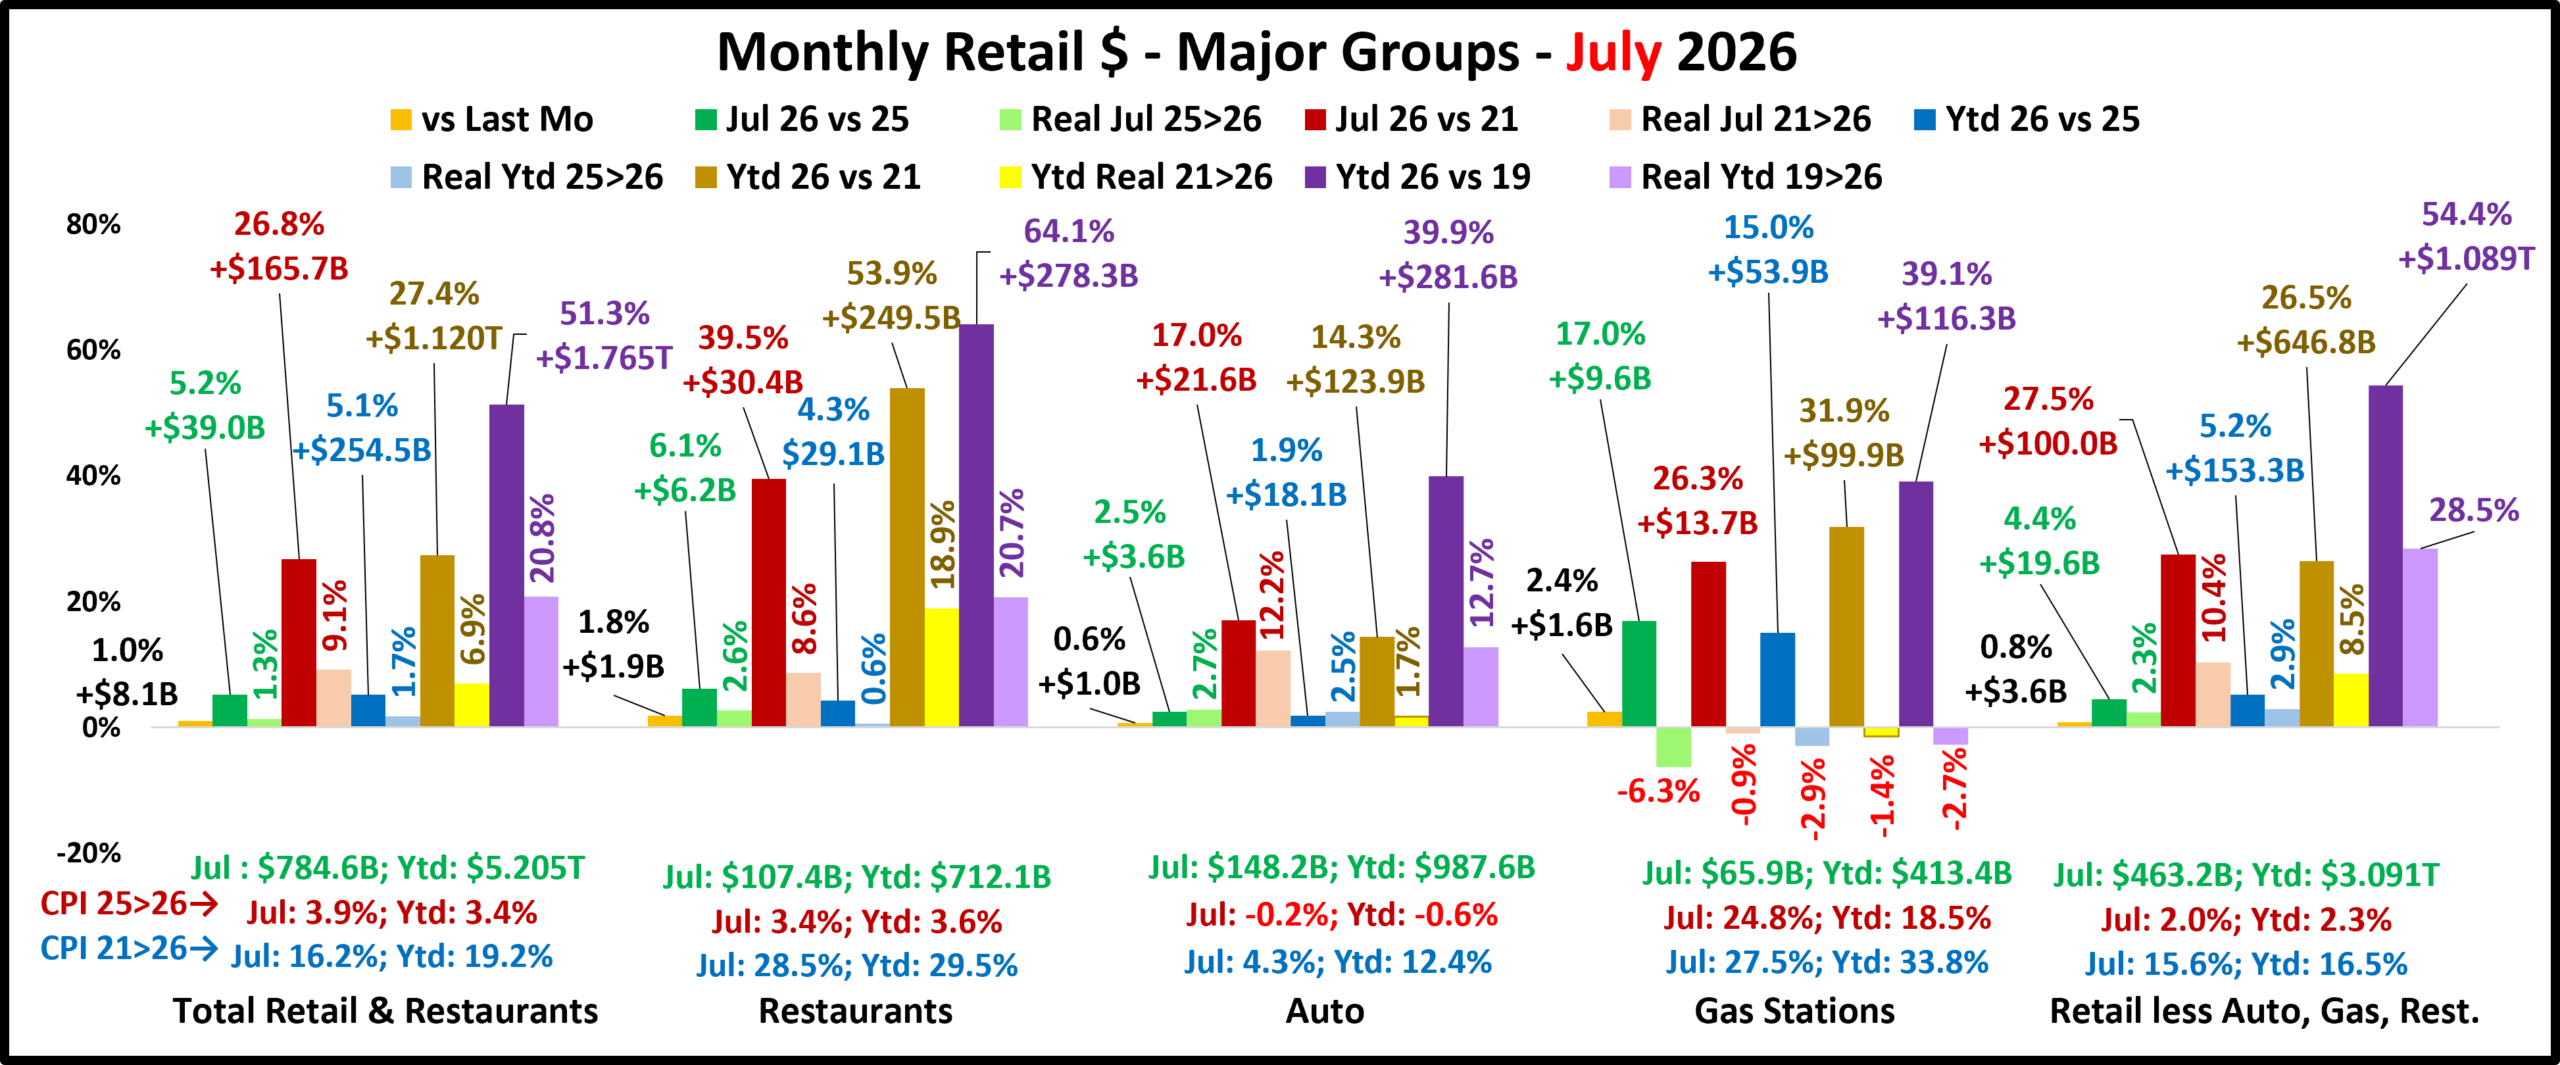
First, the July Monthly. All were up from June and there were no actual sales drops. There were 5 “real” drops and Gas Stations are again selling less product than in every comparison year, even 2019. However, Relevant Retail is all positive again. They’ve been all positive in 26 of the last 28 months. ($ are Not Seasonally Adjusted)

The July Monthly has the same total $ as the Advance, but the individual groups are different. Restaurants: +$0.2B; Auto: +$0.1B; Gas Stations: +$0.5B; Relevant Retail: -$0.8B. The lifts from June were not unexpected. A Jun>Jul increase in Total Retail  has happened in 57% of the years since 1992. However, the 1.0% lift was 2.5 times more than the 0.4% avg. There were no drops in actual sales, but again there were 5 “real” drops (all Gas Stations) – 6 in May, 9 in Apr, 7 in Mar, but none in Dec>Feb. Like June, 4 groups were all positive, up from 3 in May, 1 in Apr & 2 in Mar, but equal to Feb. Restaurants still have the biggest increases vs 21 & 19 but Relevant Retail stayed at the top of “real” performance vs 2019. However, only 52.4% of their growth is real.

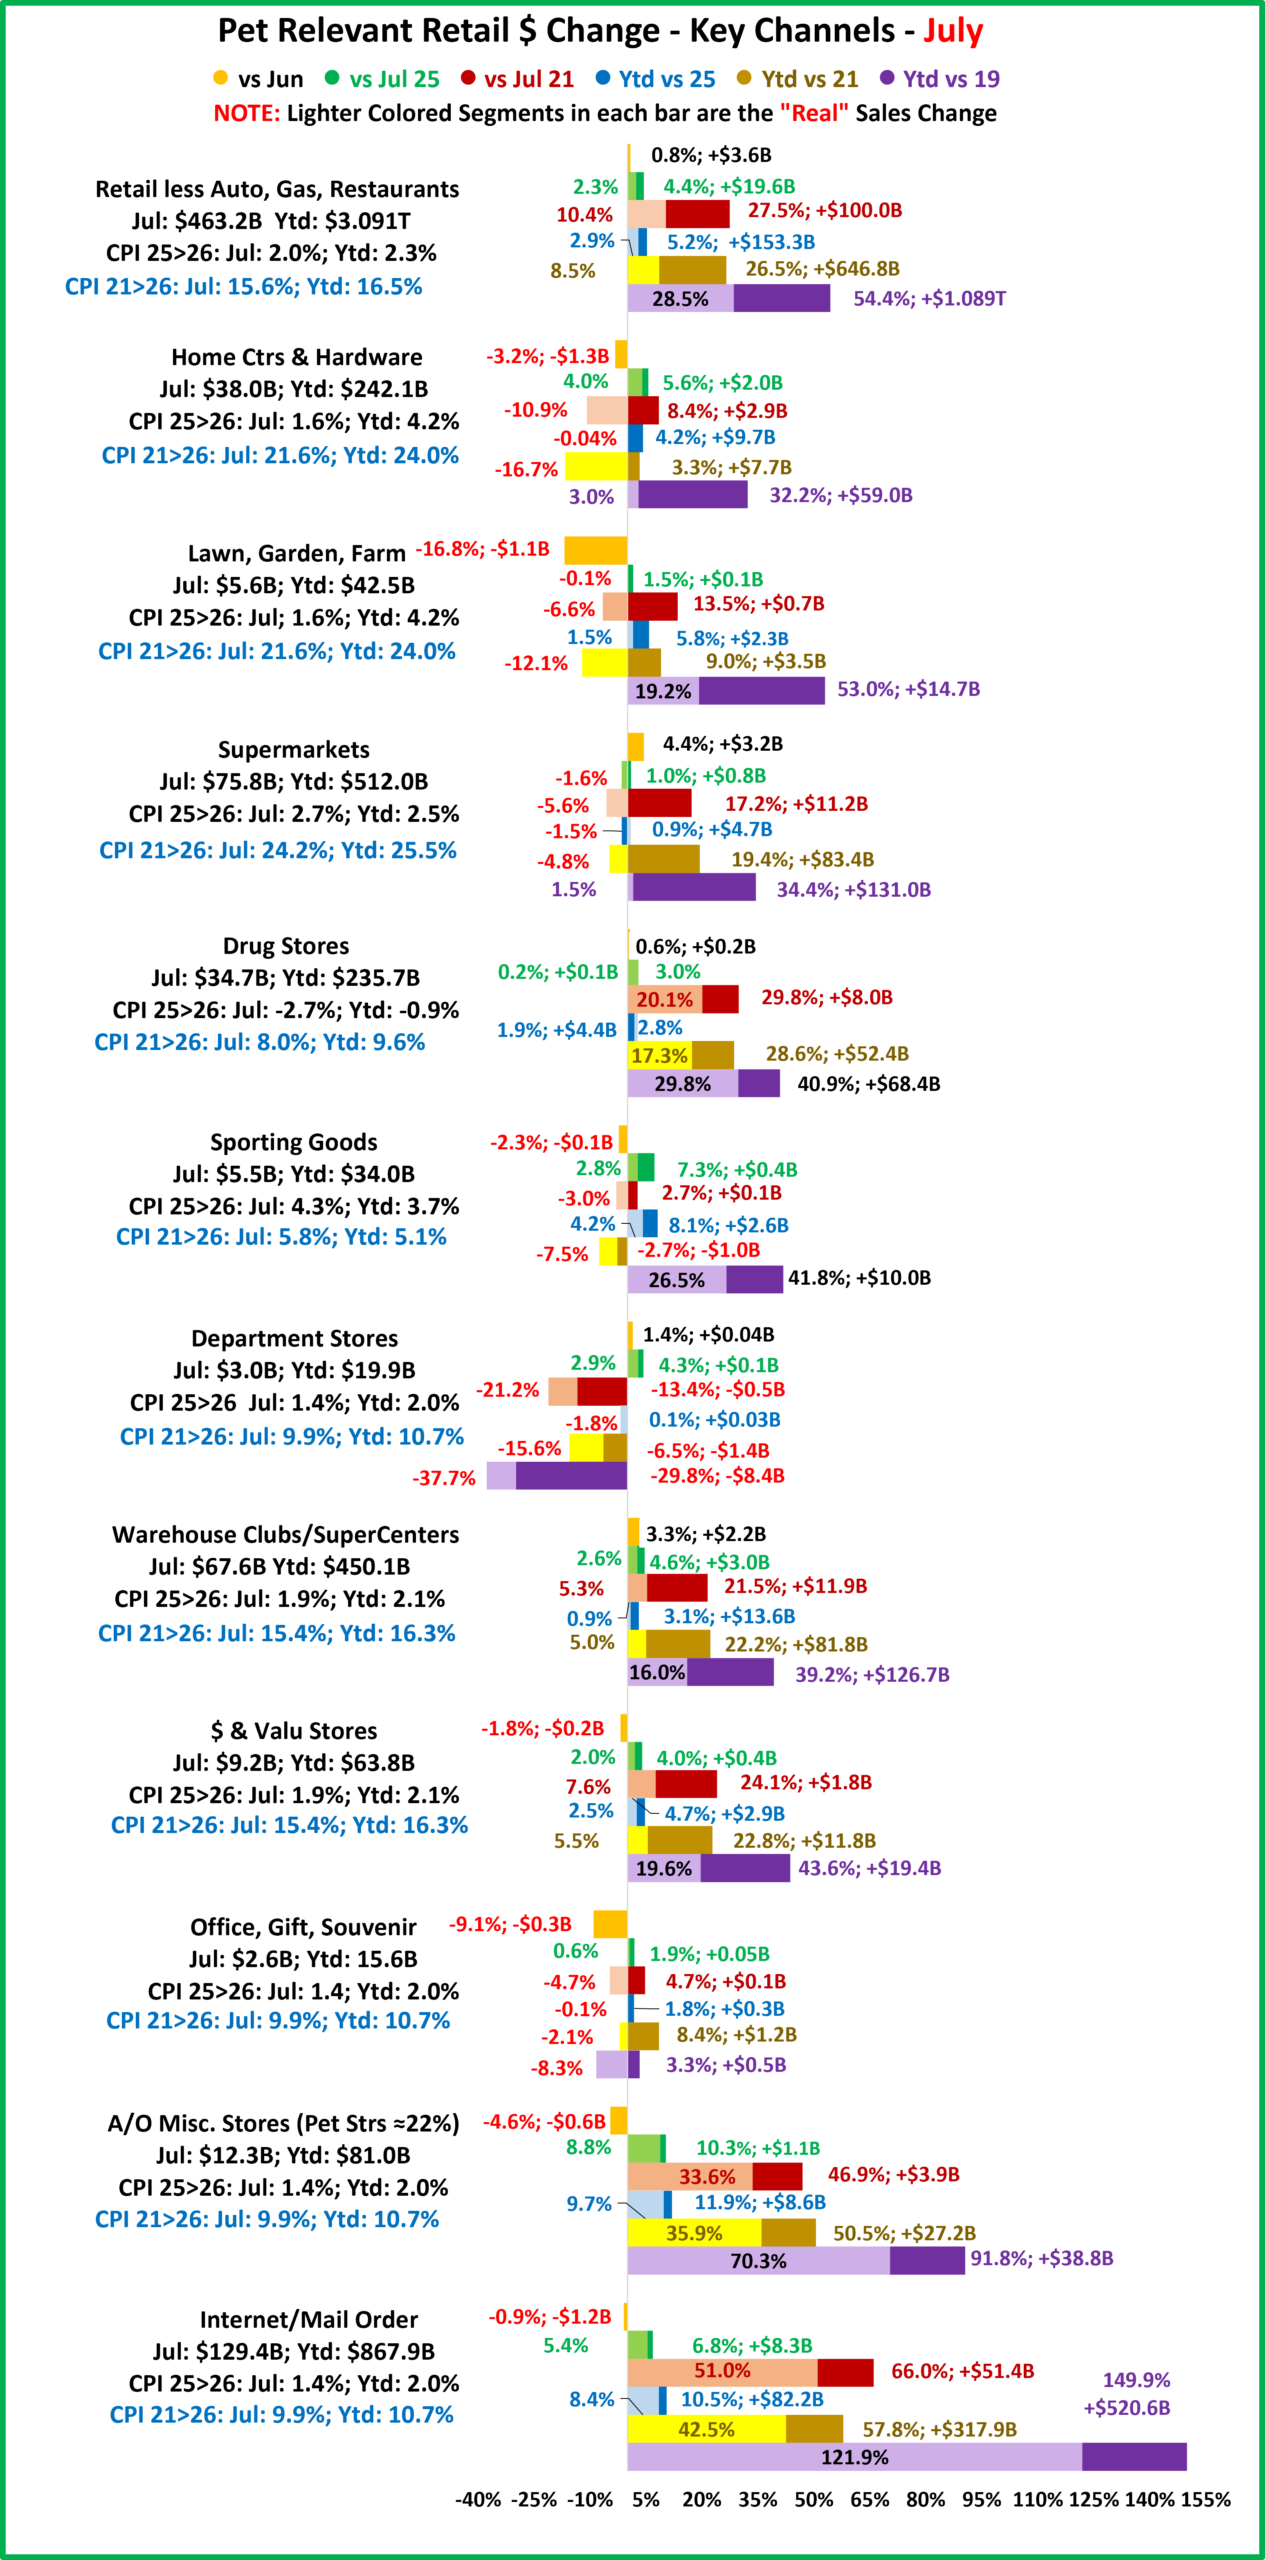
Now, let’s see how some Key Pet Relevant channels did in July in the Stacked Bar Graph Format

Overall– 4 of 11 were up from June. Vs Jul 25, 11 were actually and 9 “really” up. Vs Jul 21, 10 were up but only 5 were real lifts. Vs 2019, Only Dept Strs were actually & really down, but Off/Gift/Souv was really down.

  • Building Material Stores – The pandemic focus on home has produced $ growth of 35.6% since 2019. Prices for the group are +21.6% from 21 and +27.4% from 2019, which is impactful. As the Spring lift ends, HomeCtr/Hdwe Sales vs June were -3.2% and -16.8% for Farm. Vs other years, both are actually up for all. HomeCtr/Hdwe is only really up vs July 25 & 2019. Farm stores are really up YTD vs 25 & 19. Bldg Mat’s 19>26 real growth was 5.7% avg: 0.8%. HomeCtr/Hdwe: Ytd: 4.2%; Avg 19>26 Growth: 4.1%, Real: 0.4%; Farm: Ytd:+5.8%; Avg: 6.3%, Real: 2.5%
  • Food & Drug – Both are essential. Except for the COVID food binge, they tend to have smaller changes in $. Vs June: Supermarkets: +4.4%; Drug: +0.6%. In terms of inflation, the Groceries rate is 2.7%, while Drug/Med products are still deflating, -2.7%. Drug Stores are positive in all measurements and 72.9% of their 2019>26 growth is real. Supermarkets’ actual $ are up in all comparisons, but they are only “really” up vs 2019. Plus, only 4.4% of their 19>26 increase is real growth. Supermarkets: Ytd: +0.9%; Avg 19>26: +4.3%, Real: +0.2%; Drug Stores: Ytd: +1.9%; Avg: +5.0%, Real: +3.8%.
  • Sporting Goods Stores – They also benefited from the pandemic in that consumers turned to self-entertainment, especially sports & outdoor activities. Sales are -2.3% vs June. They are only actually & really negative ytd vs 21 and really vs July 21. Prices stopped deflating. Deflation started in April 23 and was a big change from +1.1% in 22>23 & +7.9% in 21>22. This caused 63.4% of their 41.8% lift since 2019 to be real. Ytd: +8.1%; Avg 19>26: +5.1%; Real: +3.4%
  • Gen Mdse – $ vs June: SupCtr/Club; +3.3%; $ Strs: -1.8%; Dept Strs: +1.4%. All comparisons were up for $ Strs & SupCtr/Club. Dept Stores are negative for all but vs July 25 & actual YTD vs 25. Their Actual sales are even -29.8% from 2019 (real:-37.7%). The other channels have an average of 39.7% in growth. SupCtr/Club: Ytd: +3.1%; Avg 19>26: 4.8%, Real: 2.1%; $/Value Strs: Ytd: +4.7%; Avg: +5.3%, Real: +2.6%; Dept. Strs: Ytd: +0.1%; Avg: -4.9%, Real: -6.5%.
  • Office, Gift & Souvenir Stores – Sales are -9.1% vs June. They are actually up for all but only really up vs July 25. Their recovery restarted Jun/Jul 25, but took off in Oct, slowed Nov, grew Dec, slowed Jan>Mar, grew in Apr, slowed in May, restarted in June, then slowed a little in July. Ytd:+1.8%; Avg Growth Rate: 0.5%,Real: -1.2%
  • Internet/Mail Order – Sales are -0.9% vs June but still set a July record. All YOY measurements are positive, but their YOY growth, +11.2%, is only 75.0% of their average since 2019. However, 81.3% of their 149.9% growth since 2019 is real. Ytd: +10.5%; Avg Growth: +14.0%, Real: +12.1%. As expected, they are by far the growth leader since 2019.
  • A/O Miscellaneous – Pet Stores are 22>24% of total $. In May 2020 they began recovery which reached $100B for the 1st time in 21. In 22 their $ dipped in 4 months, rose Dec, fell Jan>Feb 23, grew Mar>May, fell Jun>Aug, rose Sep>Nov, fell Dec>Jan 24, grew Feb>May, fell Jun>Sep, grew Oct, fell Nov, rose Dec, fell Jan>Feb 25, grew Mar>May, fell Jun>Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb/Mar, fell Apr, rose May/Jun, fell -4.6% in July. They’re all positive & are #2 in the increase vs 19 & vs 21. Also, 76.6% of their 91.8% growth since 2019 is real. Ytd: +11.9%; Avg 19>26: 9.8%, Real: +7.9%

July had a small lift vs June, but far above avg. Rel Retl was +0.8% (avg: -0.1%). However, only 4 small channels were up. The YOY lift vs 25 was 12% above avg for Total, but -6% below avg for Relevant Retl. All big groups & all smaller channels had lifts. Prices are only deflating in Auto & Drug, but cumulative inflation has an impact, as only 5 of 11 channels were really up vs July 21. Recovery is slow. In August, the commodities CPI rose slightly from 3.9% to 4.0%. Let’s see if it impacts Retail.

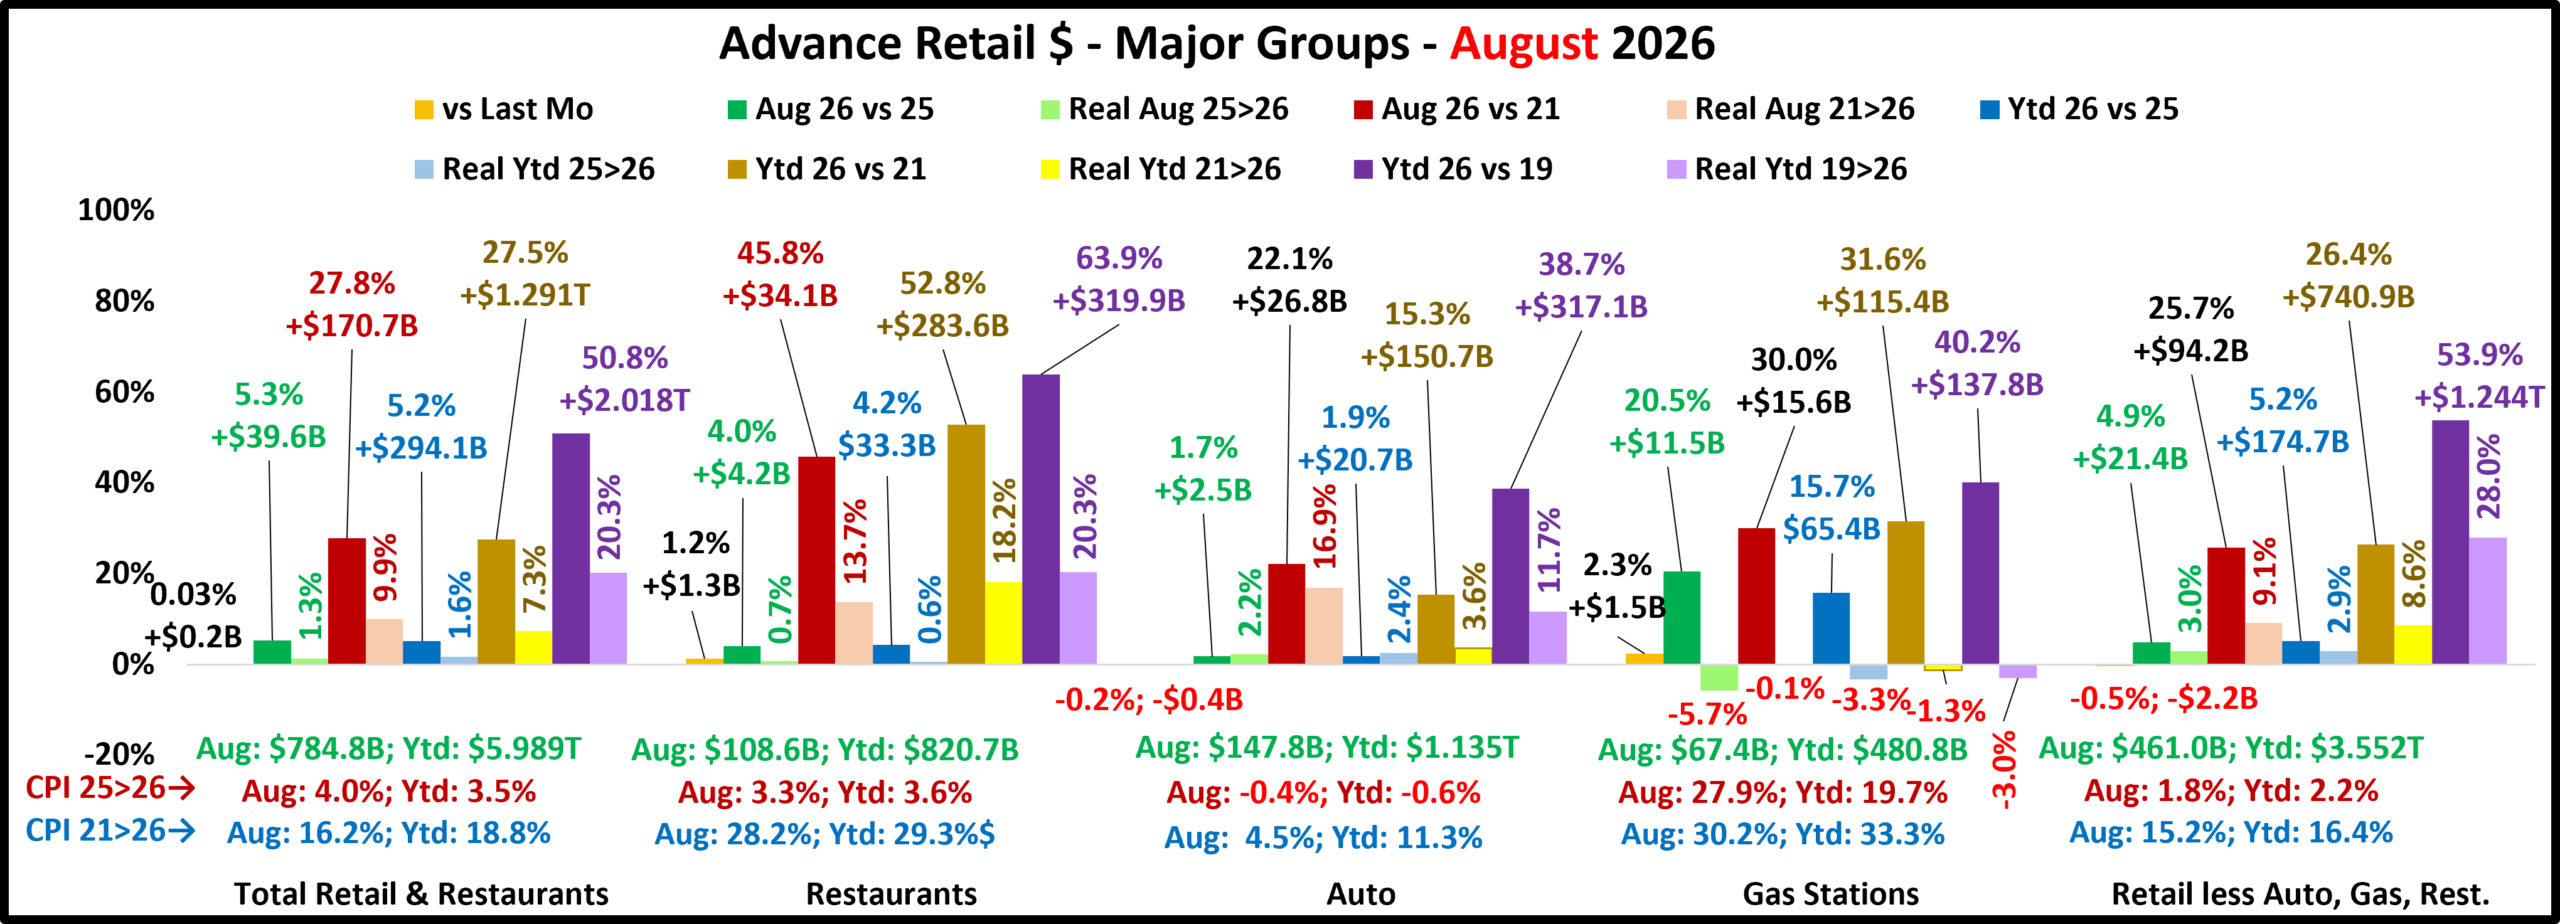
3 were up from July. Rel Retl was -0.5%. A Jul>Aug Total Retail lift has happened in 80% of the yrs since 1992, but the 0.03% lift is -99% less than the 2.1% avg. There were no YOY $ drops, the same as May>Jul. All Big Groups were up vs 25 and the Total Retail lift of 5.3% vs August 25 was 13.9% above their +4.7% 92>25 avg. The Relevant Retail 4.9% increase vs August 25 was 5.9% above their +4.6% avg. The CPI for all commodities rose to 4.0% from 3.9% in July and it is still +16.2% vs 21. There is some “real” news. In Jan/Feb, no “real” measurement was down. In Mar there were 7, in Apr 9, in May 6, in Jun>Aug 5. Gas Stations are still selling less Gas than in all comparison yrs. However, like Jun/Jul, 4 Big Groups are all positive, up from 3 in May, 2 in Apr & 1 in Mar. Note: Relevant Retail has been all positive in 27 of the last 29 months.

Overall Inflation Reality– The Total Retail CPI rose to 4.0%, but the $ lift vs 25 was 13.9% above avg. The Restaurant CPI slowed to +3.3% from +3.4%, but their $ lift was -27.5% below avg. The Gas CPI rose from 24.8% to 27.9%. They are in turmoil. Auto inflation is  -0.4% vs 25 and only 4.5% vs 21. Sales were +1.7% vs 25. Their avg change is +4.5%. Inflation slowed to 1.8% from 2.0% for Relevant Retail and their lift was 5.9% above avg. They are again all positive. Progress is complex in 26.

Total Retail – Since June 20, every month but April 23, Jun 24 & Feb 25 has set a monthly $ record. In 23>26, Sales got on a roller coaster. Up Oct>Dec, down Jan 24, up Feb>Mar, down Apr, up May, down Jun, up Jul>Aug, down Sep, up Oct>Dec, down Jan>Feb 25, up Mar, down Apr, up May, down Jun, up Jul>Aug, down Sep, up Oct, down Nov, up Dec, down Jan/Feb 26, up Mar, down Apr, up May, down Jun, up Jul/Aug. Prices are +4.0% and YOY $ are +5.3%, 13.9% above avg. 41% of 19>26 growth is real. The small inflation lift didn’t impact YOY $. Growth: 25>26: 5.2%; Avg 19>26: +6.0%, Real: +2.7%

Restaurants – They were hit hard by the pandemic and didn’t begin recovery until Mar 21. However, they have had strong growth since then, exceeding $1T for the 1st time in 23. August $ are +1.2% from July and +4.0% vs 25, but  they have the biggest lifts vs 21 & 19. Inflation slowed to 3.3% from 3.4% vs last year, but it is +28.2% vs 21 and +36.2% vs 19. Their 4.0% YOY lift is -27.5% below their +5.6% 92>25 avg. They are again all positive, but just 31.8% of their 63.9% growth since 2019 is real. They are 3rd in performance. Recovery started late but inflation started early. Growth: 4.2%; Avg 19>26: +7.3%, Real: +2.7%. They just account for 13.7% of Total Retail $, but their strong growth has helped Total Retail.

Auto (Motor Vehicle/Parts Dealers) – They overcame the stay-at-home attitude with deals & advertising. They finished 2020 up 1% vs 2019 and hit a record $1.48T in 2021 but much was due to high prices. In 22, sales got on a rollercoaster. Inflation started to drop mid-year, but it caused 4 down months in $. Their YE real 22 sales were even worse, -8.2% vs 21 and -8.9% vs 19. 23 began a sales rollercoaster but set a record, $1.595T. $ fell Jan 24, grew Feb/Mar, fell Apr, grew May, fell June, grew Jul/Aug, fell Sep, grew Oct, fell Nov, grew Dec, fell Jan/Feb 25, grew Mar, fell Apr>Jun, rose Jul/Aug, fell Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb, fell Mar/Apr, rose May, fell Jun, rose Jul, fell -0.2% in Aug. August was +1.7% vs 25. Avg: 4.5%. They’re all positive, but just 30.2% of 19>26 growth is real. Growth:  1.9%; Avg 19>26: +4.8%, Real: +1.6%

Gas Stations – Gas Stations were hit hard by “stay at home”. They started recovery in March 21, and inflation began. Sales got on a rollercoaster in 22 but set a record, $583B. Inflation started to slow in August 22, and prices slightly deflated in Dec & Feb 23, then strongly fell in Mar>Jul to -20.2%. In Sep they were +2.7% but began deflating to -4.2% in Feb 24. In Mar>May $ grew, fell Jun, rose July, fell Aug/Sep, rose Oct, fell Nov>Feb 25, rose Mar>May, fell Jun, rose Jul, fell Aug>Oct, up Nov, fell Dec/Jan, skyrocketed Feb>May, fell Jun, rose Jul/Aug. August $ vs 25: +20.5% (4.4% avg). No $ drops, but all real $ are down. Growth: +15.7%; Avg 19>26: +4.9%, Real: -0.4%. Strong inflation can be “really” negative.

Relevant Retail – Less Auto, Gas and Restaurants– They account for ≈60% of Total Retail $ in a variety of channels. Their only down month until Feb 25 was Apr 20, and they led the way in Retail’s recovery. Sales got on a roller coaster in 22, but all months set new records with Dec reaching a new all-time high, $481B, and an annual record of $4.81T. In 23, the roller coaster continued. A Dec lift set a monthly record of $494.7B & an annual record of $4.997T. The roller coaster restarted in 24. $ rose Oct>Jan 25, fell Feb, rose Mar>May, fell Jun, rose Jul, fell Aug/Sep, rose Oct>Dec, fell Jan>Feb 26, rose Mar, fell Apr, rose May, fell Jun, rose Jul, fell Aug. The Aug 4.9% YOY lift is 5.9% above their 4.6% avg. They are all positive again & 52% of their 19>26 growth is real, #1 in performance. Growth: 5.2%; Avg 19>26: +6.3%, Real: +3.6%. In 24 their inflation rate fell from 3.2% to 0.1%. It rose in 25 to 1.8% in Sep, slowed to 1.5% Oct>Nov, rose to 2.0% Dec>Jan 26, Mar: 2.3%, Apr: 2.7%, fell to 2.5% in May, Jun: 2.1%, Jul: 2.0%, Aug 1.8%. Low inflation hasn’t spurred growth

August Retail $ rose vs July. Total Retl was +0.03%, 99% below avg; Relevant Retl was -0.5%. (avg: 2.8%). Like  May>Jul, no actual comparison was negative. Mar had 1. Dec>Feb & Apr, 2. There were 5 real drops in Jun>Aug. May 6, Apr 9; Mar 7; Dec>Feb None. In Dec 25, all were up vs 24 but only Rel. Retl’s lift was above avg. In Jan 26, 3 lifts, all below avg. In Feb, 4 lifts, all below avg. In Mar/Apr, 4 lifts, 2 above avg. In May 5 lifts, 2 above avg. In Jun 5 lifts, 4 above avg. In Jul/Aug 5 lifts, 3 above avg. In Dec>Feb, 4 were all positive. Mar, 2. Apr, 1. May, 3, Jun>Aug, 4. Relevant Retail has now been all positive in 27 of 29 months. YOY inflation is relatively low for all but Gasoline. However, cumulative inflation can also slow sales.

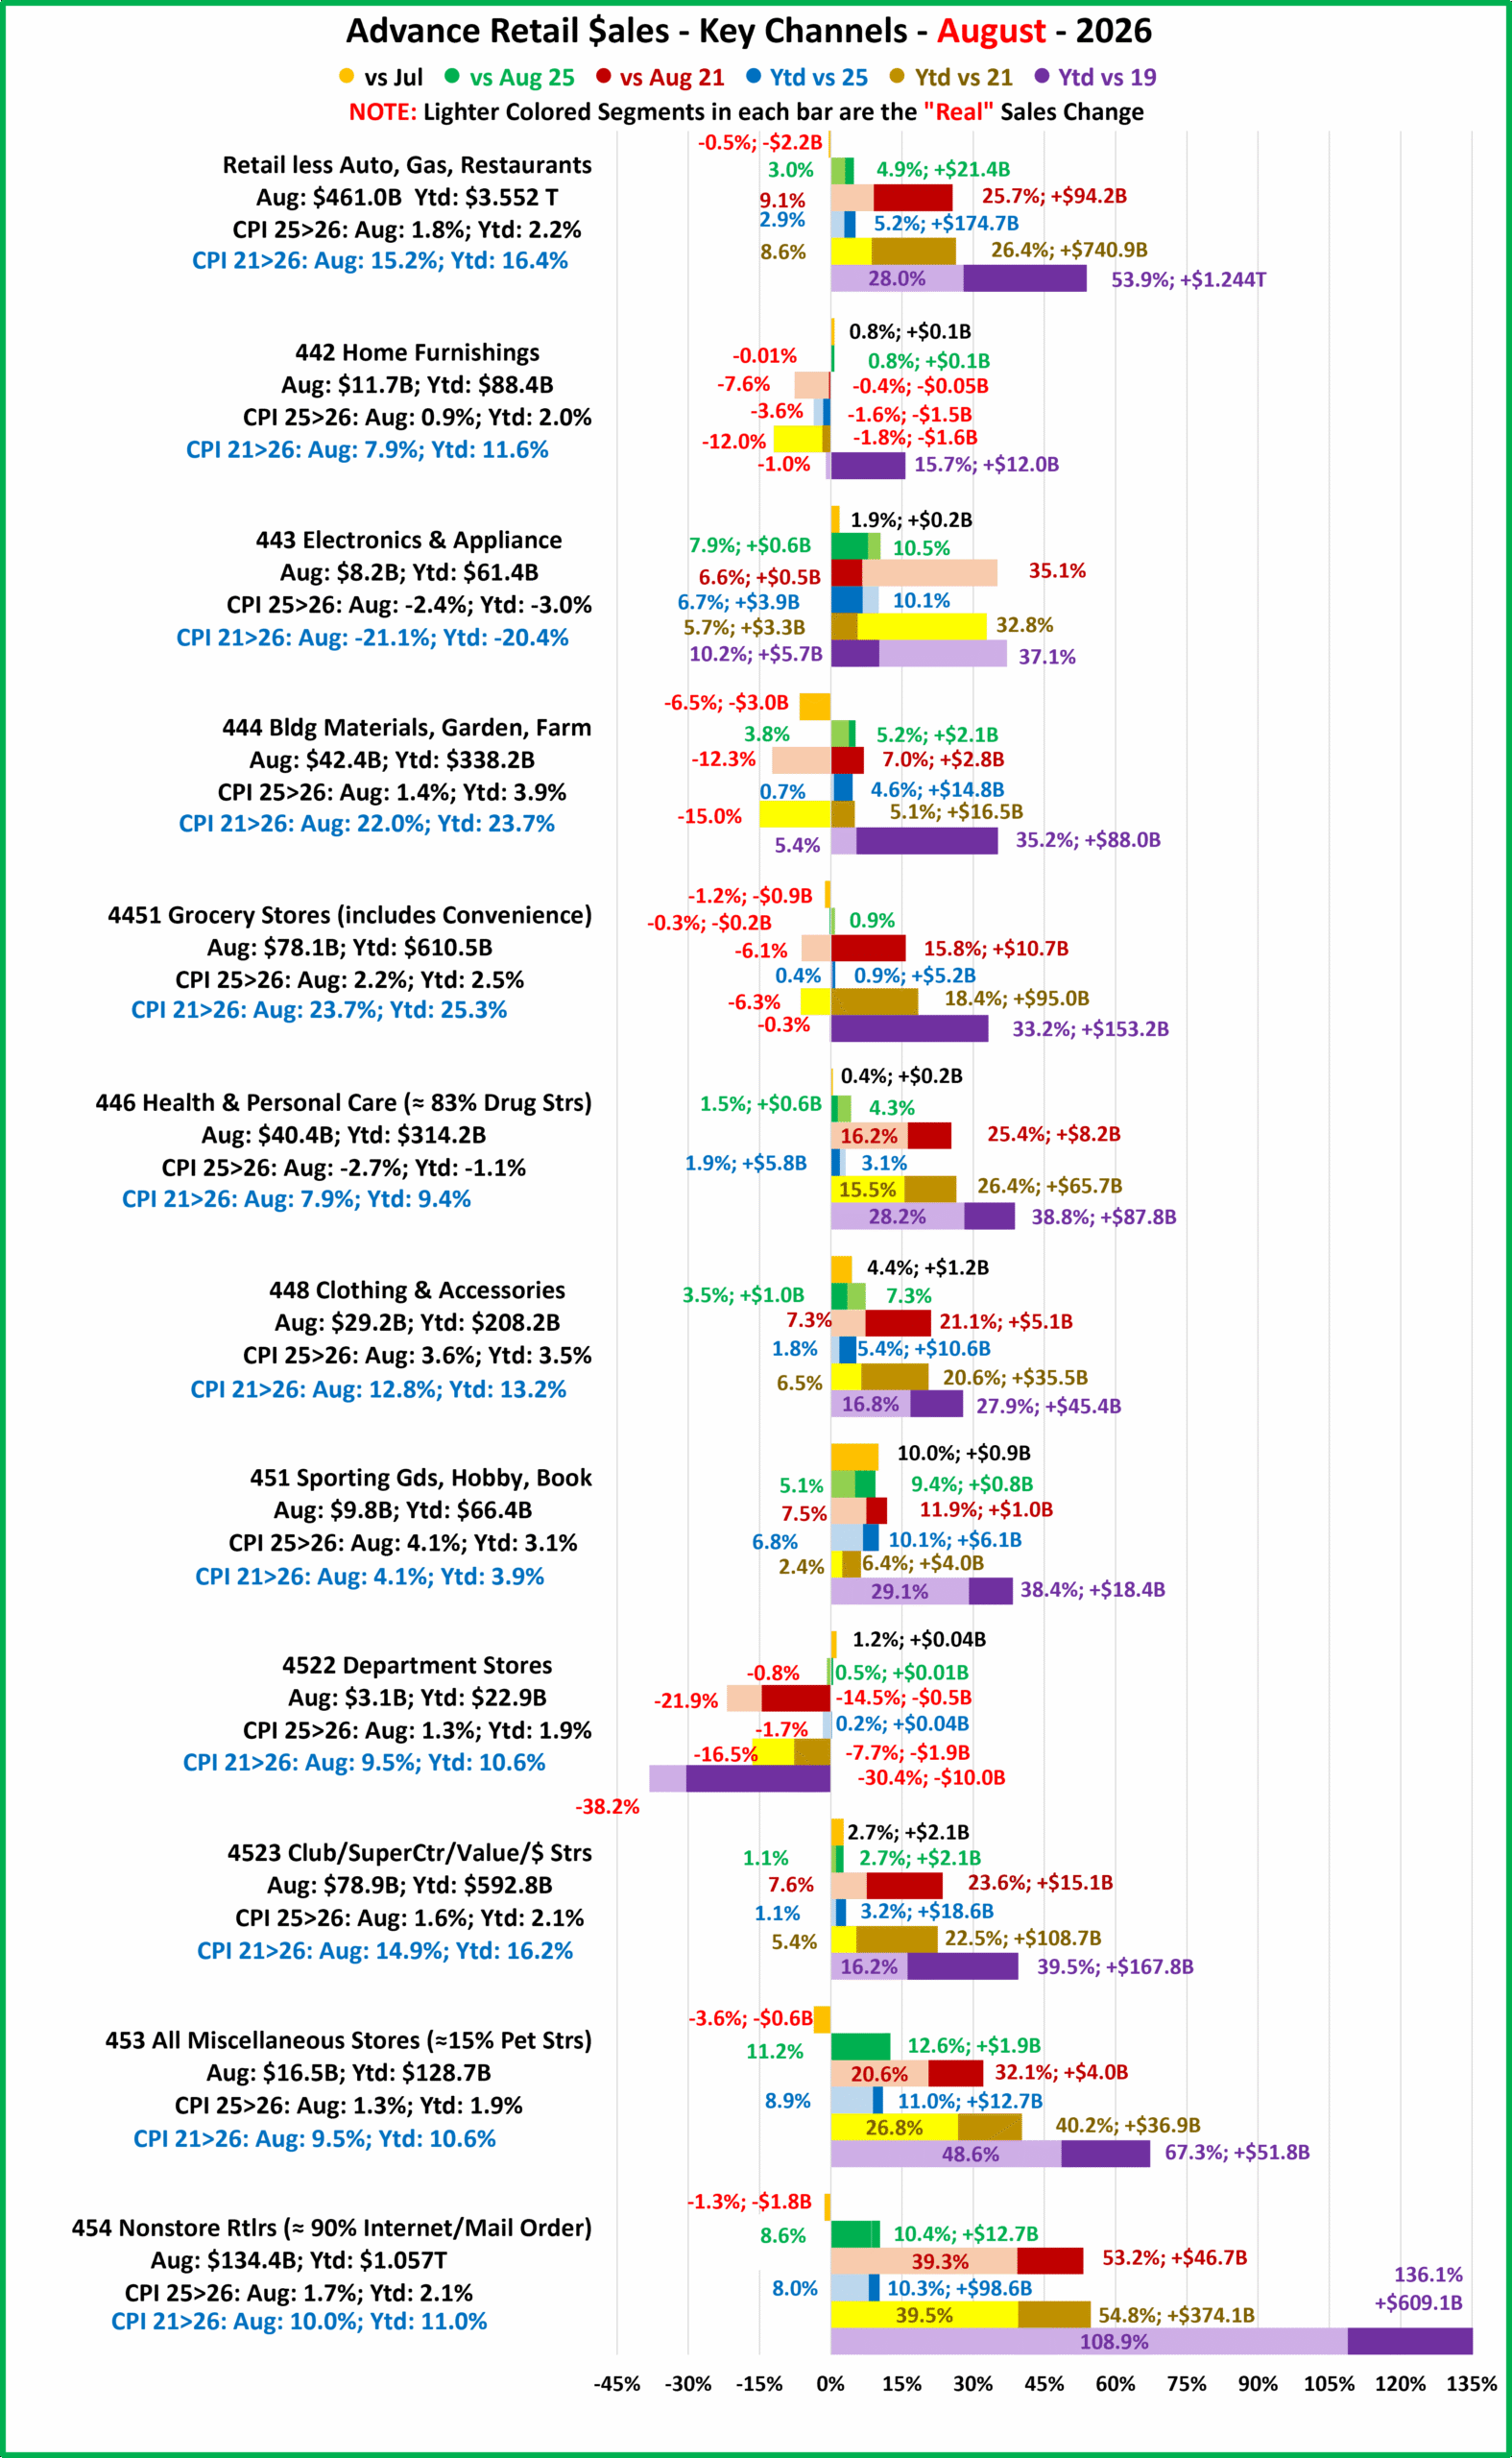
                                                 Here’s a more detailed look at August by Key Channels in the Stacked Bar Graph Format Relevant Retail: Ytd Growth: +5.2%; Avg 19>26: +6.3%; Real: 3.6%. % Real Growth: 51.9%. 7 of 11 were up from July. Vs Aug 25: 10 were up, 9 Real. Vs Aug 21: 9 were up; 7 Real. Vs 19: Dept Stores were down & “real” Furniture & Grocery

  • All Department Stores – This group was struggling before the pandemic hit them hard. They began recovery in March 21. Sales are +1.2% from July, but all YOY measurements except actual August & YTD vs 25 are negative. Their 0.5% August YOY lift is much better than their -4.7% avg. Ytd Growth: +0.2%; Avg 19>26: -5.1%; Real: -6.7%. % Real growth: None
  • Club/SuprCtr/$- They fueled a big part of the recovery because they focus on value which has broad consumer appeal. $ales are +2.7% from July, and they are up in all comparisons. Their 2.7% YOY August lift is -66.7% below their 92>25 avg of +8.2%. Ytd Growth: 3.2%; Avg 19>26: +4.9%; Real: 2.2%. % Real Growth: 41.0%
  • Grocery- They depend on frequent purchases, so their changes are usually less radical. $ales are -1.2% from July. They are actually up for all but really down for all but YTD vs 2025. Cumulative inflation has hit them hard. Their -0.3% YOY August drop is far below their +3.1% avg. Ytd Growth: 0.9%; Avg 19>26: +4.2%; Real: -0.04%. % Real Growth: None
  • Health/Drug Stores – Many stores are essential, but consumers visit less frequently than Grocery stores. $ are +0.4% from July and positive in all YOY comparisons. Inflation has been relatively low, so it is surprising that their +1.5% YOY lift vs August 25 is 71.7% below avg. Ytd Growth: 1.9%; Avg 19>26: +4.8%; Real: 3.6%. % Real Growth: 72.7%
  • Clothing and Accessories – Clothes mattered less if you stayed home. That changed in March 2021 with strong growth through 2022. Sales are +4.4% from July and positive in all YOY measurements. $ales are +3.5% vs August 25, 10.9% more than their 3.1% avg. Ytd Growth: 5.4%; Avg 19>26: +3.6%; Real: 2.2%. % Real Growth: 60.2%.
  • Home Furnishings – In mid-2020, consumers’ focus turned to their homes and furniture became a priority. Prices stopped deflating in August. $ are +0.8% from July, but they are only actually up vs August 25 and vs 2019. YOY vs August 25, they are +0.8%, -72.4% below their 3.1% avg lift. Ytd Growth: -1.6%; Avg 19>26: +2.1%; Real: -0.1%. % Real Growth: None
  • Electronic/Appliances – They have had many issues. $ fell in Apr>May of 2020 and didn’t reach 2019 levels until March 21. $ are +1.9% from July and up in all comparisons. Strong deflation made real sales very high. Sales are +7.9% vs August 25, 3.5 times above the 2.3% avg. Ytd Growth: 6.7%; Avg 19>26: 1.4%; Real: 4.6%. % Real Growth: 100+%
  • Bldg Matl, Farm, Garden, Hdwe – They benefited from the consumers’ focus on home. In 22 the lift slowed as inflation grew to 10+%. Prices rose again in Apr>Sep 25, dropped Oct/Nov, rose Dec/Jan to 5.6%, fell Feb to 4.8%, rose Mar to 6.0%, fell Apr>Aug to 1.4%. $ are -6.5% from July and are actually up & really down vs 2021. All other comparisons are up. $ vs August 25 were +5.2%, 31% above their 4.0% Avg. Ytd Growth: 4.6%; Avg 19>26: 4.4%; Real: 0.8%. % Real Growth: 15.3%
  • Sporting Goods, Hobby and Book Stores – Consumers turned their attention to recreation and Sporting Goods stores sales took off. Book & Hobby Stores recovered more slowly. They have been on a sales roller coaster since June 24 and $ are +10.0% from July. All YOY comparisons are again positive. YOY Sales vs August 25 are +9.4%, 3.1 times more than their 3.0% avg. Ytd Growth: +10.1%; Avg 19>26: +4.8%; Real: 3.7%. % Real Growth: 75.8%.
  • All Miscellaneous Stores – Pet Stores have been a key part of the strong and growing recovery of this group. They finished 2020 at +0.9% but sales took off in March 21 and have continued to grow. Sales are -3.6% vs July, but positive in all comparisons. They are 2nd in the % increase vs 19 & vs 21. Plus, their 12.6% YOY August lift is 3.0 times their 92>25 avg of +4.2%. Ytd Growth: +11.0%; Avg 19>26: +7.6%; Real: 5.8%. % Real Growth: 72.2%.
  • NonStore Retailers – 90% of their $ comes from Internet/Mail Order/TV. The pandemic accelerated online spending. They ended 2020 +21.4%. The growth continued in 2021 as sales exceeded $100B for the 1st time and they broke the $1 Trillion barrier. $ are -1.3% from July, but their YOY lift of 10.4% is 1.6% above the 10.2% avg. Plus, they are positive in all comparisons. Ytd Growth: 10.3%; Avg 19>26: +13.1%; Real: 11.1%. % Real Growth: 80.0%.

Recap – Driven by Relevant Retail, the Pandemic recovery was widespread by Y/E 21. In 22 we were hit with the strongest inflation in 40 years. Inflation has slowed considerably from its Jun 22 peak, but only 2 smaller channels are now deflating. Deflation helps, but cumulative inflation can still have a negative impact – slowed YOY growth and even sales drops. In a small surprise since Relative Retail was -0.5%, $ rose from July for 7 of 11 small channels. However, only 1 of the lifts was above avg. The biggest concern is still YOY drops and smaller lifts.  Relevant Retail’s 4.9% lift vs August 25 was 5.9% above avg. 10 channels had a YOY lift vs 25, the same as July. 7 of the lifts were above avg, 1 more than July. There are many factors affecting growth, but the major one is retail pricing. Feb is usually the worst retail month. August is the 3rd best, but the Jul>Aug lift is the 3rd smallest of 7 (Rel Retl $ dropped again). Both Total & Relevant Retail had record monthly sales for Dec>Aug 26. The August Rel Retl YOY lift was above avg and the biggest since 2022. 7 smaller channels had an above average lift, tied w/June for the most in 26. When we look closer, performance and progress improved a little in August. We’ll see what happens in September.

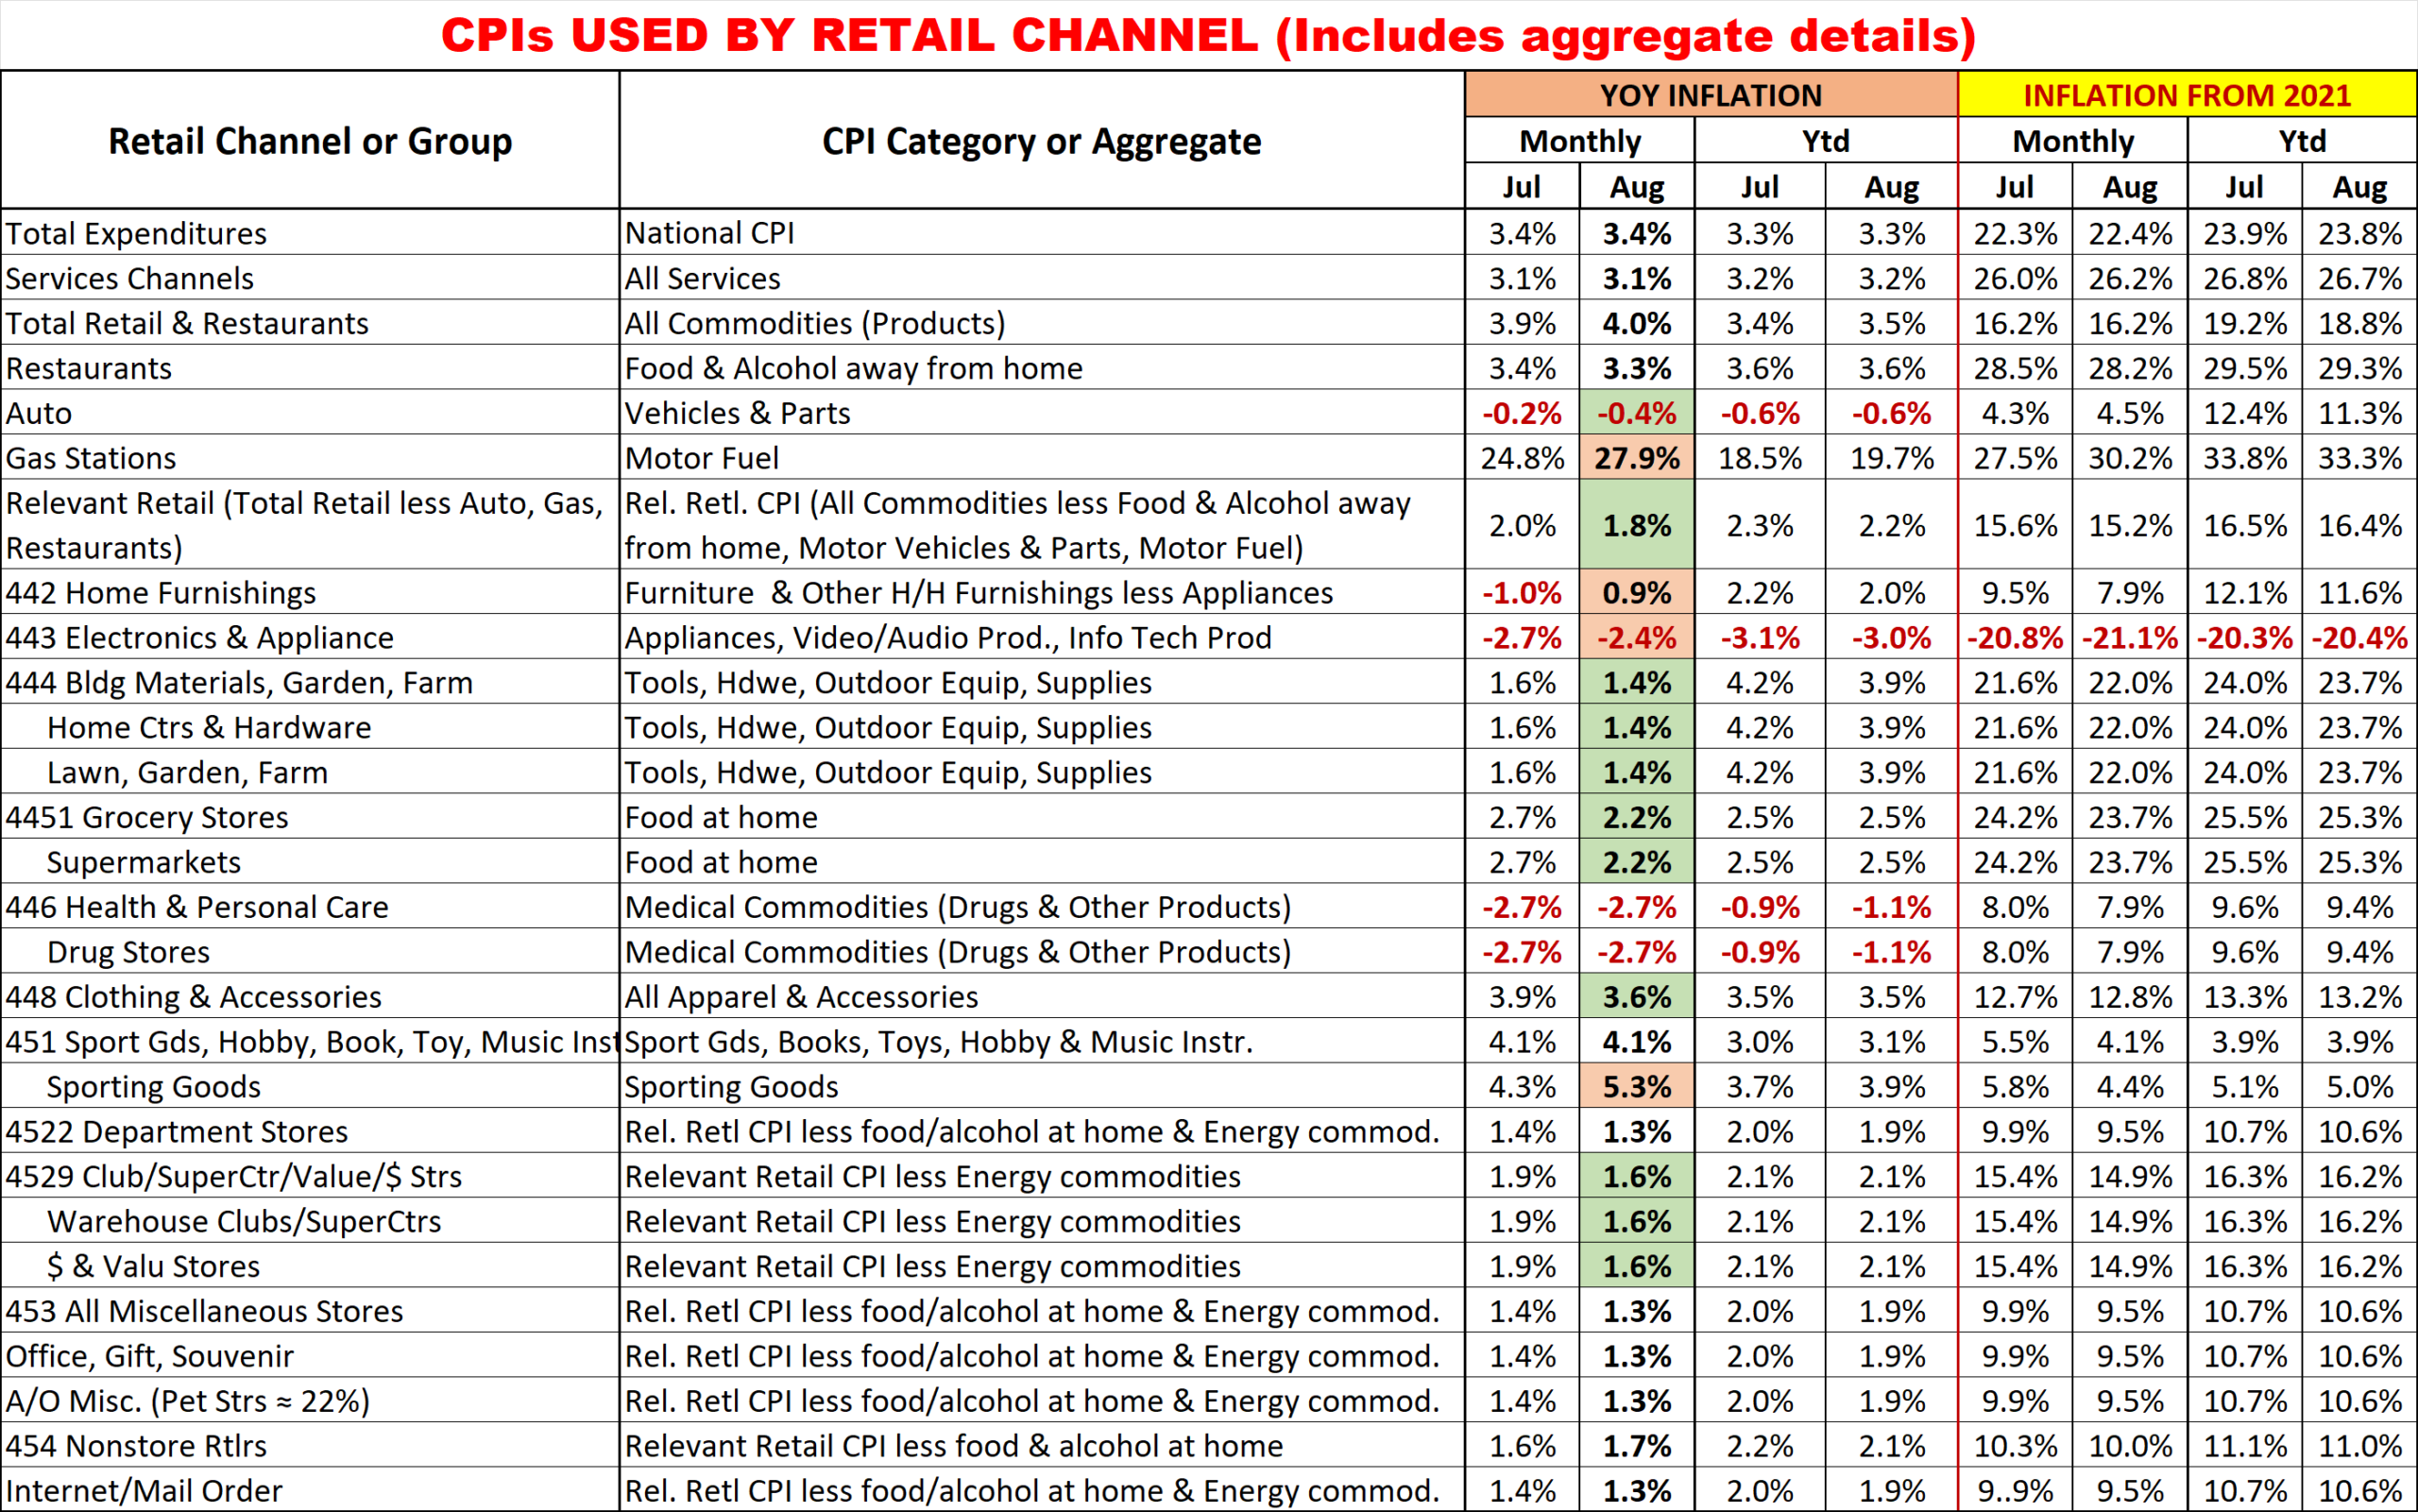
Here are the Jul/Aug inflation rates for the CPIs used to calculate the impact of inflation on retail groups and channels. This includes special aggregate CPIs created with the instruction and guidance of the US BLS. I also researched data from the last Economic Census to review the share of sales by product category for the various channels to help in selecting what expenditures to include in specific aggregates. Of course, none of these specially created aggregates are 100% accurate but they are much closer than the overall CPI or available aggregates. The data includes the CPI changes vs 21 to show cumulative inflation.

Monthly YOY CPI changes of 0.2% or more are highlighted. (Green = lower; Pink = higher)Here are some answers to some obvious questions. Note: Inflation slowed slightly for most.  

  • Why is the group for Nonstore different from the Internet?
    • Non-store is not all internet. It also includes Fuel Oil Dealers, the non-motor fuel Energy Commodity.
  • Why is there no Food at home included in Nonstore or Internet?
    • Online Grocery purchasing is becoming popular, but almost all is from companies whose major business is brick ‘n mortar. These online sales are recorded under their primary channel.
  • 5 Channels have the same CPI aggregate but represent a variety of business types.
    • They also have a wide range of product types. Rather than try to build aggregates of a multitude of small expenditure categories, it seemed better to eliminate the biggest, influential groups that they don’t sell. This method is not perfect, but it is certainly closer than any existing aggregate.
  • Why are Grocery and Supermarkets only tied to the Grocery CPI?
    • According to the Economic Census, 76% of their sales comes from Grocery products. Grocery Products are the driver. The balance of their sales comes from a collection of a multitude of categories.
  • What about Drug/Health Stores only being tied to Medical Commodities?
    • An answer similar to the one for Grocery/Supermarkets. However, in this case Medical Commodities account for over 80% of these stores’ total sales.
  • Why do SuperCtrs/Clubs and $ Stores have the same CPI?
    • While the Big Stores sell much more fresh groceries, Groceries account for ¼ of $ Store sales. Both Channels generally offer most of the same product categories, but the actual product mix is different.