Retail Channel $ Update – July Monthly & August Advance
In August, YOY Commodities’ inflation rose to 4.0% from 3.9%, largely due to Gasoline. High cumulative inflation vs 21 can slow $ales growth and of course, current inflation changes can affect growth, but not always. We saw examples of all of these in August. Total Retail $ were +5.3% vs 25, 13.9% above the avg 92>25 lift. Relevant Retail’s inflation dropped from 2.0% to 1.8% and sales were +4.9%, 5.9% above their avg. The situation is definitely complex. We’ll continue to track the retail market with data from 2 reports provided by the Census Bureau and factor in targeted CPIs.
The Census Bureau Reports are the Monthly and the Advance Retail Sales Reports. Both are derived from sales data gathered from retailers across the U.S. and are published monthly at the same time. The Advance Report has a smaller sample size so it can be published quickly – normally, 2 weeks after month end. The Monthly Report includes data from all respondents, so it takes longer to compile the data – about 6 weeks. Although the sample size for the Advance report is smaller, the results over the years have proven it to be statistically accurate with the Monthly reports. The biggest difference is that the full sample in the Monthly report allows us to “drill” a little deeper into the retail channels.
We will begin with the July Monthly Report and then go to the August Advance Report. Our focus is comparing to last year but also 21 & 19. We’ll show both actual and the “real” change in sales as we factor inflation into the data.
Both reports include the following:
- Total Retail, Restaurants, Auto, Gas Stations and Relevant Retail (removing Restaurants, Auto and Gas)
- Individual Channel Data – This is more detailed in the Monthly reports, and we’ll focus on Pet Relevant Channels.
The data will be presented in detailed charts to facilitate visual comparison between groups/channels. The charts will show 11 separate measurements. To save space they will be displayed in a stacked bar format for the channel charts.
- Current Month change – % & $ vs previous month
- Current Month change – % & $ vs same month last year and vs 2021.
- Current Month Real change vs last year and vs 2021 – % factoring in inflation
- Current Ytd change – % & $ for this year vs last year, 2021 & 2019.
- Current Ytd Real change % for this year vs last year and vs 2021 and 2019
- Monthly & Ytd $ & CPIs for this year vs last year and vs 2021 which are targeted by channel will also be shown. (CPI Details are at the end of the report)
First, the July Monthly. All were up from June and there were no actual sales drops. There were 5 “real” drops and Gas Stations are again selling less product than in every comparison year, even 2019. However, Relevant Retail is all positive again. They’ve been all positive in 26 of the last 28 months. ($ are Not Seasonally Adjusted)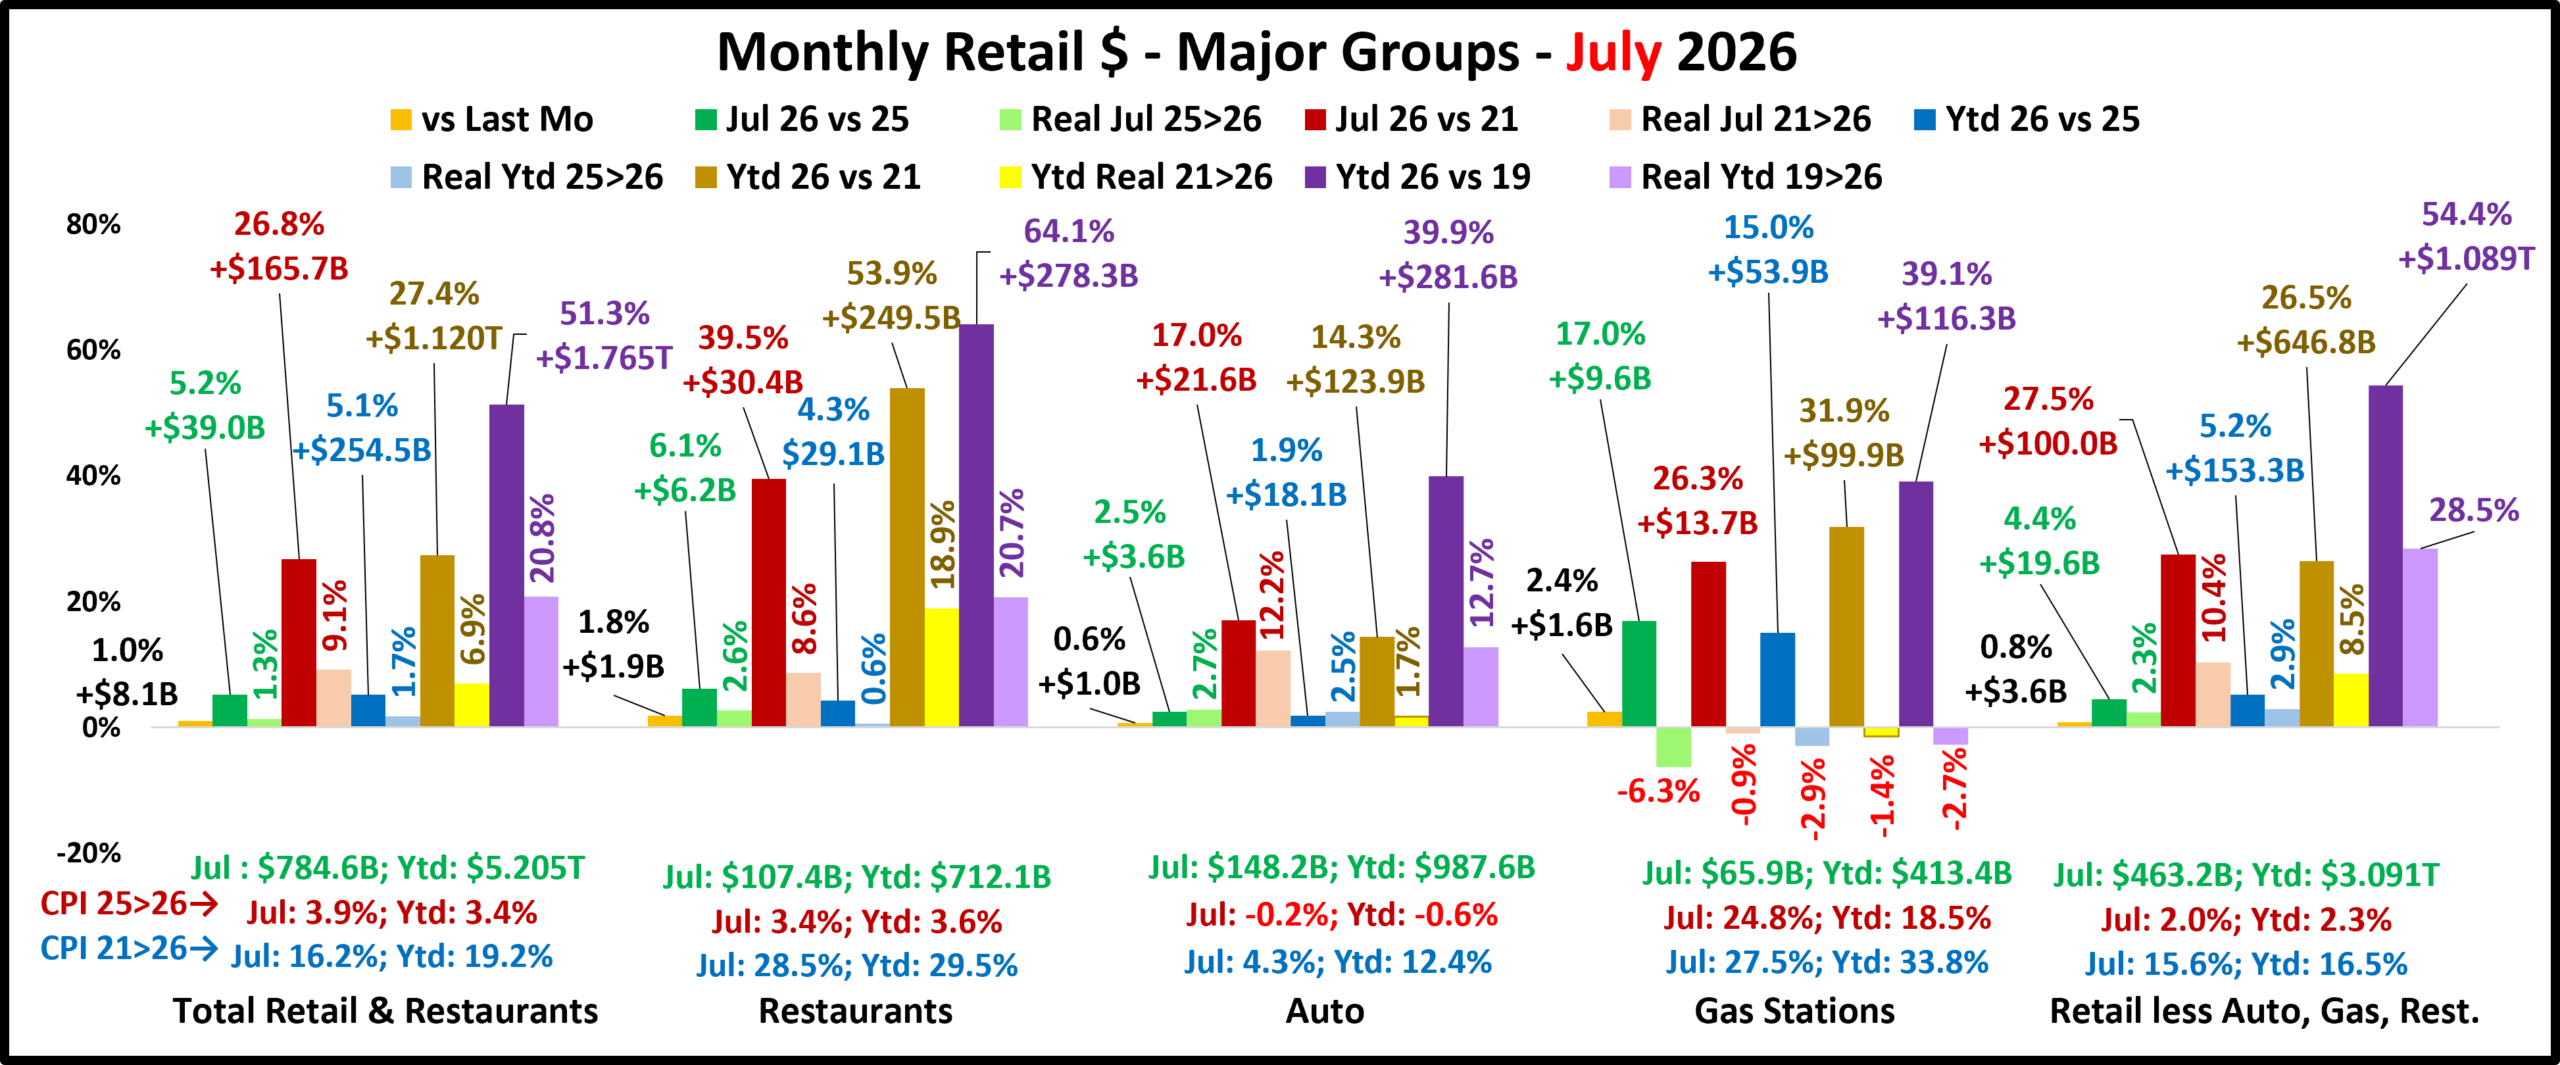
The July Monthly has the same total $ as the Advance, but the individual groups are different. Restaurants: +$0.2B; Auto: +$0.1B; Gas Stations: +$0.5B; Relevant Retail: -$0.8B. The lifts from June were not unexpected. A Jun>Jul increase in Total Retail has happened in 57% of the years since 1992. However, the 1.0% lift was 2.5 times more than the 0.4% avg. There were no drops in actual sales, but again there were 5 “real” drops (all Gas Stations) – 6 in May, 9 in Apr, 7 in Mar, but none in Dec>Feb. Like June, 4 groups were all positive, up from 3 in May, 1 in Apr & 2 in Mar, but equal to Feb. Restaurants still have the biggest increases vs 21 & 19 but Relevant Retail stayed at the top of “real” performance vs 2019. However, only 52.4% of their growth is real.
Now, let’s see how some Key Pet Relevant channels did in July in the Stacked Bar Graph Format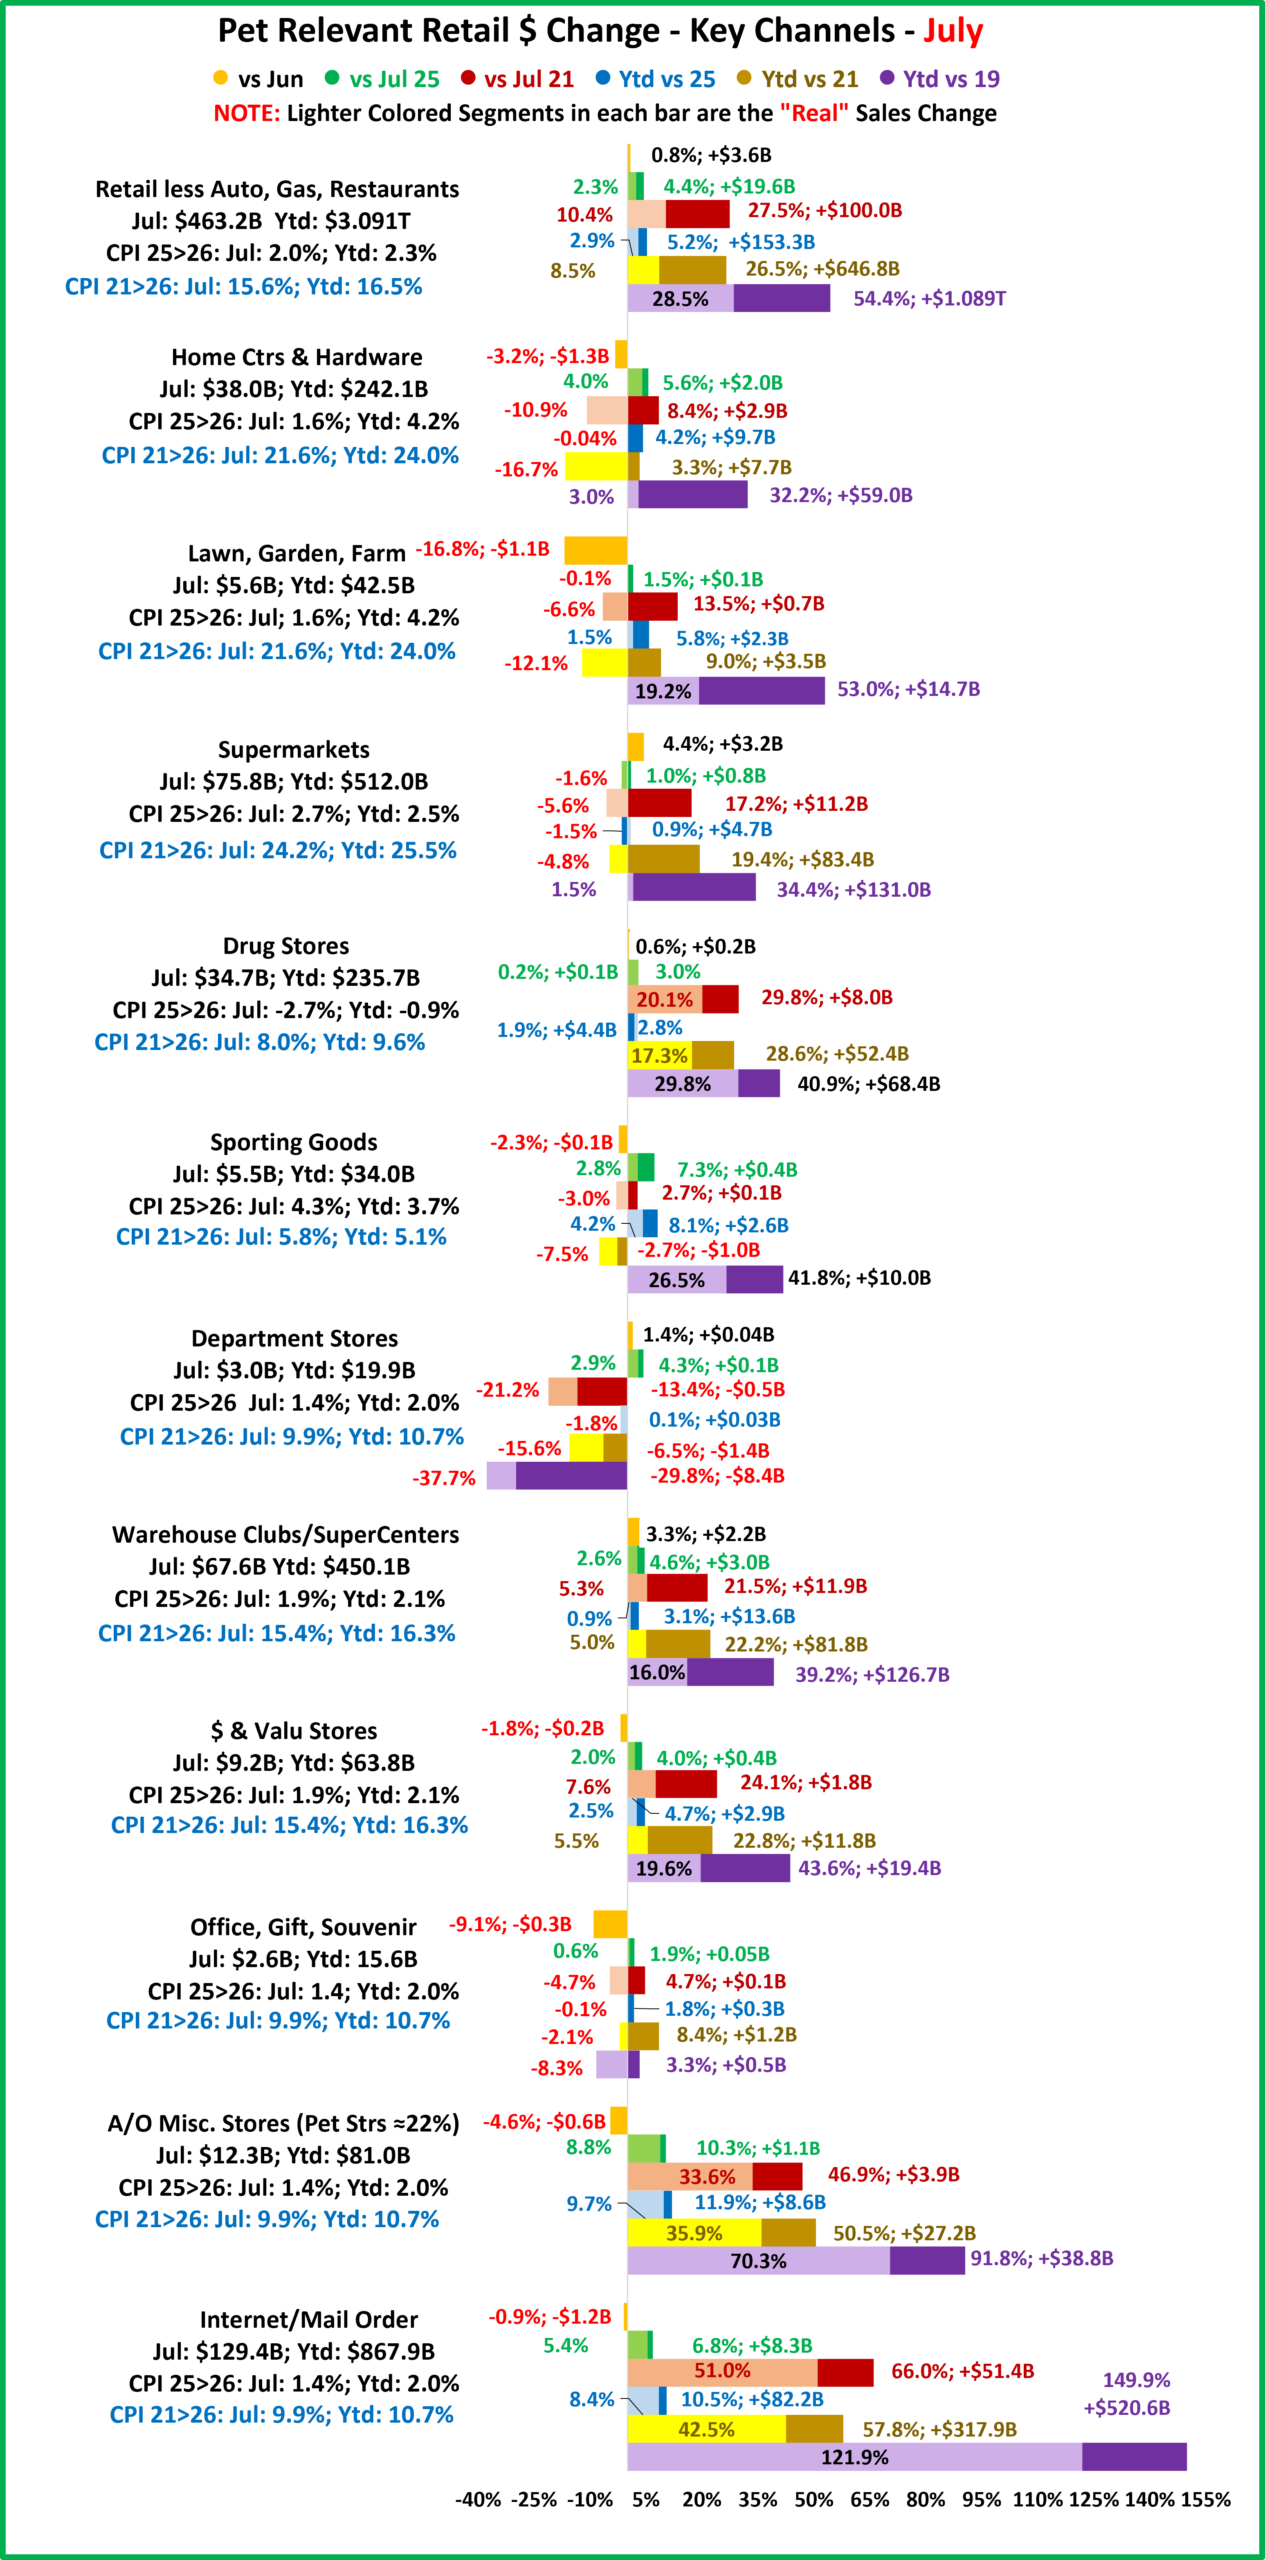
Overall– 4 of 11 were up from June. Vs Jul 25, 11 were actually and 9 “really” up. Vs Jul 21, 10 were up but only 5 were real lifts. Vs 2019, Only Dept Strs were actually & really down, but Off/Gift/Souv was really down.
- Building Material Stores – The pandemic focus on home has produced $ growth of 35.6% since 2019. Prices for the group are +21.6% from 21 and +27.4% from 2019, which is impactful. As the Spring lift ends, HomeCtr/Hdwe Sales vs June were -3.2% and -16.8% for Farm. Vs other years, both are actually up for all. HomeCtr/Hdwe is only really up vs July 25 & 2019. Farm stores are really up YTD vs 25 & 19. Bldg Mat’s 19>26 real growth was 5.7% avg: 0.8%. HomeCtr/Hdwe: Ytd: 4.2%; Avg 19>26 Growth: 4.1%, Real: 0.4%; Farm: Ytd:+5.8%; Avg: 6.3%, Real: 2.5%
- Food & Drug – Both are essential. Except for the COVID food binge, they tend to have smaller changes in $. Vs June: Supermarkets: +4.4%; Drug: +0.6%. In terms of inflation, the Groceries rate is 2.7%, while Drug/Med products are still deflating, -2.7%. Drug Stores are positive in all measurements and 72.9% of their 2019>26 growth is real. Supermarkets’ actual $ are up in all comparisons, but they are only “really” up vs 2019. Plus, only 4.4% of their 19>26 increase is real growth. Supermarkets: Ytd: +0.9%; Avg 19>26: +4.3%, Real: +0.2%; Drug Stores: Ytd: +1.9%; Avg: +5.0%, Real: +3.8%.
- Sporting Goods Stores – They also benefited from the pandemic in that consumers turned to self-entertainment, especially sports & outdoor activities. Sales are -2.3% vs June. They are only actually & really negative ytd vs 21 and really vs July 21. Prices stopped deflating. Deflation started in April 23 and was a big change from +1.1% in 22>23 & +7.9% in 21>22. This caused 63.4% of their 41.8% lift since 2019 to be real. Ytd: +8.1%; Avg 19>26: +5.1%; Real: +3.4%
- Gen Mdse – $ vs June: SupCtr/Club; +3.3%; $ Strs: -1.8%; Dept Strs: +1.4%. All comparisons were up for $ Strs & SupCtr/Club. Dept Stores are negative for all but vs July 25 & actual YTD vs 25. Their Actual sales are even -29.8% from 2019 (real:-37.7%). The other channels have an average of 39.7% in growth. SupCtr/Club: Ytd: +3.1%; Avg 19>26: 4.8%, Real: 2.1%; $/Value Strs: Ytd: +4.7%; Avg: +5.3%, Real: +2.6%; Dept. Strs: Ytd: +0.1%; Avg: -4.9%, Real: -6.5%.
- Office, Gift & Souvenir Stores – Sales are -9.1% vs June. They are actually up for all but only really up vs July 25. Their recovery restarted Jun/Jul 25, but took off in Oct, slowed Nov, grew Dec, slowed Jan>Mar, grew in Apr, slowed in May, restarted in June, then slowed a little in July. Ytd:+1.8%; Avg Growth Rate: 0.5%,Real: -1.2%
- Internet/Mail Order – Sales are -0.9% vs June but still set a July record. All YOY measurements are positive, but their YOY growth, +11.2%, is only 75.0% of their average since 2019. However, 81.3% of their 149.9% growth since 2019 is real. Ytd: +10.5%; Avg Growth: +14.0%, Real: +12.1%. As expected, they are by far the growth leader since 2019.
- A/O Miscellaneous – Pet Stores are 22>24% of total $. In May 2020 they began recovery which reached $100B for the 1st time in 21. In 22 their $ dipped in 4 months, rose Dec, fell Jan>Feb 23, grew Mar>May, fell Jun>Aug, rose Sep>Nov, fell Dec>Jan 24, grew Feb>May, fell Jun>Sep, grew Oct, fell Nov, rose Dec, fell Jan>Feb 25, grew Mar>May, fell Jun>Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb/Mar, fell Apr, rose May/Jun, fell -4.6% in July. They’re all positive & are #2 in the increase vs 19 & vs 21. Also, 76.6% of their 91.8% growth since 2019 is real. Ytd: +11.9%; Avg 19>26: 9.8%, Real: +7.9%
July had a small lift vs June, but far above avg. Rel Retl was +0.8% (avg: -0.1%). However, only 4 small channels were up. The YOY lift vs 25 was 12% above avg for Total, but -6% below avg for Relevant Retl. All big groups & all smaller channels had lifts. Prices are only deflating in Auto & Drug, but cumulative inflation has an impact, as only 5 of 11 channels were really up vs July 21. Recovery is slow. In August, the commodities CPI rose slightly from 3.9% to 4.0%. Let’s see if it impacts Retail.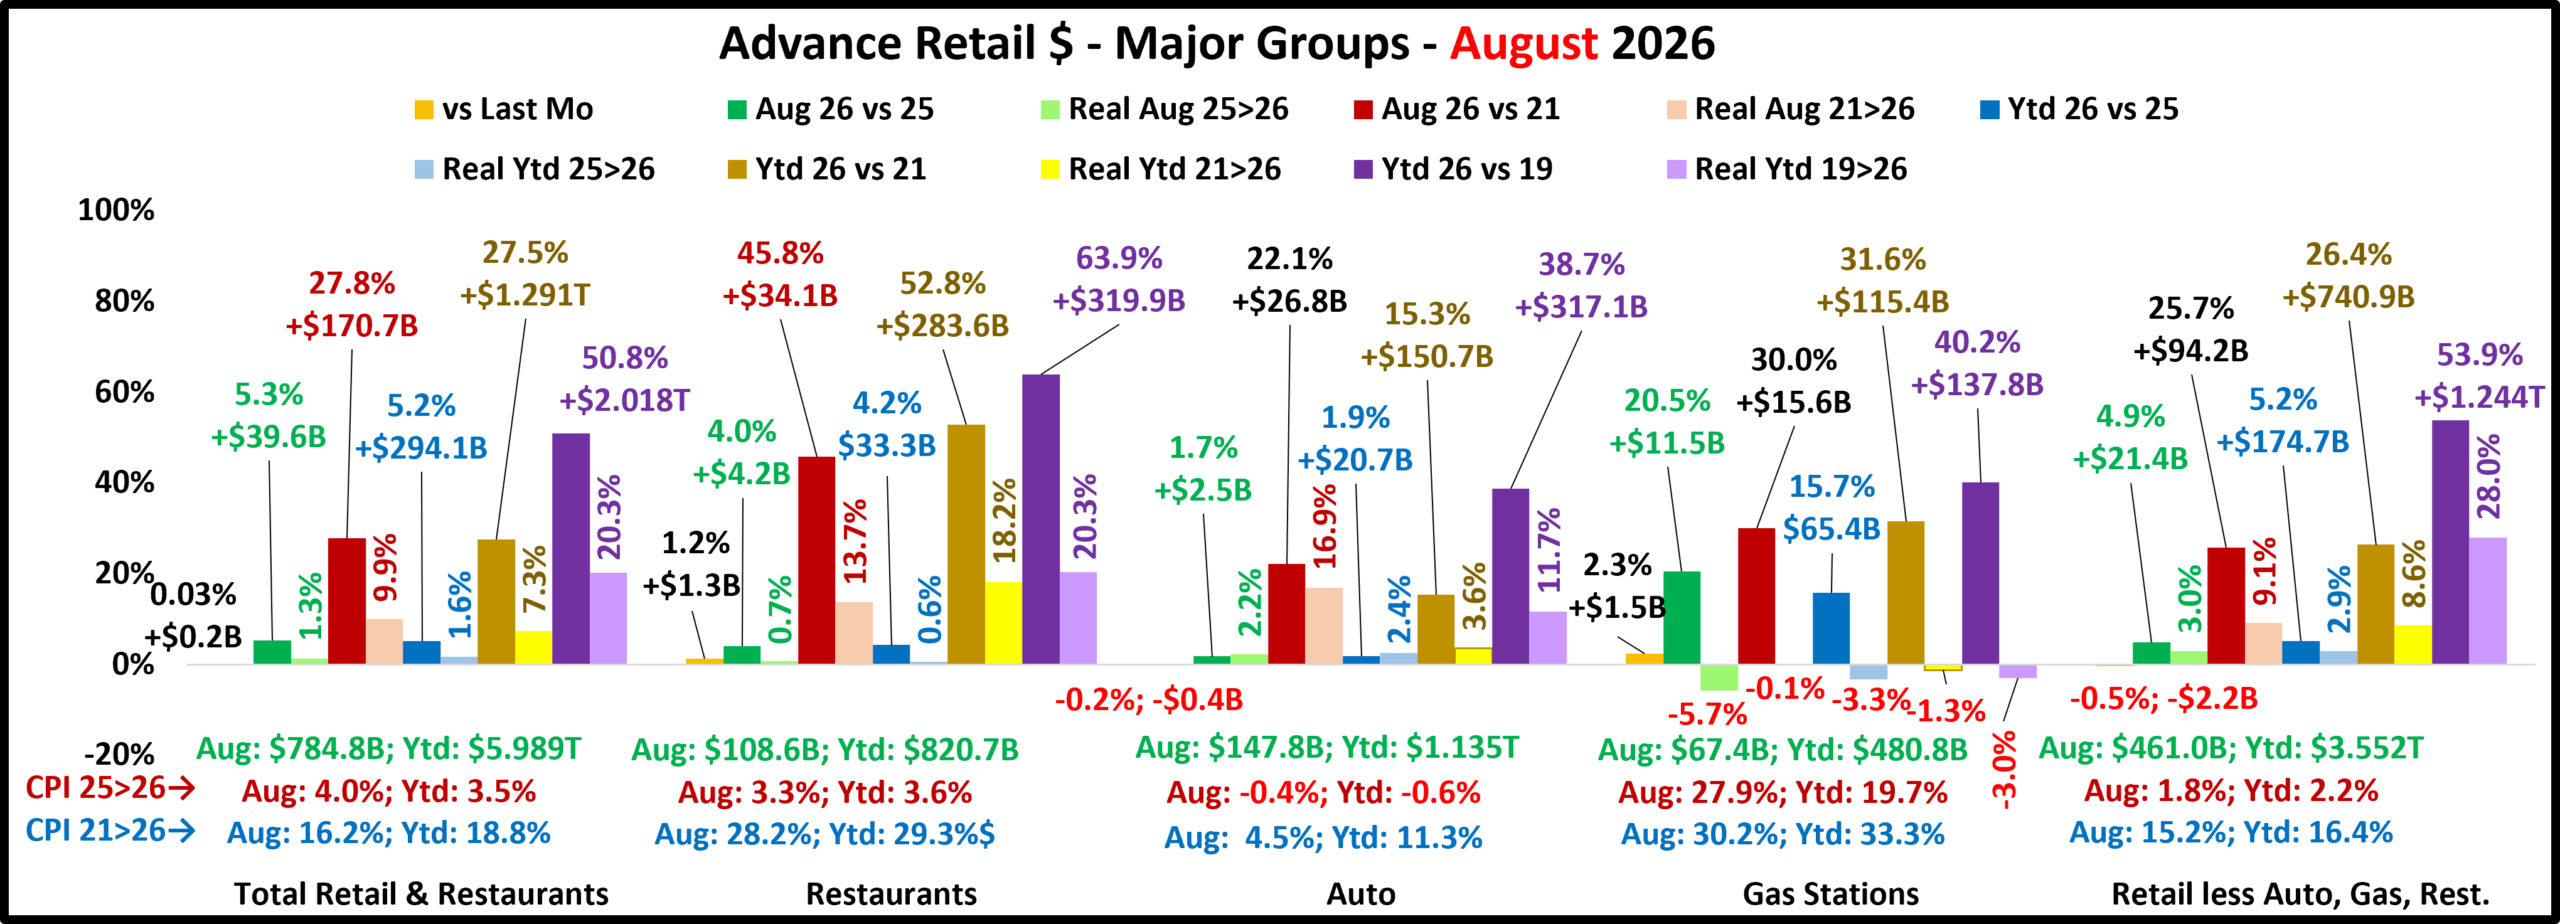
3 were up from July. Rel Retl was -0.5%. A Jul>Aug Total Retail lift has happened in 80% of the yrs since 1992, but the 0.03% lift is -99% less than the 2.1% avg. There were no YOY $ drops, the same as May>Jul. All Big Groups were up vs 25 and the Total Retail lift of 5.3% vs August 25 was 13.9% above their +4.7% 92>25 avg. The Relevant Retail 4.9% increase vs August 25 was 5.9% above their +4.6% avg. The CPI for all commodities rose to 4.0% from 3.9% in July and it is still +16.2% vs 21. There is some “real” news. In Jan/Feb, no “real” measurement was down. In Mar there were 7, in Apr 9, in May 6, in Jun>Aug 5. Gas Stations are still selling less Gas than in all comparison yrs. However, like Jun/Jul, 4 Big Groups are all positive, up from 3 in May, 2 in Apr & 1 in Mar. Note: Relevant Retail has been all positive in 27 of the last 29 months.
Overall Inflation Reality– The Total Retail CPI rose to 4.0%, but the $ lift vs 25 was 13.9% above avg. The Restaurant CPI slowed to +3.3% from +3.4%, but their $ lift was -27.5% below avg. The Gas CPI rose from 24.8% to 27.9%. They are in turmoil. Auto inflation is -0.4% vs 25 and only 4.5% vs 21. Sales were +1.7% vs 25. Their avg change is +4.5%. Inflation slowed to 1.8% from 2.0% for Relevant Retail and their lift was 5.9% above avg. They are again all positive. Progress is complex in 26.
Total Retail – Since June 20, every month but April 23, Jun 24 & Feb 25 has set a monthly $ record. In 23>26, Sales got on a roller coaster. Up Oct>Dec, down Jan 24, up Feb>Mar, down Apr, up May, down Jun, up Jul>Aug, down Sep, up Oct>Dec, down Jan>Feb 25, up Mar, down Apr, up May, down Jun, up Jul>Aug, down Sep, up Oct, down Nov, up Dec, down Jan/Feb 26, up Mar, down Apr, up May, down Jun, up Jul/Aug. Prices are +4.0% and YOY $ are +5.3%, 13.9% above avg. 41% of 19>26 growth is real. The small inflation lift didn’t impact YOY $. Growth: 25>26: 5.2%; Avg 19>26: +6.0%, Real: +2.7%
Restaurants – They were hit hard by the pandemic and didn’t begin recovery until Mar 21. However, they have had strong growth since then, exceeding $1T for the 1st time in 23. August $ are +1.2% from July and +4.0% vs 25, but they have the biggest lifts vs 21 & 19. Inflation slowed to 3.3% from 3.4% vs last year, but it is +28.2% vs 21 and +36.2% vs 19. Their 4.0% YOY lift is -27.5% below their +5.6% 92>25 avg. They are again all positive, but just 31.8% of their 63.9% growth since 2019 is real. They are 3rd in performance. Recovery started late but inflation started early. Growth: 4.2%; Avg 19>26: +7.3%, Real: +2.7%. They just account for 13.7% of Total Retail $, but their strong growth has helped Total Retail.
Auto (Motor Vehicle/Parts Dealers) – They overcame the stay-at-home attitude with deals & advertising. They finished 2020 up 1% vs 2019 and hit a record $1.48T in 2021 but much was due to high prices. In 22, sales got on a rollercoaster. Inflation started to drop mid-year, but it caused 4 down months in $. Their YE real 22 sales were even worse, -8.2% vs 21 and -8.9% vs 19. 23 began a sales rollercoaster but set a record, $1.595T. $ fell Jan 24, grew Feb/Mar, fell Apr, grew May, fell June, grew Jul/Aug, fell Sep, grew Oct, fell Nov, grew Dec, fell Jan/Feb 25, grew Mar, fell Apr>Jun, rose Jul/Aug, fell Sep, rose Oct, fell Nov, rose Dec, fell Jan 26, rose Feb, fell Mar/Apr, rose May, fell Jun, rose Jul, fell -0.2% in Aug. August was +1.7% vs 25. Avg: 4.5%. They’re all positive, but just 30.2% of 19>26 growth is real. Growth: 1.9%; Avg 19>26: +4.8%, Real: +1.6%
Gas Stations – Gas Stations were hit hard by “stay at home”. They started recovery in March 21, and inflation began. Sales got on a rollercoaster in 22 but set a record, $583B. Inflation started to slow in August 22, and prices slightly deflated in Dec & Feb 23, then strongly fell in Mar>Jul to -20.2%. In Sep they were +2.7% but began deflating to -4.2% in Feb 24. In Mar>May $ grew, fell Jun, rose July, fell Aug/Sep, rose Oct, fell Nov>Feb 25, rose Mar>May, fell Jun, rose Jul, fell Aug>Oct, up Nov, fell Dec/Jan, skyrocketed Feb>May, fell Jun, rose Jul/Aug. August $ vs 25: +20.5% (4.4% avg). No $ drops, but all real $ are down. Growth: +15.7%; Avg 19>26: +4.9%, Real: -0.4%. Strong inflation can be “really” negative.
Relevant Retail – Less Auto, Gas and Restaurants– They account for ≈60% of Total Retail $ in a variety of channels. Their only down month until Feb 25 was Apr 20, and they led the way in Retail’s recovery. Sales got on a roller coaster in 22, but all months set new records with Dec reaching a new all-time high, $481B, and an annual record of $4.81T. In 23, the roller coaster continued. A Dec lift set a monthly record of $494.7B & an annual record of $4.997T. The roller coaster restarted in 24. $ rose Oct>Jan 25, fell Feb, rose Mar>May, fell Jun, rose Jul, fell Aug/Sep, rose Oct>Dec, fell Jan>Feb 26, rose Mar, fell Apr, rose May, fell Jun, rose Jul, fell Aug. The Aug 4.9% YOY lift is 5.9% above their 4.6% avg. They are all positive again & 52% of their 19>26 growth is real, #1 in performance. Growth: 5.2%; Avg 19>26: +6.3%, Real: +3.6%. In 24 their inflation rate fell from 3.2% to 0.1%. It rose in 25 to 1.8% in Sep, slowed to 1.5% Oct>Nov, rose to 2.0% Dec>Jan 26, Mar: 2.3%, Apr: 2.7%, fell to 2.5% in May, Jun: 2.1%, Jul: 2.0%, Aug 1.8%. Low inflation hasn’t spurred growth
August Retail $ rose vs July. Total Retl was +0.03%, 99% below avg; Relevant Retl was -0.5%. (avg: 2.8%). Like May>Jul, no actual comparison was negative. Mar had 1. Dec>Feb & Apr, 2. There were 5 real drops in Jun>Aug. May 6, Apr 9; Mar 7; Dec>Feb None. In Dec 25, all were up vs 24 but only Rel. Retl’s lift was above avg. In Jan 26, 3 lifts, all below avg. In Feb, 4 lifts, all below avg. In Mar/Apr, 4 lifts, 2 above avg. In May 5 lifts, 2 above avg. In Jun 5 lifts, 4 above avg. In Jul/Aug 5 lifts, 3 above avg. In Dec>Feb, 4 were all positive. Mar, 2. Apr, 1. May, 3, Jun>Aug, 4. Relevant Retail has now been all positive in 27 of 29 months. YOY inflation is relatively low for all but Gasoline. However, cumulative inflation can also slow sales.
Here’s a more detailed look at August by Key Channels in the Stacked Bar Graph Format 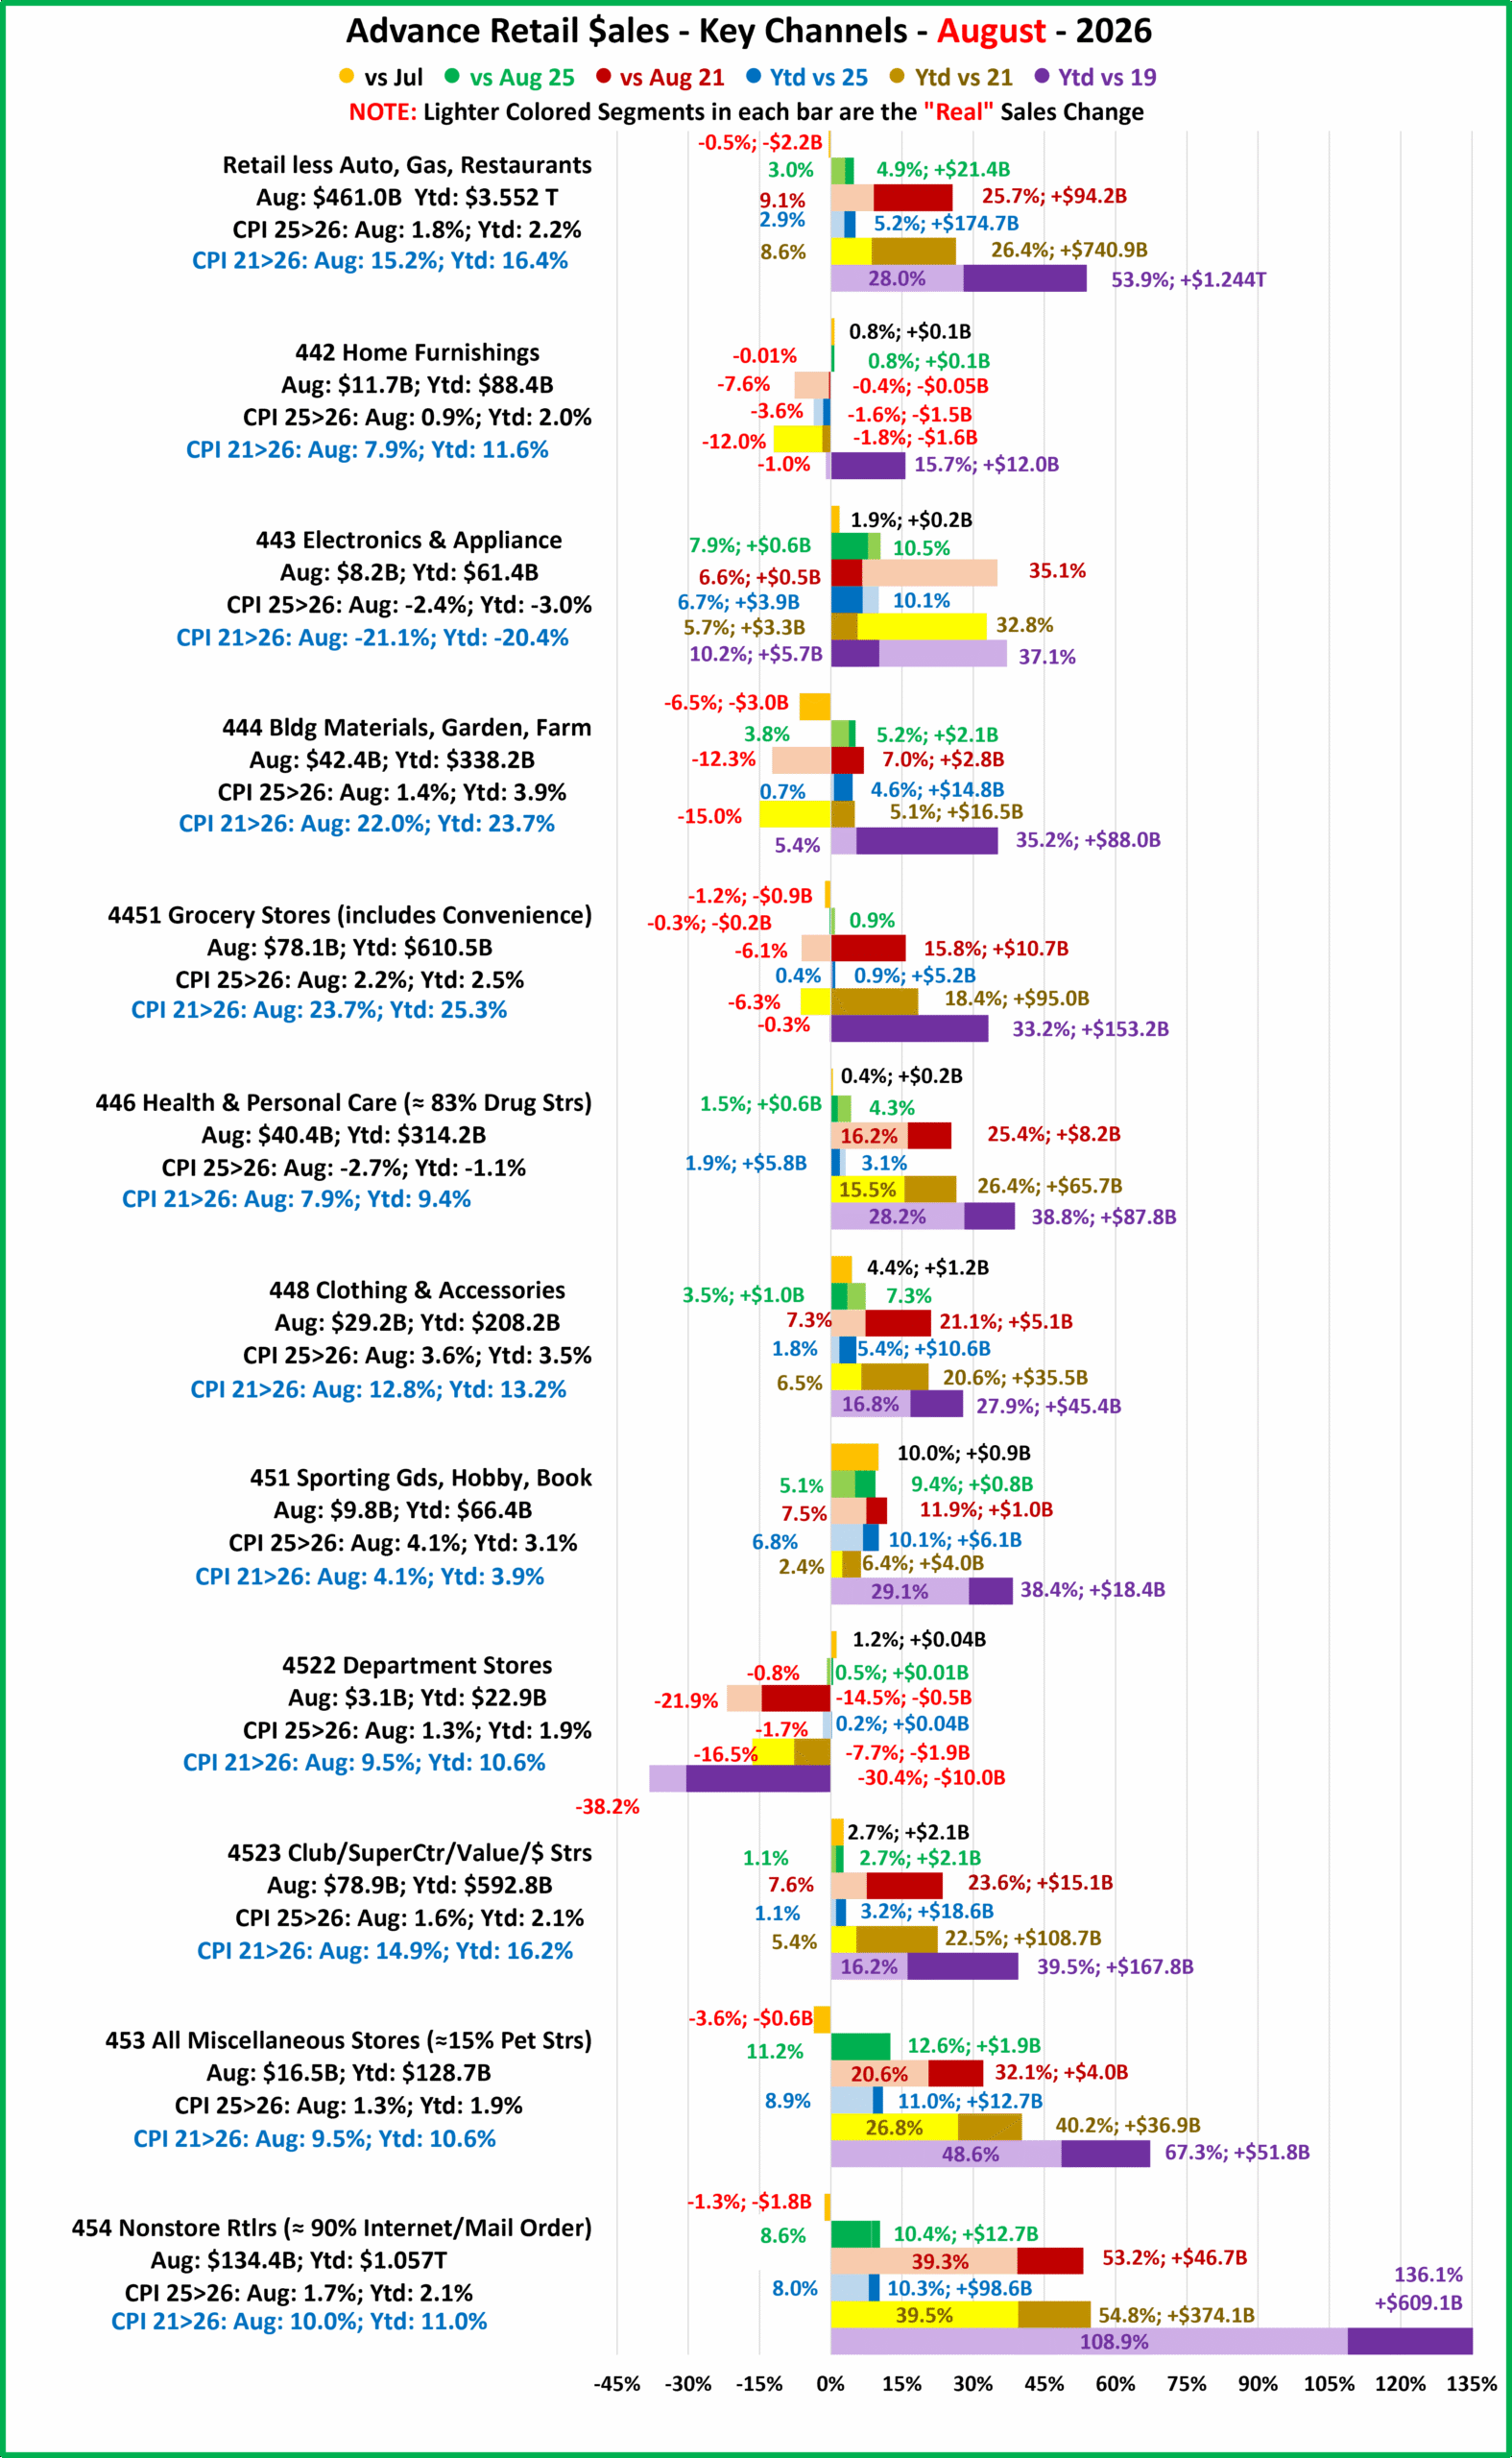 Relevant Retail: Ytd Growth: +5.2%; Avg 19>26: +6.3%; Real: 3.6%. % Real Growth: 51.9%. 7 of 11 were up from July. Vs Aug 25: 10 were up, 9 Real. Vs Aug 21: 9 were up; 7 Real. Vs 19: Dept Stores were down & “real” Furniture & Grocery
- All Department Stores – This group was struggling before the pandemic hit them hard. They began recovery in March 21. Sales are +1.2% from July, but all YOY measurements except actual August & YTD vs 25 are negative. Their 0.5% August YOY lift is much better than their -4.7% avg. Ytd Growth: +0.2%; Avg 19>26: -5.1%; Real: -6.7%. % Real growth: None
- Club/SuprCtr/$- They fueled a big part of the recovery because they focus on value which has broad consumer appeal. $ales are +2.7% from July, and they are up in all comparisons. Their 2.7% YOY August lift is -66.7% below their 92>25 avg of +8.2%. Ytd Growth: 3.2%; Avg 19>26: +4.9%; Real: 2.2%. % Real Growth: 41.0%
- Grocery- They depend on frequent purchases, so their changes are usually less radical. $ales are -1.2% from July. They are actually up for all but really down for all but YTD vs 2025. Cumulative inflation has hit them hard. Their -0.3% YOY August drop is far below their +3.1% avg. Ytd Growth: 0.9%; Avg 19>26: +4.2%; Real: -0.04%. % Real Growth: None
- Health/Drug Stores – Many stores are essential, but consumers visit less frequently than Grocery stores. $ are +0.4% from July and positive in all YOY comparisons. Inflation has been relatively low, so it is surprising that their +1.5% YOY lift vs August 25 is 71.7% below avg. Ytd Growth: 1.9%; Avg 19>26: +4.8%; Real: 3.6%. % Real Growth: 72.7%
- Clothing and Accessories – Clothes mattered less if you stayed home. That changed in March 2021 with strong growth through 2022. Sales are +4.4% from July and positive in all YOY measurements. $ales are +3.5% vs August 25, 10.9% more than their 3.1% avg. Ytd Growth: 5.4%; Avg 19>26: +3.6%; Real: 2.2%. % Real Growth: 60.2%.
- Home Furnishings – In mid-2020, consumers’ focus turned to their homes and furniture became a priority. Prices stopped deflating in August. $ are +0.8% from July, but they are only actually up vs August 25 and vs 2019. YOY vs August 25, they are +0.8%, -72.4% below their 3.1% avg lift. Ytd Growth: -1.6%; Avg 19>26: +2.1%; Real: -0.1%. % Real Growth: None
- Electronic/Appliances – They have had many issues. $ fell in Apr>May of 2020 and didn’t reach 2019 levels until March 21. $ are +1.9% from July and up in all comparisons. Strong deflation made real sales very high. Sales are +7.9% vs August 25, 3.5 times above the 2.3% avg. Ytd Growth: 6.7%; Avg 19>26: 1.4%; Real: 4.6%. % Real Growth: 100+%
- Bldg Matl, Farm, Garden, Hdwe – They benefited from the consumers’ focus on home. In 22 the lift slowed as inflation grew to 10+%. Prices rose again in Apr>Sep 25, dropped Oct/Nov, rose Dec/Jan to 5.6%, fell Feb to 4.8%, rose Mar to 6.0%, fell Apr>Aug to 1.4%. $ are -6.5% from July and are actually up & really down vs 2021. All other comparisons are up. $ vs August 25 were +5.2%, 31% above their 4.0% Avg. Ytd Growth: 4.6%; Avg 19>26: 4.4%; Real: 0.8%. % Real Growth: 15.3%
- Sporting Goods, Hobby and Book Stores – Consumers turned their attention to recreation and Sporting Goods stores sales took off. Book & Hobby Stores recovered more slowly. They have been on a sales roller coaster since June 24 and $ are +10.0% from July. All YOY comparisons are again positive. YOY Sales vs August 25 are +9.4%, 3.1 times more than their 3.0% avg. Ytd Growth: +10.1%; Avg 19>26: +4.8%; Real: 3.7%. % Real Growth: 75.8%.
- All Miscellaneous Stores – Pet Stores have been a key part of the strong and growing recovery of this group. They finished 2020 at +0.9% but sales took off in March 21 and have continued to grow. Sales are -3.6% vs July, but positive in all comparisons. They are 2nd in the % increase vs 19 & vs 21. Plus, their 12.6% YOY August lift is 3.0 times their 92>25 avg of +4.2%. Ytd Growth: +11.0%; Avg 19>26: +7.6%; Real: 5.8%. % Real Growth: 72.2%.
- NonStore Retailers – 90% of their $ comes from Internet/Mail Order/TV. The pandemic accelerated online spending. They ended 2020 +21.4%. The growth continued in 2021 as sales exceeded $100B for the 1st time and they broke the $1 Trillion barrier. $ are -1.3% from July, but their YOY lift of 10.4% is 1.6% above the 10.2% avg. Plus, they are positive in all comparisons. Ytd Growth: 10.3%; Avg 19>26: +13.1%; Real: 11.1%. % Real Growth: 80.0%.
Recap – Driven by Relevant Retail, the Pandemic recovery was widespread by Y/E 21. In 22 we were hit with the strongest inflation in 40 years. Inflation has slowed considerably from its Jun 22 peak, but only 2 smaller channels are now deflating. Deflation helps, but cumulative inflation can still have a negative impact – slowed YOY growth and even sales drops. In a small surprise since Relative Retail was -0.5%, $ rose from July for 7 of 11 small channels. However, only 1 of the lifts was above avg. The biggest concern is still YOY drops and smaller lifts. Relevant Retail’s 4.9% lift vs August 25 was 5.9% above avg. 10 channels had a YOY lift vs 25, the same as July. 7 of the lifts were above avg, 1 more than July. There are many factors affecting growth, but the major one is retail pricing. Feb is usually the worst retail month. August is the 3rd best, but the Jul>Aug lift is the 3rd smallest of 7 (Rel Retl $ dropped again). Both Total & Relevant Retail had record monthly sales for Dec>Aug 26. The August Rel Retl YOY lift was above avg and the biggest since 2022. 7 smaller channels had an above average lift, tied w/June for the most in 26. When we look closer, performance and progress improved a little in August. We’ll see what happens in September.
Here are the Jul/Aug inflation rates for the CPIs used to calculate the impact of inflation on retail groups and channels. This includes special aggregate CPIs created with the instruction and guidance of the US BLS. I also researched data from the last Economic Census to review the share of sales by product category for the various channels to help in selecting what expenditures to include in specific aggregates. Of course, none of these specially created aggregates are 100% accurate but they are much closer than the overall CPI or available aggregates. The data includes the CPI changes vs 21 to show cumulative inflation.
Monthly YOY CPI changes of 0.2% or more are highlighted. (Green = lower; Pink = higher)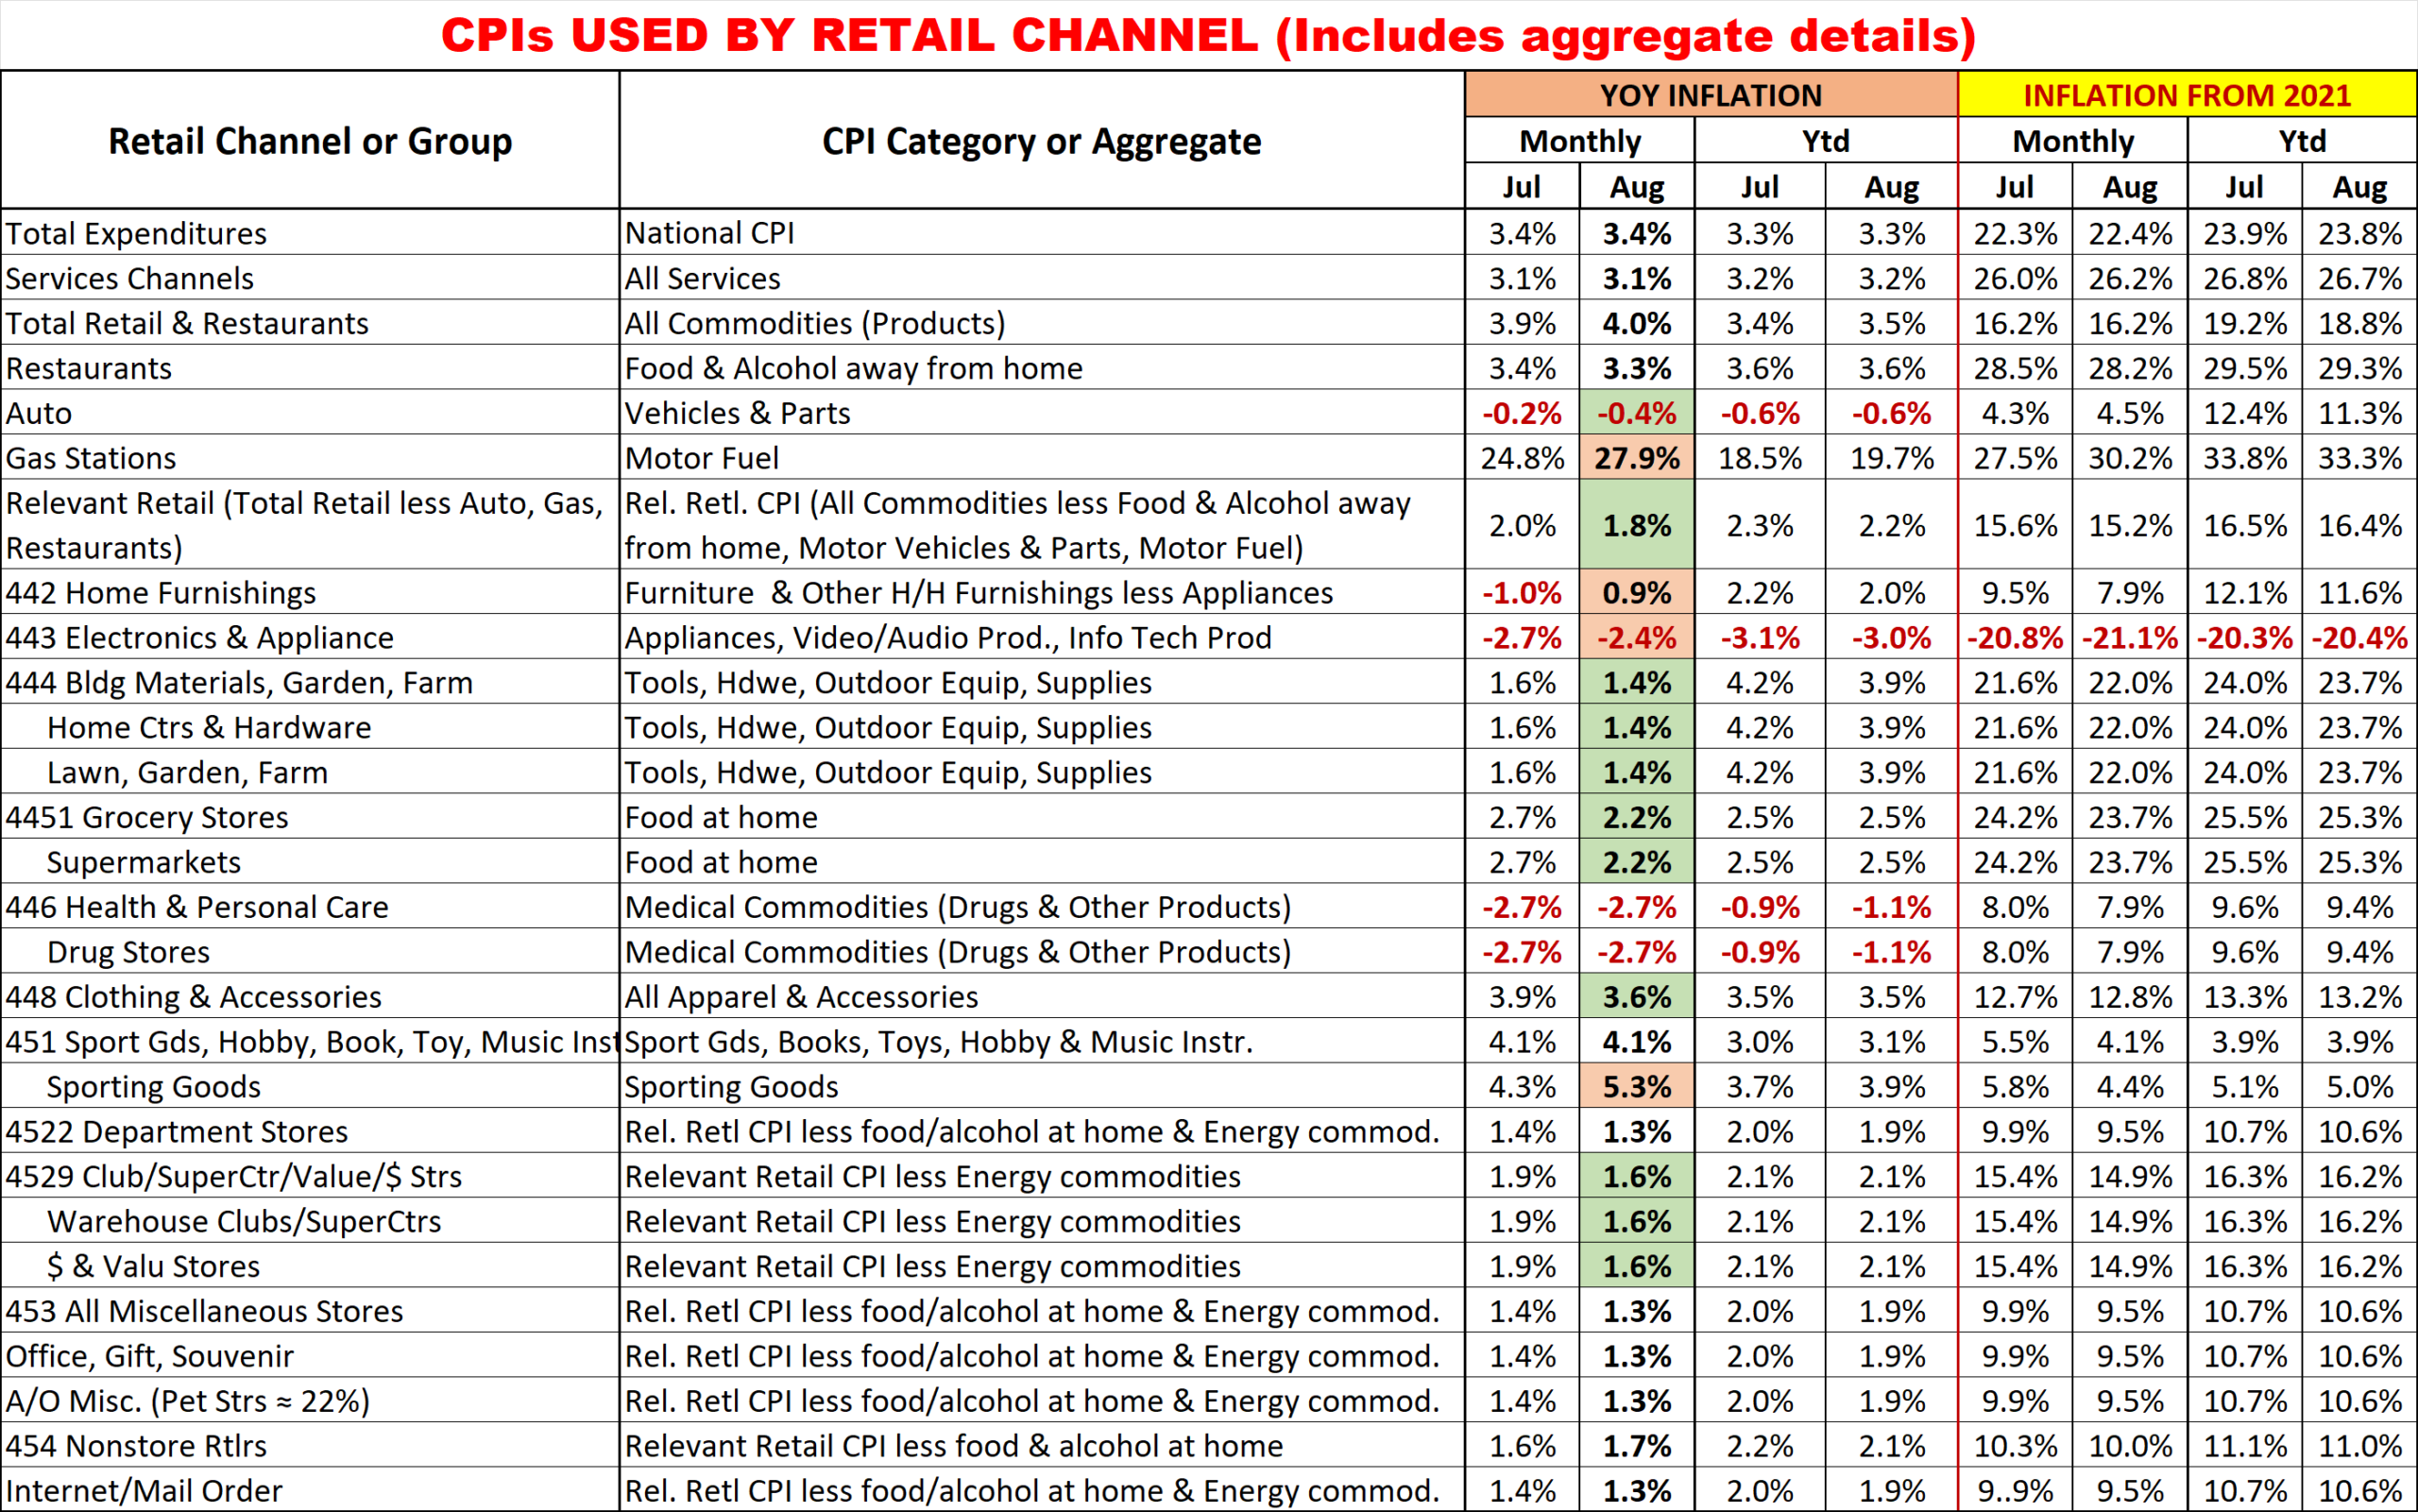 Here are some answers to some obvious questions. Note: Inflation slowed slightly for most.
- Why is the group for Nonstore different from the Internet?
- Non-store is not all internet. It also includes Fuel Oil Dealers, the non-motor fuel Energy Commodity.
- Why is there no Food at home included in Nonstore or Internet?
- Online Grocery purchasing is becoming popular, but almost all is from companies whose major business is brick ‘n mortar. These online sales are recorded under their primary channel.
- 5 Channels have the same CPI aggregate but represent a variety of business types.
- They also have a wide range of product types. Rather than try to build aggregates of a multitude of small expenditure categories, it seemed better to eliminate the biggest, influential groups that they don’t sell. This method is not perfect, but it is certainly closer than any existing aggregate.
- Why are Grocery and Supermarkets only tied to the Grocery CPI?
- According to the Economic Census, 76% of their sales comes from Grocery products. Grocery Products are the driver. The balance of their sales comes from a collection of a multitude of categories.
- What about Drug/Health Stores only being tied to Medical Commodities?
- An answer similar to the one for Grocery/Supermarkets. However, in this case Medical Commodities account for over 80% of these stores’ total sales.
- Why do SuperCtrs/Clubs and $ Stores have the same CPI?
- While the Big Stores sell much more fresh groceries, Groceries account for ¼ of $ Store sales. Both Channels generally offer most of the same product categories, but the actual product mix is different.

Leave a Reply
Want to join the discussion?Feel free to contribute!